


EN
Should New Infrastructure Unit Require Action From American Electric Power (AEP) Investors?
- American Electric Power recently formed AEP Infrastructure to combine competitive generation, development and energy solutions, targeting large-load demand with projects such as the proposed Longview Power Plant acquisition and a 20-year Google fuel cell agreement.
- The company also reported higher third quarter 2026 revenue and net income year on year, along with updated earnings guidance that tightens the focus on how American Electric Power funds and executes its expanding capital program.
- This article examines how American Electric Power's new AEP Infrastructure unit could reshape the investment narrative built around its capital plan.
Scan American Electric Power's peers that are targeting the same large-load and grid buildout trend by reviewing a hand picked group of 42 power grid technology and infrastructure stocks.
American Electric Power Company Investment Narrative Recap
To own American Electric Power Company, you need to believe the huge capital plan can be executed while keeping credit metrics intact and regulators onside. According to Andrei_Niculescu, an investor in the Simply Wall St Community, the current plan leans heavily on new debt and equity, so funding costs and dilution remain the main near term pressure points.
The creation of AEP Infrastructure and the third quarter 2026 beat do not remove that funding risk. They do, however, sharpen the short term catalyst. Investors are now watching how quickly contracted projects move into rate mechanisms or long term contracts that support cash generation rather than stretching the balance sheet.
The most relevant recent announcement is the third quarter 2026 earnings report. American Electric Power Company reported revenue of US$6,832 million and net income of US$1,187 million for the quarter, with diluted EPS from continuing operations of US$2.16. For the first nine months, revenue was US$18,297 million and net income US$2,774 million.
Those figures frame how much room management has to support the capital plan and AEP Infrastructure build out. Earnings guidance for 2026, with GAAP EPS expected between US$6.11 and US$6.41, becomes a practical hurdle. Strong delivery here would help offset concerns Andrei_Niculescu raised around interest coverage, dividend funding and the large program of debt issuance.
In this narrative, Andrei_Niculescu arrives at a fair value of US$133.00 for American Electric Power by assuming revenue expands 9.9% a year and the business settles at a 14.2% future profit margin. Together, these assumptions support the earnings and P/E inputs used in the valuation.
Uncover why American Electric Power Company's fair value indicates a 4% potential upside to its current price that could narrow quickly.
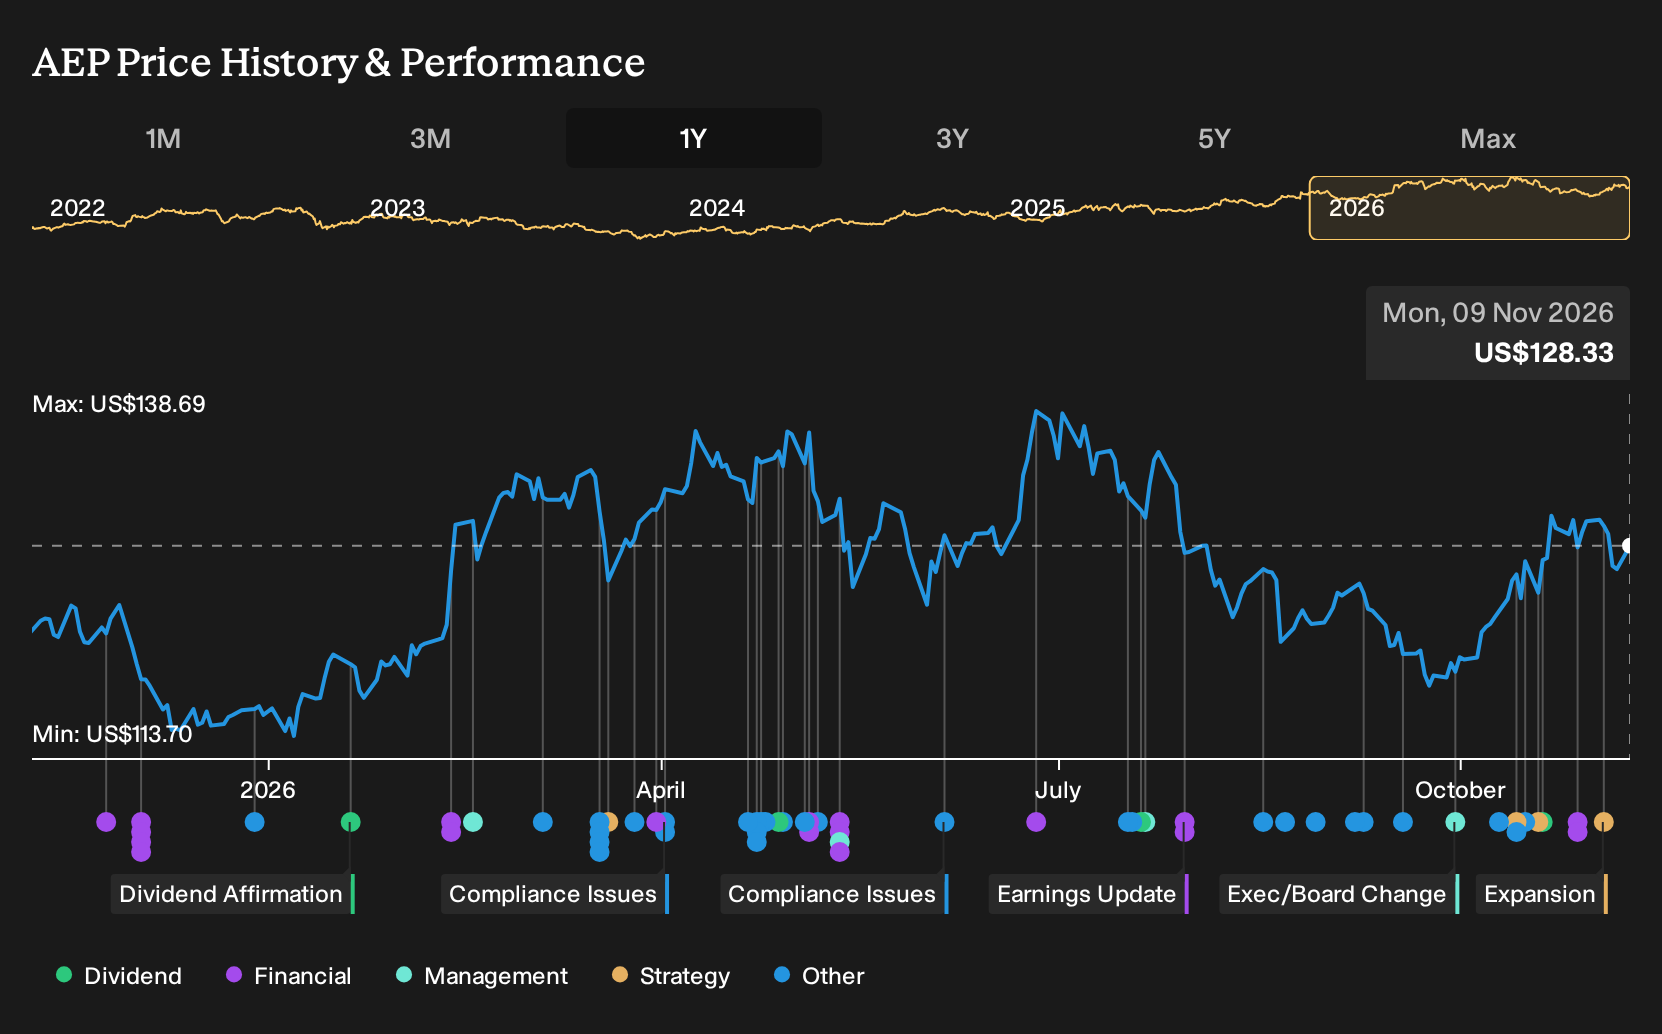
Exploring Other Perspectives
The five fair value estimates from the Simply Wall St Community span roughly US$113 to about US$143, so you are looking at a wide band on American Electric Power Company. That spread reflects how differently private investors treat AEP Infrastructure, potential ERCOT outcomes and the US$44.4b debt plan. Explore those contrasting views before deciding how you frame the story.
Explore 4 other American Electric Power Company fair value estimates, including one that indicates up to 12% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Electric Power Company research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Electric Power Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Electric Power Company?
If you want to pressure test your thesis on American Electric Power Company against other possibilities, the Simply Wall St Screener can help you quickly spot businesses with different risk and reward profiles that still fit your style.
- If capital preservation sits high on your list, you can filter for companies with steadier profiles by scanning a curated set of 30 resilient stocks with low risk scores that score well on financial risk checks.
- If dependable income matters more to you, you can compare American Electric Power Company's payout with a group of 6 dividend fortresses that pair yield with balance sheet support.
- If you want to hunt for less crowded ideas, you can widen your search to a collection of 19 high quality undiscovered gems where fundamentals, not headlines, drive the story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com