


EN
How Lithium Royalties Are Shaping The Case For Altius Minerals Stock
- Altius Minerals has been drawing attention as a royalty and streaming business with lithium exposure tied to key producing regions, giving investors access to lithium-linked production and processing revenue without operating mines directly.
- The recent focus on its lithium royalty portfolio highlights how Altius Minerals can link long life resource income to electric vehicle and energy storage battery demand while avoiding direct mining cost inflation and project execution risk.
- We will now look at how Altius Minerals' lithium royalty exposure could shape the broader investment narrative for the business.
Scan royalty and lithium peers moving on the same battery demand story as Altius Minerals with our curated list of 33 best rare earth metal stocks.
Altius Minerals Investment Narrative Recap
To own Altius Minerals, you need to believe the royalty model can keep converting a diversified mix of potash, copper, gold, lithium and renewable power into long life cash flows while avoiding direct operating exposure. The analyst consensus Narrative on Simply Wall St points to revenue that analysts expect to grow 18.3% a year, with earnings moving in the opposite direction as non cash items normalise.
The key near term swing factor is how quickly management puts the roughly CA$540 million liquidity pool to work in new royalties or buybacks. The biggest risk is that this capital sits idle or ends up in shorter duration funding deals, while counterparties take longer than hoped to advance projects like CAMI, Curipamba and Chapada expansions.
Recent lithium focused attention effectively acts like an informal update on the portfolio rather than a hard catalyst. The lithium royalties connect to the same thesis as the emerging U.S. renewable power book, where strong underlying power fundamentals meet a financing market that has been cautious. This combination could influence how fast royalty volumes build.
Against that backdrop, the most interesting operational thread is the ramp up of U.S. renewable royalties mentioned in the analyst consensus Narrative on Simply Wall St. If more of the current interconnection and funding relationships convert into long duration royalties, that would directly affect how Altius Minerals deploys its large cash balance and how much of future earnings comes from long life contracts instead of shorter term financial income.
Altius Minerals' analyst narrative points to forecast revenue of CA$155.6 million and earnings of CA$97.7 million by 2029, based on expected revenue growth of 35.0% a year and an earnings move from CA$294.9 million today to the 2029 consensus, which implies a decline of about CA$197 million over that period.
Uncover why Altius Minerals' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
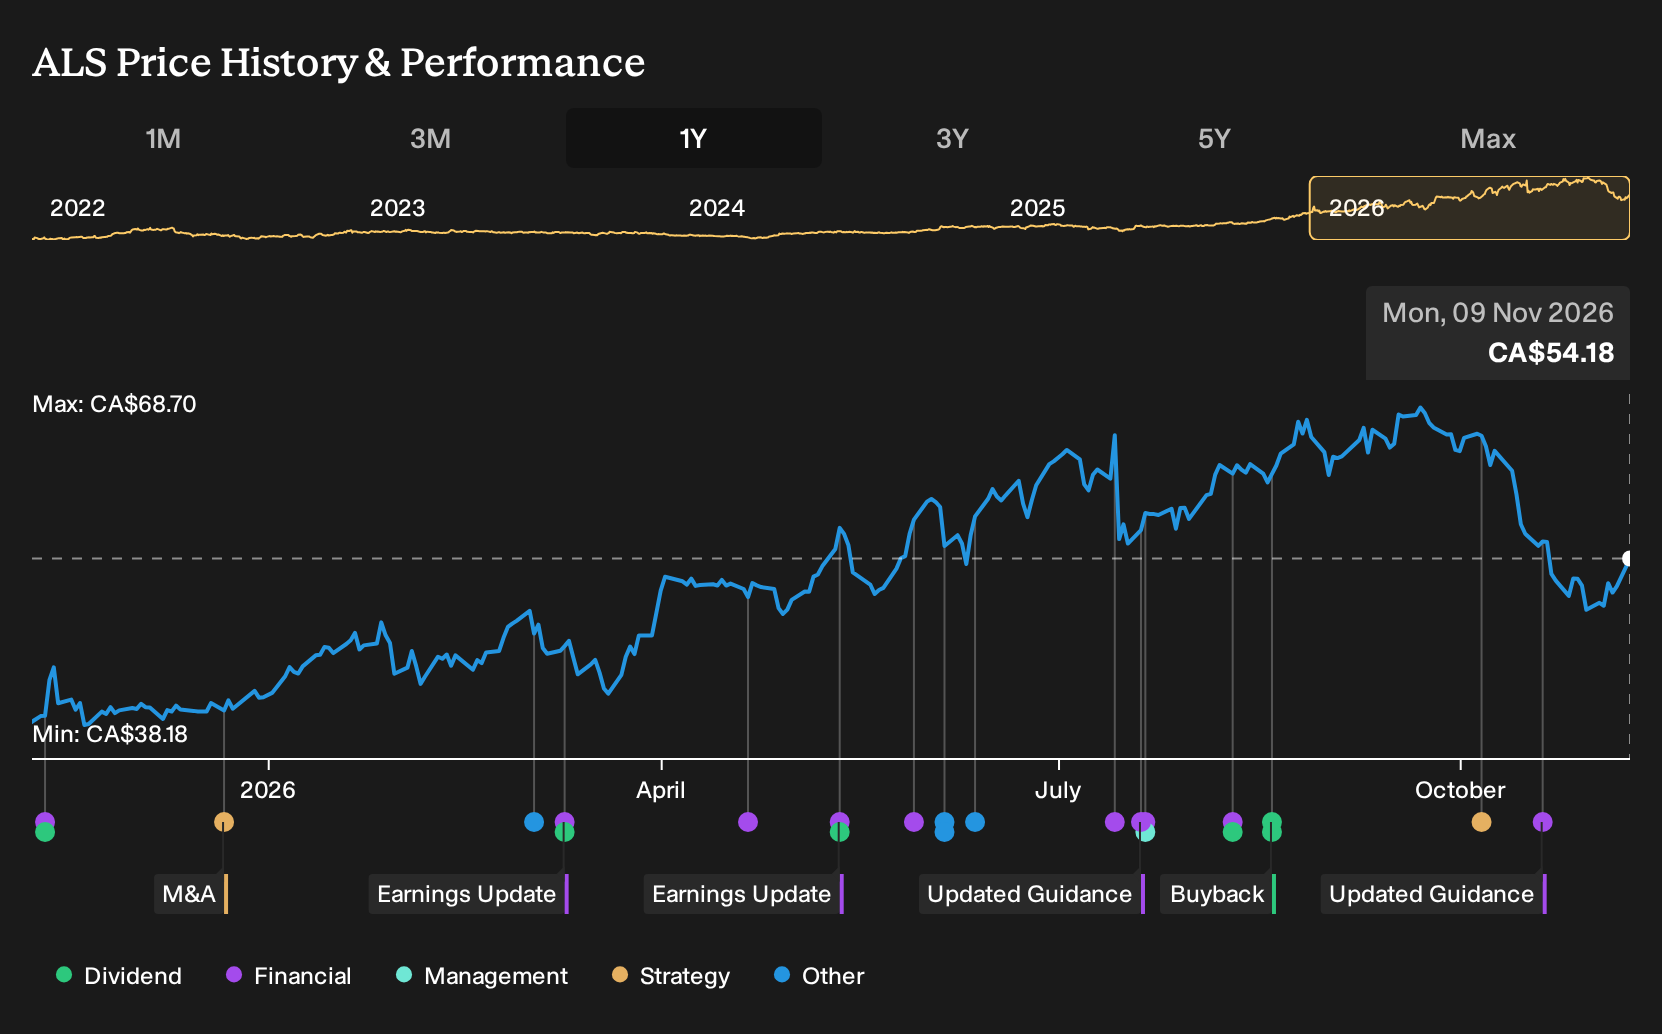
Exploring Other Perspectives
One alternate angle on Altius Minerals leans hard into lithium risk. The most pessimistic analysts worry that new battery chemistries and extra supply could hit royalty income, which helps explain why they were only pencilling in CA$145.5 million of revenue and CA$66.7 million of earnings by 2029 before this news. Those projections sketch a very different story to the baseline, and fresh information on lithium demand or project timing could easily shift both narratives.
Explore 2 other Altius Minerals fair value estimates, including one that suggests it could be worth just CA$59.71.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Altius Minerals research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Altius Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Altius Minerals' overall financial health at a glance.
Looking for more investment ideas beyond Altius Minerals?
Once you have a view on Altius Minerals, it can help to compare that thesis with other opportunities that share some of the qualities you care about most, whether that is value, resilience or balance sheet strength.
- If you are hunting for businesses that the market may be pricing cautiously relative to their fundamentals, scan our curated set of 6 high quality undervalued stocks that meet a blend of quality and value filters.
- For readers who care most about stability and financial resilience, narrow your focus to companies in the 9 resilient stocks with low risk scores and see how they manage volatility and downside risk.
- If balance sheet strength is non negotiable for you, start with the list of solid balance sheet and fundamentals (5 results) and compare how these firms fund growth and manage debt.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com