


EN
Standex International (SXI) Raises FY2027 Outlook, But Does Valuation Still Have Room
Standex International (SXI) has drawn fresh attention after raising its Fiscal 2027 outlook to high single digit total sales growth, alongside reporting first quarter results that showed higher sales and net income versus a year earlier.
Recent trading shows how quickly sentiment around Standex International can shift. The share price jumped 8.37% in the last session to US$247.47, yet it is still down 24.44% over 90 days and 13.17% over 30 days. At the same time, the year-to-date share price return of 10.06%, alongside a 5-year total shareholder return of 120.21%, points to longer-term momentum that contrasts with the recent pullback.
Compare Standex International's setup with a curated group of industrials that pair solid balance sheets with fundamental strength using our list of solid balance sheet and fundamentals (25 results)
The reset in Standex International's share price after strong guidance and a fresh buyback authorization raises a practical question for investors. Is most of the easy upside already in the rear-view mirror, or does valuation still offer real headroom from here?
Most Popular Narrative: 27% Undervalued
On the analyst consensus Narrative on Simply Wall St, Standex International screens as undervalued, with a central fair value estimate of $338.40 against the last close of $247.47. That gap depends on whether the grid and aerospace build out can translate into the earnings power analysts are modeling.
The accelerating global shift toward electrification, grid modernization, and data center infrastructure continues to support Standex International’s plan for Standex Grid to reach roughly US$340 million to US$440 million of sales by fiscal 2030, which would directly influence revenue growth and earnings power.
See why 1 investors see Standex International as 27% undervalued.
Result: Fair Value of $338.40 (UNDERVALUED)
Still, the bullish Standex International narrative can easily wobble if organic growth in Electronics and Aerospace & Defense cools or if new grid investments earn weak returns.
Find out about the key risks to this Standex International narrative.
Another View: What Multiples Say About Standex International
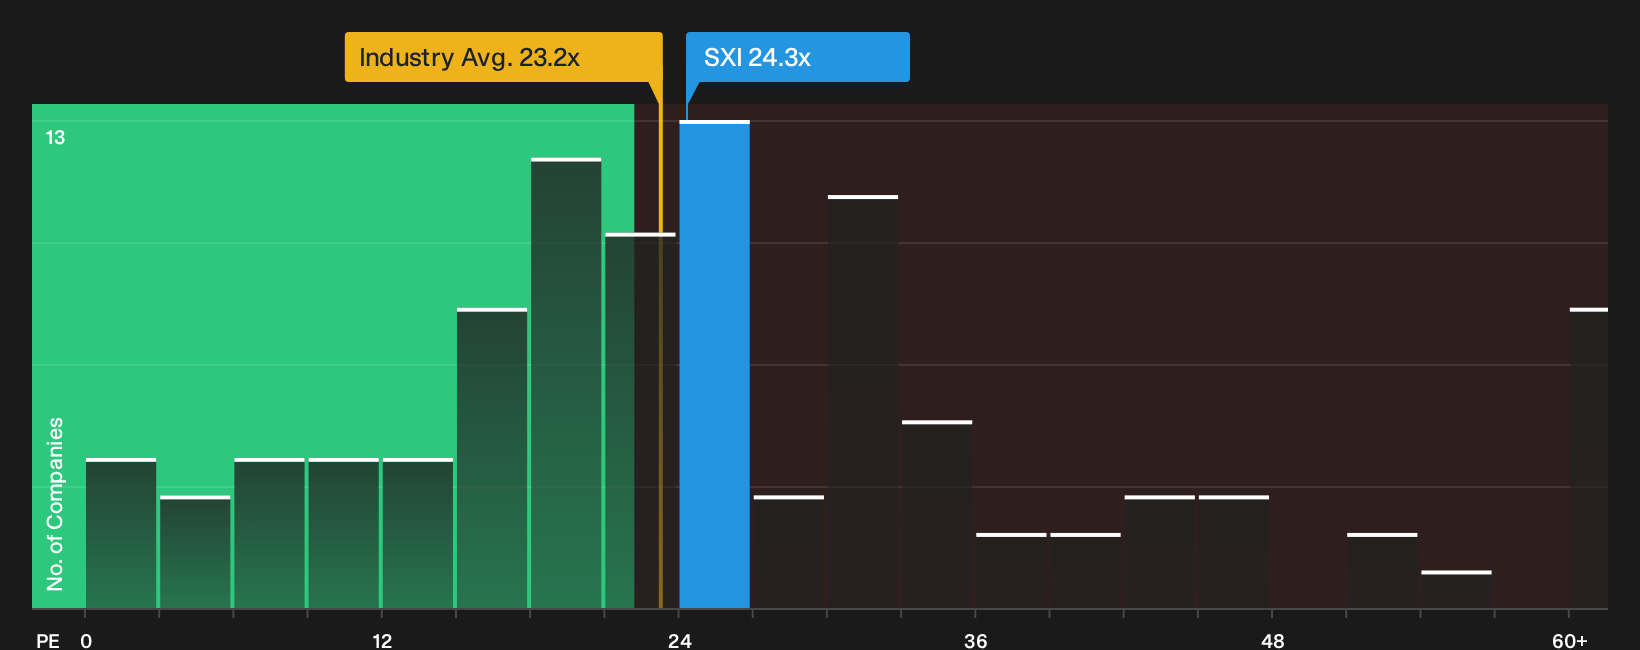
On simple earnings multiples, Standex International screens as expensive. The stock trades on a P/E of 26.3x, compared with 23.2x for the US Machinery group and a fair ratio estimate of 21.4x. That gap points to less room for error if growth or margins underperform expectations.
When a share trades well above both peers and its own fair ratio, investors are effectively paying upfront for a stronger future. The question is whether you are comfortable underwriting that premium while one off gains, insider selling, and slower forecast growth than the wider US market all sit in the background.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Standex International story today. Put the numbers, risks, and upside potential side by side and pressure test them for yourself with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Standex International?
If Standex International has your attention, do not stop here. Use the Simply Wall St screener to line up fresh candidates before the crowd moves on.
- Target steadier compounding by scanning companies that combine earnings strength with lower perceived risk using the 30 resilient stocks with low risk scores.
- Hunt for quality on sale by focusing on businesses that pair robust fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- Build a watchlist of tomorrow's potential market favorites by filtering for financially sound smaller players with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com