


EN
Is Nissui (TSE:1332) Undervalued On Half Year Sales Growth And Softer Profitability?
Half year results put Nissui’s profitability under the microscope
Nissui (TSE:1332) has put fresh numbers on the table with half year earnings to September 30, 2026, providing new detail on how sales growth and softer profit margins are interacting.
Nissui’s latest half year report lands after a mixed run in the market, with the share price up 1.61% over the past day but down 6.44% over the week and 16.95% over the past three months. That softer short term share price return sits alongside a 1 year total shareholder return decline of 4.35%, although investors who have held through the last three and five years have seen total shareholder returns of 59.46% and 93.01%. This keeps attention on how current profit margins evolve from here.
Compare Nissui’s softer margins with other businesses that pair solid earnings profiles and balance sheets in our curated list of solid balance sheet and fundamentals (23 results).
Nissui now trades well below both analyst targets and an estimated fair value, while profit margins have softened and the share price has retreated. Is the discount generous or simply acknowledging those risks?
Preferred Price-to-Earnings of 11.8x: Is it justified?
Nissui closed at ¥1,038.5 while trading on a P/E of 11.8x, a level that points to a lower valuation compared with both its own fair ratio and the wider food sector.
The P/E ratio compares the current share price to earnings per share, so it reflects how much investors are paying for each unit of profit. For a business like Nissui with exposure to food products and marine operations, this measure anchors expectations about the durability of earnings through different demand and cost cycles.
Management has delivered earnings growth of 9.9% per year over the past five years, while current net profit margins of 2.7% are below last year’s 3.2%. That combination of a relatively low 11.8x P/E, lower profitability in the latest period and earnings that are forecast to grow around 8.96% a year suggests the market is pricing in some caution about how comfortably Nissui can compound profits from here.
The gap to peers is clear. Nissui trades on an 11.8x P/E compared with 15.8x for the broader JP Food industry and 27x for its direct peer set. These levels are materially higher and point to investors assigning richer earnings multiples elsewhere. Regression work on the fair P/E ratio indicates a level of 20.1x, which is significantly above where Nissui changes hands and highlights how far sentiment could shift if confidence in its earnings profile improves.
Explore the SWS fair ratio for Nissui.
Result: Price-to-Earnings of 11.8x (UNDERVALUED)
Still, thinner net margins and a share price that has fallen over the past three months leave Nissui exposed if earnings or sector sentiment weaken.
Find out about the key risks to this Nissui narrative.
Another view on Nissui’s value
The P/E gap already looks wide for Nissui, yet the SWS DCF model goes further and suggests the shares trade at a steep discount. The current price of ¥1,038.5 compares with an estimated future cash flow value of ¥2,179.99. This raises a different question: is this simply a value trap, or is the market underestimating those cash flows?
For a closer look at how that cash flow based estimate is built, including the key assumptions that could move it up or down, Look into how the SWS DCF model arrives at its fair value.
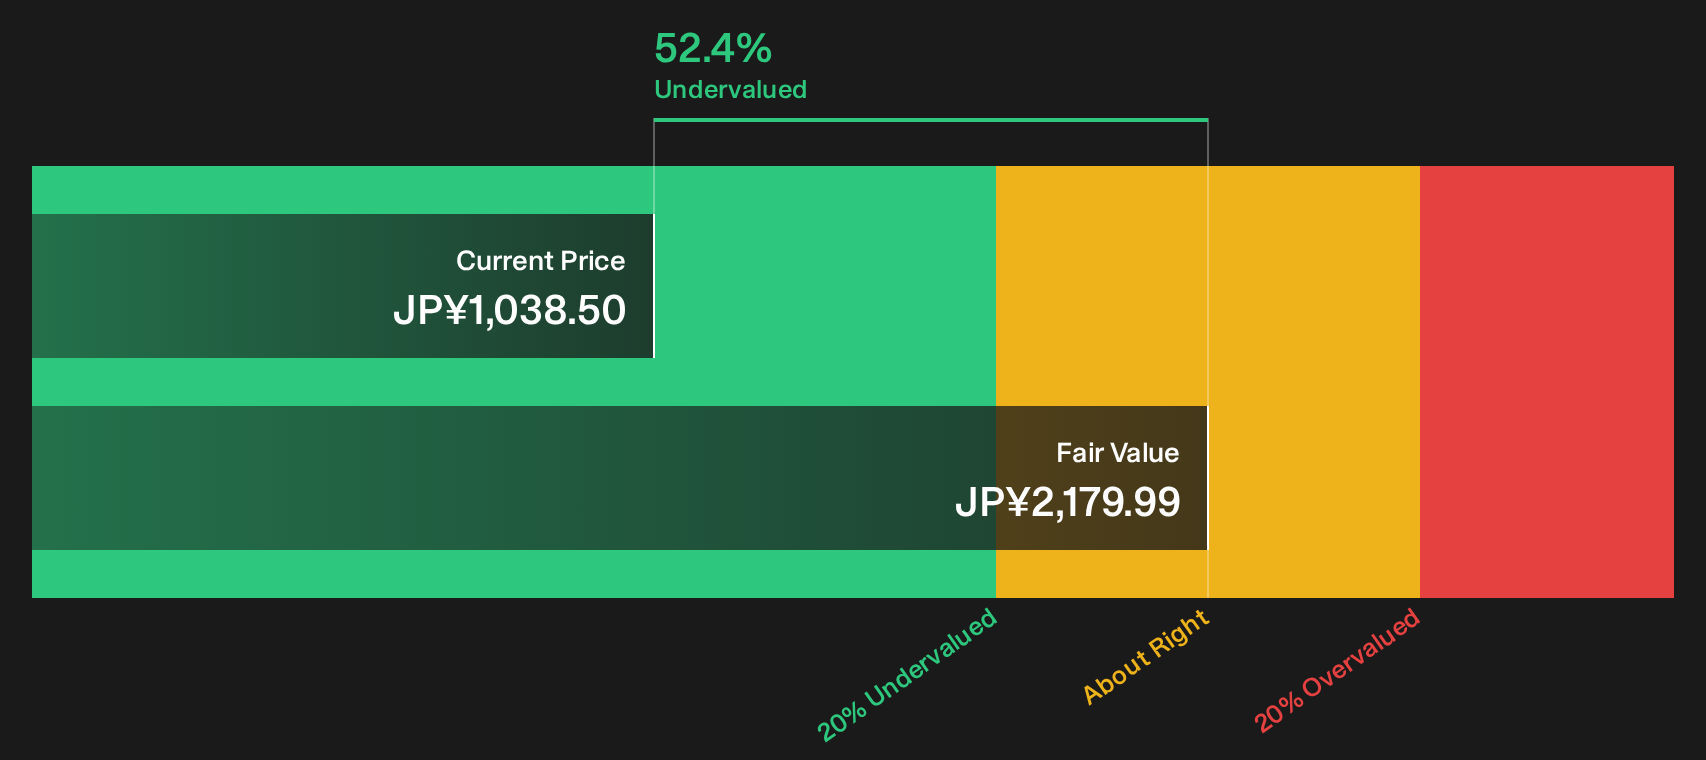
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nissui for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 22 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nissui can feel uncomfortable, so move quickly, test the numbers yourself and pressure check both sides of the story with 3 key rewards and 2 important warning signs
Looking for more Nissui sized investment ideas?
If Nissui has sharpened your focus on price, quality and risk, do not stop here. Broader opportunities could be passing by while you wait.
- Target higher potential upside by scanning companies that combine quality fundamentals with lower valuations through the 76 high quality undiscovered gems.
- Prioritise resilience first and hunt for businesses with steadier profiles using the 18 resilient stocks with low risk scores.
- Lock in income ideas by reviewing companies with stronger yields and payout profiles via the 35 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com