


EN
Is Quarterly Loss Altering The Investment Case For ATS (TSX:ATS)?
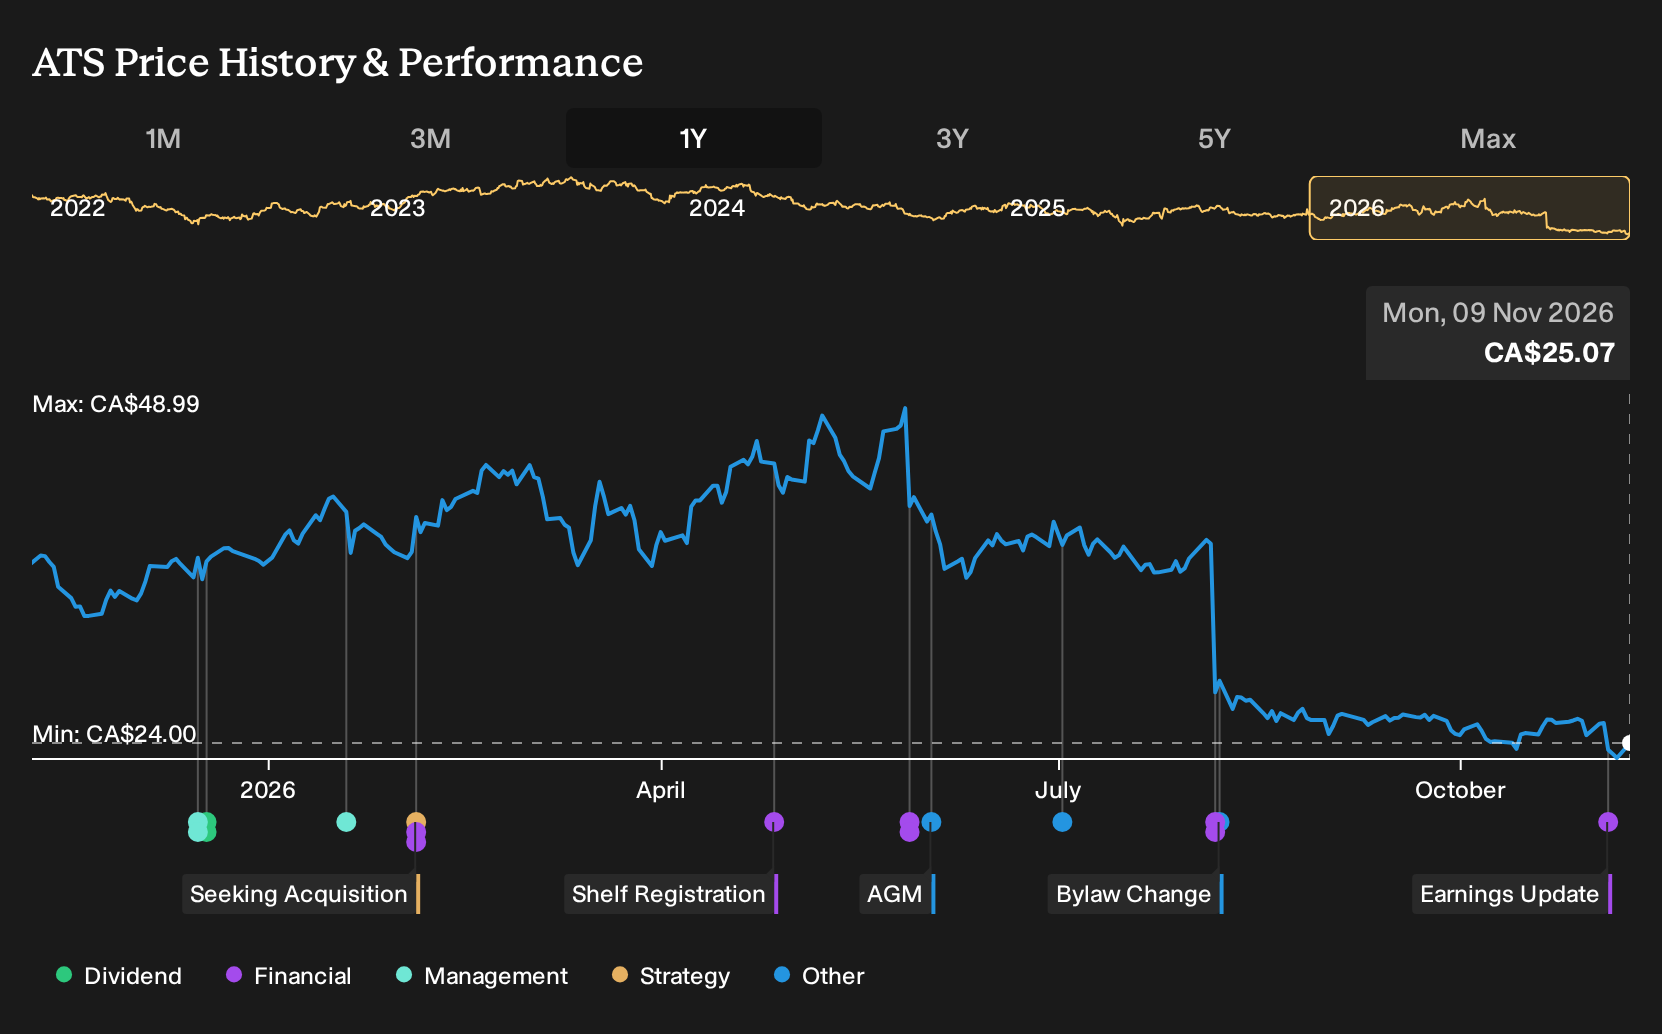
- ATS Corporation reported second quarter 2026 results with sales of CA$665.77 million and a net loss of CA$4.95 million, compared with higher revenue and positive earnings in the same period a year earlier.
- The swing from profit to loss over both the quarter and first half, along with softer sales, points to meaningful pressure on ATS's operating model and cost structure.
- Investors will now observe how ATS's swing to a quarterly net loss reshapes the existing investment narrative around margin expansion and services.
ATS Investment Narrative Recap
To own ATS today, you need to believe the fixed cost transformation and shift toward higher margin services can still reshape the earnings profile, even with the recent quarterly loss. The analyst consensus Narrative on Simply Wall St leans heavily on that 18 month cost program and a richer services mix as the core earnings driver.
The latest results, with softer sales and a net loss over both the quarter and first half, put more pressure on that thesis in the near term. Execution risk on cost savings, order volatility in transportation, life sciences and energy, and interest coverage already matter more as management works through this reset.
The fixed cost transformation program described in the analyst consensus Narrative on Simply Wall St is the clearest operational reference point against the new earnings numbers. Management is targeting about CA$20 million of annualized savings and roughly 500 basis points of operating margin uplift from European cost actions and tighter process discipline.
With a quarter where ATS moved from profit to loss, investors get a more direct test of whether that program and the services mix shift can offset weaker transportation volumes and a softer backlog. Delivery against these internal milestones, more than any single contract win, now appears to be the key short term catalyst and risk.
ATS' projections estimate CA$3.1b in revenue and CA$307.3 million in earnings by 2029. This is based on an assumed 2.7% annual revenue growth rate and an earnings increase of about CA$298.7 million from CA$8.6 million today.
Uncover why ATS' fair value indicates a 35% potential upside to its current price before that discount narrows.
Exploring Other Perspectives
One alternate view on ATS focuses on execution risk in the cost transformation. The most cautious analysts already worked with slower annual revenue growth of about 1.9% and earnings of roughly CA$253.1 million by 2029. After a fresh quarterly loss, that more pessimistic path may feel closer to home. Use it as a contrast point and explore how your own expectations differ before this earnings shock is fully reflected in forecasts.
Explore 2 other ATS fair value estimates, including one that suggests it could be worth just CA$32.60!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ATS research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ATS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATS' overall financial health at a glance.
Looking For More Ideas Beyond ATS?
If this ATS update has you rethinking your watchlist, it can help to broaden the field and compare what you see here with other opportunities using the Simply Wall St Screener.
- For readers who care most about resilience, scan a curated set of 9 resilient stocks with low risk scores that pair steadier fundamentals with lower risk scores.
- If balance sheet strength is your priority, anchor your research around the list of solid balance sheet and fundamentals (5 results) to focus on companies with cleaner debt profiles and healthier financial footing.
- Those hunting for underfollowed opportunities can use the 7 high quality undiscovered gems to surface businesses with strong fundamentals that may not be on every investor's radar yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com