


EN
Learn Why The Bull Case For Western Midstream Partners Stock Could Change Following Record Gas Throughput
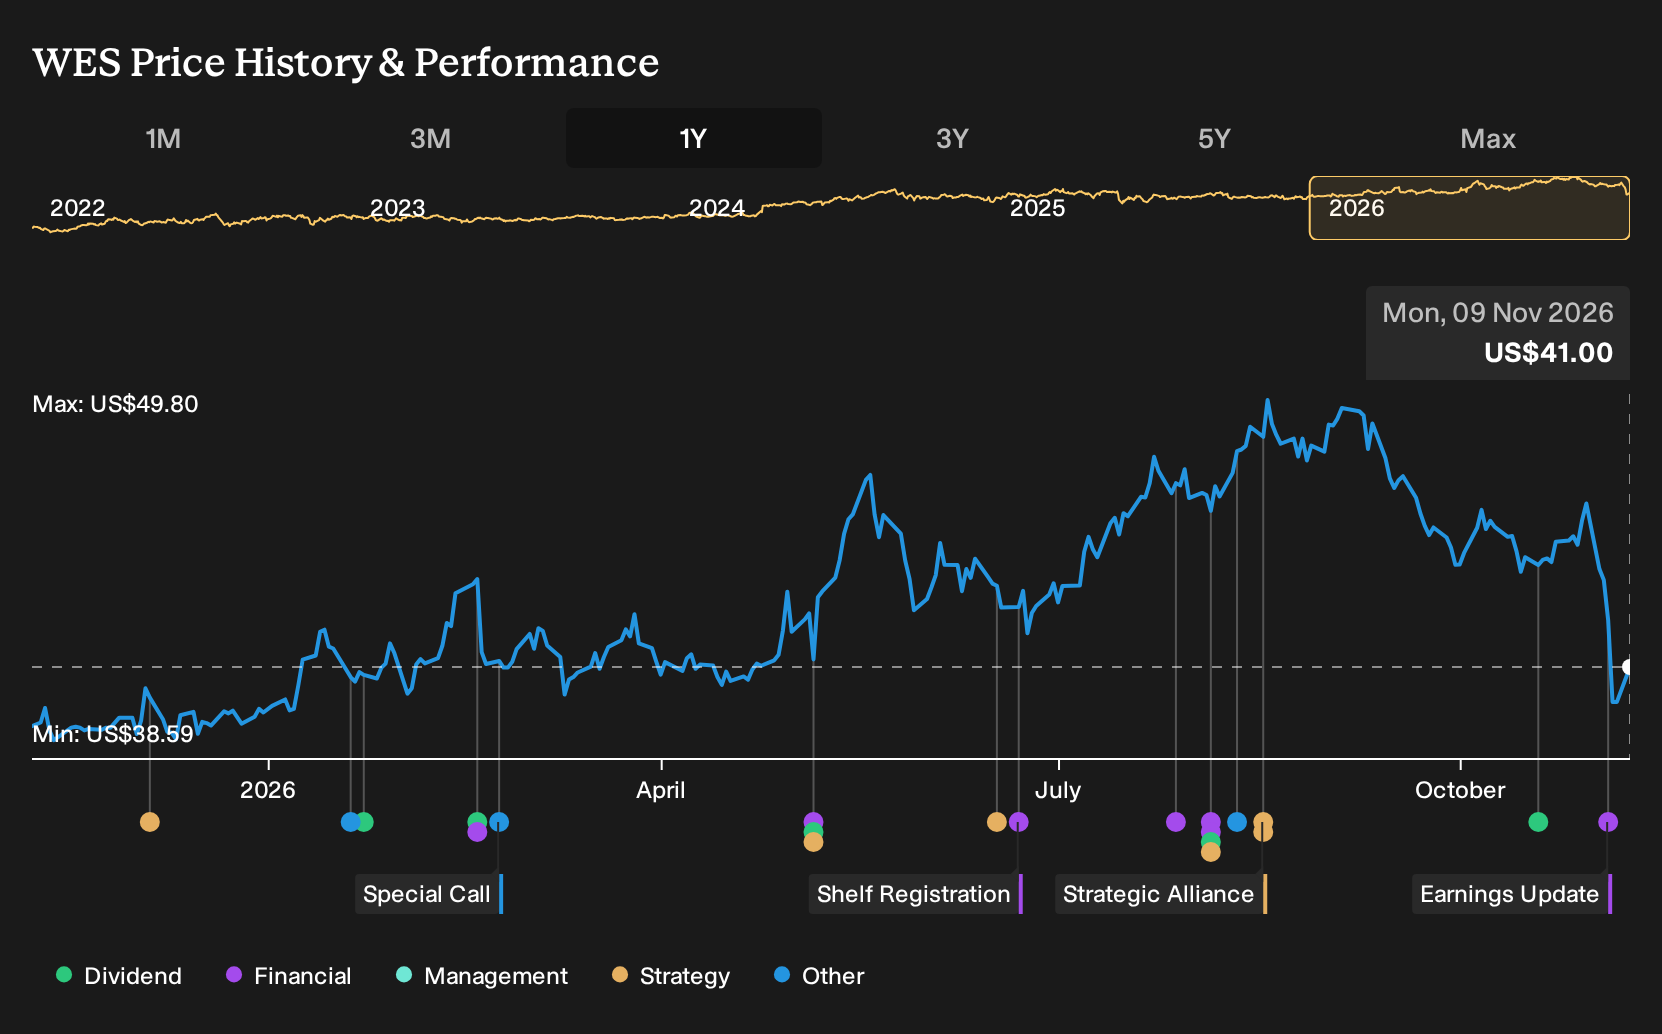
- Western Midstream Partners reported third quarter 2026 revenue of US$1,194.22 million, net income of US$324.78 million, and adjusted EBITDA of US$708 million, alongside record natural gas throughput of 5.9 billion cubic feet per day.
- The partnership paired higher revenue and record volumes with guidance that 2026 adjusted EBITDA is expected to exceed the midpoint of its range, while also advancing growth projects such as the Pathfinder produced water pipeline and the North Loving II processing train.
- We will now look at how Western Midstream Partners’ investment narrative could be reshaped by record throughput and management’s higher EBITDA outlook.
Western Midstream Partners Investment Narrative Recap
To own Western Midstream Partners, you need to believe its fee based model can keep turning record throughput into steady cash flow, while major Delaware Basin projects such as Pathfinder and North Loving II come online on time and on budget. The latest quarter supports that operating story, with higher revenue, record gas volumes and a 12% rise in adjusted EBITDA.
The near term swing factor is still producer activity in key basins. Management’s expectation that 2026 adjusted EBITDA will land above the midpoint of guidance relies on that remaining supportive. The biggest risk remains heavy capital commitments and high debt if drilling or completions slow and those new assets end up under utilized.
The analyst consensus narrative on Simply Wall St ties a lot of the long term potential to Pathfinder, North Loving II and integration of Brazos Delaware II. Third quarter results matter for that storyline because they show Western Midstream Partners handling 5.9 billion cubic feet per day of gas, with adjusted EBITDA of US$708 million, while still spending into growth.
For you, the key question is whether today’s record throughput and guidance upgrade increase confidence that future fee based projects will be well filled, or simply raise the stakes on execution risk and balance sheet pressure. If producer activity or basin mix shifts away from expectations, the same capital program that supports earnings potential could weigh on returns.
Western Midstream Partners’ current analyst story implies revenues of US$5.2b and earnings of US$1.7b by 2029, built on forecast revenue growth of 6.2% a year and an earnings increase of about 31% from roughly US$1.3b today to that US$1.7b level.
Uncover why Western Midstream Partners' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value marks from the Simply Wall St Community span roughly US$49.69 to US$128.91, so you are seeing very different takes on Western Midstream Partners. Set that spread against record throughput, higher 2026 EBITDA guidance and rising capital commitments, and you get sharply contrasting views on future resilience. Explore them.
Explore another Western Midstream Partners fair value estimate, including one that suggests it could be worth just $49.69!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Western Midstream Partners research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Western Midstream Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Western Midstream Partners' overall financial health at a glance.
Looking for more investment ideas beyond Western Midstream Partners?
Once you have formed a view on Western Midstream Partners, it can help to widen the lens and compare it with other opportunities that share some of the income, quality or risk profile you are targeting. The Simply Wall St Screener gives you a quick way to do that across thousands of listed businesses.
- If you want yield that aims to balance income with balance sheet strength, start with a curated 6 dividend fortresses that focuses on durability rather than just headline payout.
- For investors who care most about paying a reasonable price for quality, filter the market using a 33 high quality undervalued stocks that combines solid cash generation with conservative financials.
- If you prefer to keep risk in check while still staying in equities, lean on a 30 resilient stocks with low risk scores that screens for resilience on both volatility and fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com