


EN
Does Project Approvals Change The Bull Case For TC Energy Stock (TSX:TRP)?
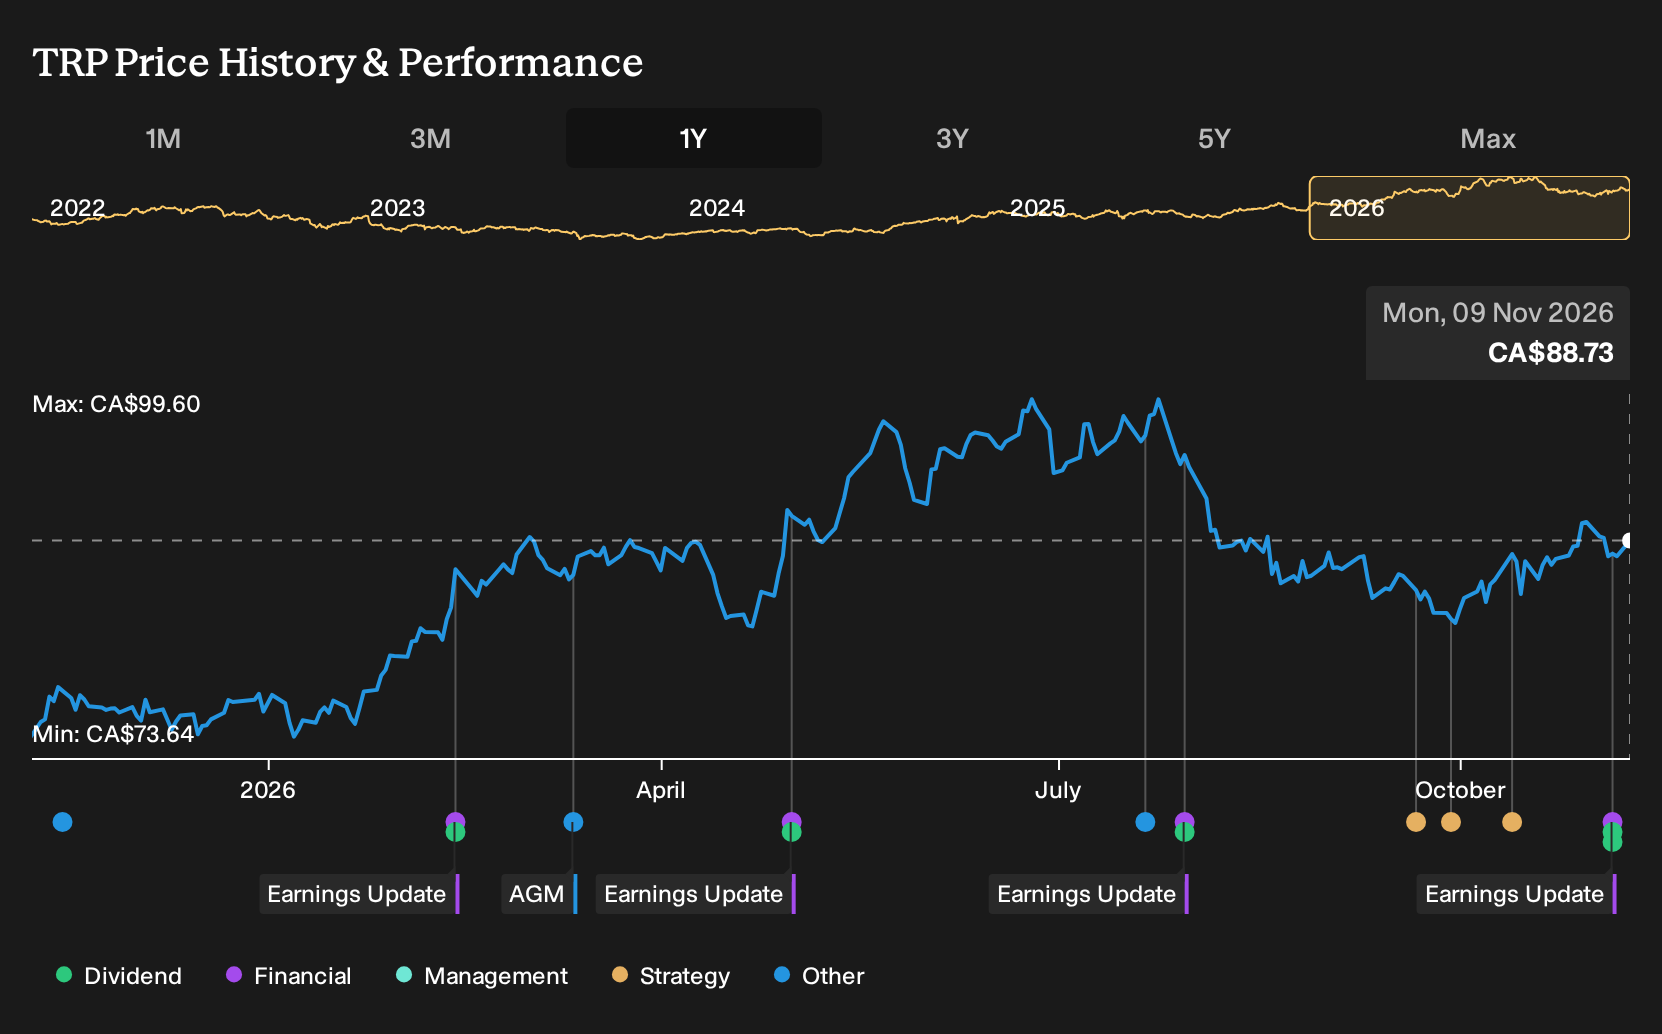
- TC Energy reported third quarter 2026 net income of C$1,054 million and nine month net income of C$2,997 million, alongside fresh approvals for roughly C$3 billion of contracted North American pipeline expansions and new common and preferred dividend declarations.
- The combination of higher reported earnings, a C$30 billion project backlog, and new long term contracted gas projects tied to data centre and LNG demand highlights how TC Energy is leaning into capacity needs from power hungry computing and export facilities.
- We will now look at how TC Energy's expanded pipeline program and raised earnings outlook could reshape the broader investment narrative.
Scan beyond TC Energy and see how other infrastructure plays are lining up for rising data centre and LNG demand with our hand picked 42 power grid technology and infrastructure stocks.
TC Energy Investment Narrative Recap
To own TC Energy, you need to be comfortable with a capital heavy North American gas infrastructure story that leans on long term contracts and a C$30b project backlog. The analyst consensus Narrative on Simply Wall St focuses on execution of that backlog and Bruce Power to support future earnings and cash flow flexibility.
Right now the key short term swing factor is project delivery and cash generation versus debt and interest costs. The latest earnings beat, higher comparable EBITDA outlook, and strong year to date net income highlight that execution angle. They do not remove the pressure from high leverage or the risk of labour and supply chain bottlenecks.
Among the recent updates, the new quarterly common dividend of C$0.8775 per share looks most relevant to the current TC Energy story. It signals that the board is comfortable maintaining a sizable cash distribution while the business increases capital spending on approved gas expansions and power projects.
For you as a shareholder, that dividend decision ties directly into the main catalysts and risks. Higher EBITDA guidance and a long contracted backlog support ongoing payouts. At the same time, analysts still note that interest payments and the dividend are not fully covered by earnings and free cash flow, so balance sheet and execution discipline remain central.
TC Energy's narrative projects CA$18.9b in revenue and CA$4.7b in earnings by 2029, based on analyst forecasts that assume 6.5% yearly revenue growth and an earnings increase of about CA$1.0b from CA$3.7b today.
Discover why TC Energy's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about C$36 to C$100, which shows how far apart views on TC Energy can be. Those opinions were set before the recent earnings beat, higher EBITDA outlook, and fresh dividend affirmations, so you may want to weigh how stronger reported cash generation and high net debt could both reshape that spread.
Explore another TC Energy fair value estimate, including one that suggests as much as 59% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider forming your own view.
- A great starting point for your TC Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TC Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TC Energy's overall financial health at a glance.
Looking for more TC Energy style ideas?
If the TC Energy story has you thinking about how to position your portfolio, it can help to widen the lens and compare it with other companies that have very different risk and income profiles.
- For investors who care most about downside protection and steadier business profiles, start with a 9 resilient stocks with low risk scores that may better match your comfort level.
- If reliable income streams matter to you, consider companies that aim to balance yield and resilience by reviewing our curated 3 dividend fortresses.
- When you want to hunt for under the radar opportunities with stronger fundamentals, cast a wider net using a targeted 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com