


EN
Is Eli Lilly (LLY) Fully Priced After Raising Guidance And Expanding GLP 1 Access?
Eli Lilly (LLY) just paired blockbuster GLP-1 demand with stronger guidance and fresh digital health partnerships, giving investors a new look at how its obesity and diabetes franchise reaches patients.
Those telehealth agreements and trial readouts are landing against a powerful run in Eli Lilly’s market value, with the share price up 19.73% over the past 30 days and a 30.69% year to date share price return. The 5 year total shareholder return of 469.88% shows how long term holders have already been rewarded as sentiment around GLP 1 opportunities builds.
Scan how Eli Lilly’s GLP 1 momentum compares with other potential breakout opportunities across the healthcare space by reviewing the hand picked 36 healthcare AI stocks.
Eli Lilly’s GLP 1 franchise, guidance lift and fresh telehealth reach have already re-rated the shares. After this kind of run, does the risk reward still lean toward buyers, or has the valuation stretch gone too far?
Most Popular Narrative: 4% Undervalued
Measured against the last close at $1,411.95, the narrative fair value of $1,477.03 suggests Eli Lilly trades at a small discount, and the argument behind that gap is worth unpacking. According to AHaron, an investor in the Simply Wall St Community, the market is still catching up to the pipeline story that sits behind those numbers.
The model uses four inputs to arrive at the fair value. Growth rate, which has been adjusted to 18% to reflect reality rather than the overly conservative 12.71% default. A future PE ratio of 30 times earnings in 2031, down from today's 39 times, which accounts for the natural compression in valuation multiples as a company matures and grows larger. A discount rate of 7.5%, slightly above the default of 6.98%, to honestly account for the pipeline risks that still exist. And earnings by 2031 of approximately $48 to $50 billion, above the model's $41.5 billion, because at 18% growth and stable margins, that is where the numbers actually land.
See why 84 investors see Eli Lilly as 4% undervalued.
Result: Fair Value of $1,477.03 (UNDERVALUED)
Still, the bullish Eli Lilly narrative could falter if GLP 1 pricing pressure bites harder than expected or if key late stage trial results disappoint.
Find out about the key risks to this Eli Lilly narrative.
Another View On What Eli Lilly Is Worth
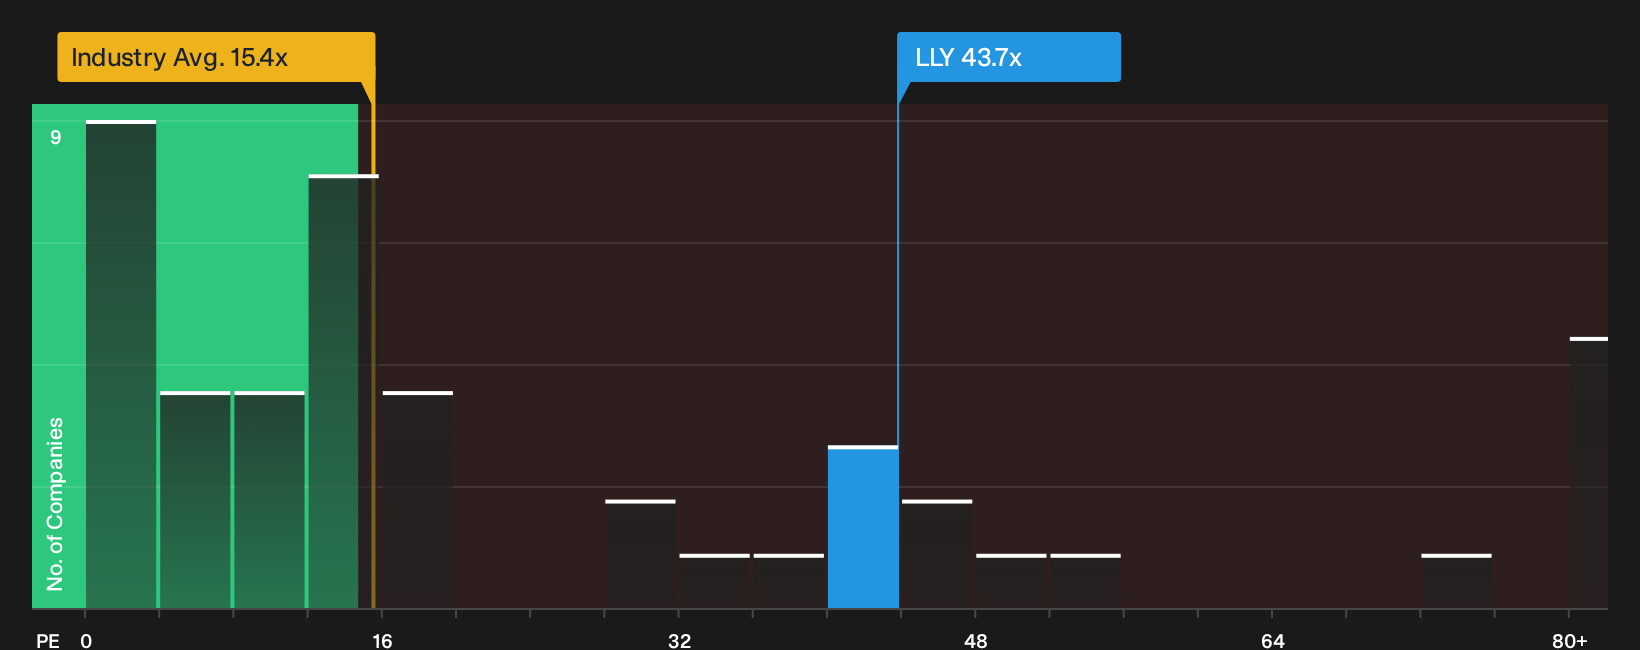
That user narrative leans on earnings and long term growth, but the market is still setting Eli Lilly’s price off a very rich P/E of 45.6x. The broader US pharmaceuticals group trades closer to 15.4x, while the fair ratio for Lilly screens at 56.6x, so investors are paying up already yet could still be short of where the market eventually settles. Is that a margin of safety or a lot of optimism priced into every extra turn of earnings?
For a closer look at how this earnings multiple could evolve as sentiment shifts, check the valuation breakdown built from this approach, then compare it with the cash flow view in the SWS tools: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors are leaning bullish on Eli Lilly after this run, but sentiment cuts both ways when clear risks and rewards sit side by side. If you want to weigh the upside against the pressure points yourself, start with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Eli Lilly?
Do not stop with Eli Lilly. Rotate through fresh opportunities where prices, quality and risk profiles line up in ways that might suit your next move.
- Target potential mispricings by scanning companies that combine quality fundamentals with room for a re rating through the 33 high quality undervalued stocks.
- Build income resilience by focusing on businesses with higher yields that still aim to protect payouts using the 6 dividend fortresses.
- Reduce portfolio stress by concentrating on companies that score well on financial strength using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com