


EN
Microchip Technology Stock In Focus After Strong Quarterly Earnings
- Microchip Technology reported second quarter 2026 sales of US$1.6215b and net income of US$401.4m, with both basic and diluted earnings per share from continuing operations rising to US$0.69 and US$0.68 respectively.
- The sharp improvement in profitability over the past year indicates that Microchip Technology’s operational reset, including cost discipline and product mix, is feeding through to earnings quality rather than only to top line recovery.
- We will now look at how Microchip Technology's stronger quarterly earnings performance could influence the longer term investment narrative around the stock.
Scan how Microchip Technology's earnings reset compares to other chipmakers preparing for the same AI and industrial cycles by reviewing our curated 53 AI infrastructure stocks.
Microchip Technology Investment Narrative Recap
To own Microchip Technology, you need to believe the analyst consensus narrative on Simply Wall St that its exposure to industrial, automotive, data center and aerospace demand can translate into durable orders rather than a short burst of recovery. The strong September quarter, with US$1.6215b in sales and US$401.4m in net income, supports that thesis on execution quality.
The key near term swing factor is whether this earnings reset holds while inventory and foundry constraints still hang over the story. Management’s third quarter guidance, which points to slightly lower net sales and net income, leaves that question open. The biggest risk is that elevated inventory and external capacity bottlenecks keep margins below what more optimistic investors expect.
The recent dividend affirmation of US$0.455 per common share matters because it ties the new profit run rate directly to cash returns. For an investor, that is a live test of how confident Microchip Technology is in its ability to sustain current earnings while still managing a high debt load and underutilized capacity.
That payout decision also interacts with the catalyst around rising data center, aerospace and defense exposure. If those programs keep scaling in line with the analyst consensus narrative on Simply Wall St, the board’s willingness to maintain the dividend could signal comfort that cash generation can fund both shareholder distributions and the edge AI, FPGA and space computing roadmaps already in motion.
Microchip Technology Earnings Assumptions and Valuation Anchors
Microchip Technology's analyst narrative ties the current reset in profitability to a specific long term earnings path that investors can measure against. The story is not just about the recent quarter. It is about whether the business can grow into the earnings profile that underpins the prevailing price targets.
In the Simply Wall St assumptions, analysts are plugging in 17.4% annual revenue growth over the next three years. Earnings today are cited at US$367.2m, with consensus forecasts pointing to US$2.3b of profit and earnings per share of US$4.02 by 2029. That jump in net income is a very large move from the current base and implies a step change in profitability if it plays out as expected.
Profitability targets in the same assumptions section add more context. Analysts are baking in an increase in profit margins from 7.2% today to 28.0% in three years, while also expecting the share count to expand only modestly at 0.47% per year. For readers, the key question is whether Microchip Technology can sustain the mix of higher margin data center, aerospace and edge AI products that would be needed to support that level of margin expansion.
The valuation excerpt then maps those operating forecasts into a single reference year. To line up with the analyst price targets, investors are being asked to accept a 2029 scenario where Microchip Technology generates US$8.3b of revenue and US$2.3b of earnings and trades on a P/E multiple of 35.2x. That would be below the current cited P/E for the US semiconductor sector of 42.6x and well under the 112.2x multiple attached to the stock today in the report.
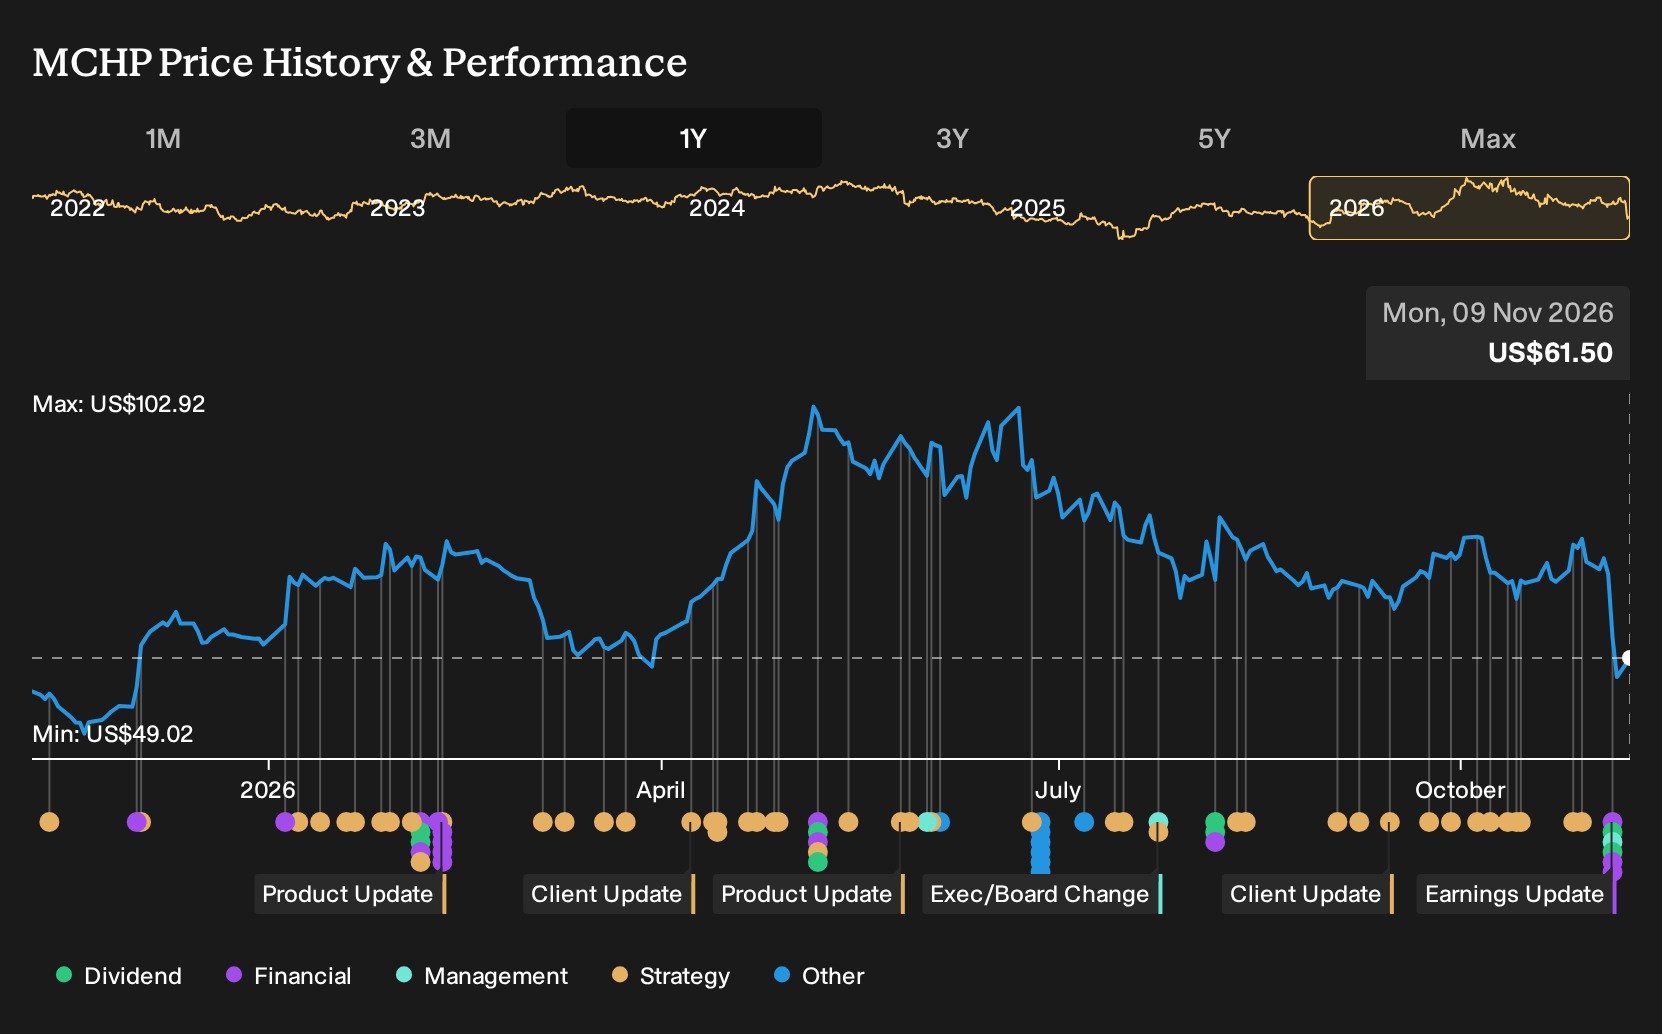
This P/E compression is a core part of the narrative. The thesis in the Simply Wall St report is that earnings growth, rather than multiple expansion, does the heavy lifting in closing the gap between the present share price of US$75.9 and the consensus target of US$105.92, which sits 28.3% higher. Analyst dispersion around that target is wide, with US$135.0 at the top end and US$75.0 at the lower bound, which signals that conviction on the long term path is far from uniform.
Microchip Technology's narrative projects US$8.3b revenue and US$2.3b earnings by 2029. This assumes 17.4% yearly revenue growth and a very large earnings increase from US$367.2m today.
Uncover why Microchip Technology's fair value indicates a 72% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view leans hard into Microchip Technology’s edge AI and space exposure as a potential upside swing factor. Before this earnings release, the most optimistic analysts were already modeling roughly 19.8% yearly revenue growth and about US$3.0b of earnings by 2029. Those projections were built without factoring in the latest quarter, so you may see some forecasts shift as opinions adjust to the new numbers and guidance.
Explore 4 other Microchip Technology fair value estimates, including one that suggests as much as 103% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Microchip Technology research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Microchip Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Microchip Technology's overall financial health at a glance.
Looking For More Investment Ideas Beyond Microchip Technology?
If Microchip Technology has sharpened your view on what quality looks like, it can help to widen the lens and see how other companies stack up on income, value and balance sheet strength using the Simply Wall St Screener.
- For investors who want current income backed by robust fundamentals, review a curated set of 6 dividend fortresses that aim to balance yield with resilience.
- If capital preservation is high on your list, filter for 30 resilient stocks with low risk scores that score well on risk metrics and business stability.
- To hunt for future leaders before they are widely followed, scan a hand picked group of 19 high quality undiscovered gems with solid underlying business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com