


EN
Marathon Petroleum (MPC) Could Be 18% Undervalued After Strong Q3 Earnings And Dividend Hike
Marathon Petroleum (MPC) just posted third quarter 2026 earnings that sharply reshaped its income statement, paired with a 10% dividend lift and fresh capital plans focused on Gulf Coast refining projects.
Marathon Petroleum’s latest move comes after a steep 30 day share price return that fell 14.32%, even though the 90 day share price return is up 15.89% and the year to date share price return has surged 136.09%.
Scan how Marathon Petroleum’s latest earnings and dividend move compare with other downstream energy plays by reviewing our hand picked list of list of solid balance sheet and fundamentals (25 results).
Marathon Petroleum now trades after a sharp rally this year, a recent pullback, a larger dividend, and very strong earnings. Does that mix still leave enough upside in the valuation for new money coming in here?
Most Popular Narrative: 15% Undervalued
On the analyst consensus Narrative on Simply Wall St, Marathon Petroleum screens as undervalued, with a fair value of $458.72 against a last close of $389.88. That gap rests on a detailed set of margin, earnings and capital return assumptions that go well beyond a simple chart of recent share price moves.
The numbers suggest that a fairly valued, bearish view on Marathon Petroleum already reflects strong refining margins, substantial cash returns, and continued MPLX growth, which limits the potential upside for the share price if conditions simply remain where they are.
See why 74 investors see Marathon Petroleum as 15% undervalued.
Result: Fair Value of $458.72 (UNDERVALUED)
Still, the narrative can break if a U.S. diesel export ban hits higher value overseas sales, or if crude stays competitive while product prices soften and squeeze Marathon Petroleum spreads.
Find out about the key risks to this Marathon Petroleum narrative.
Another View: What Multiples Say About Marathon Petroleum
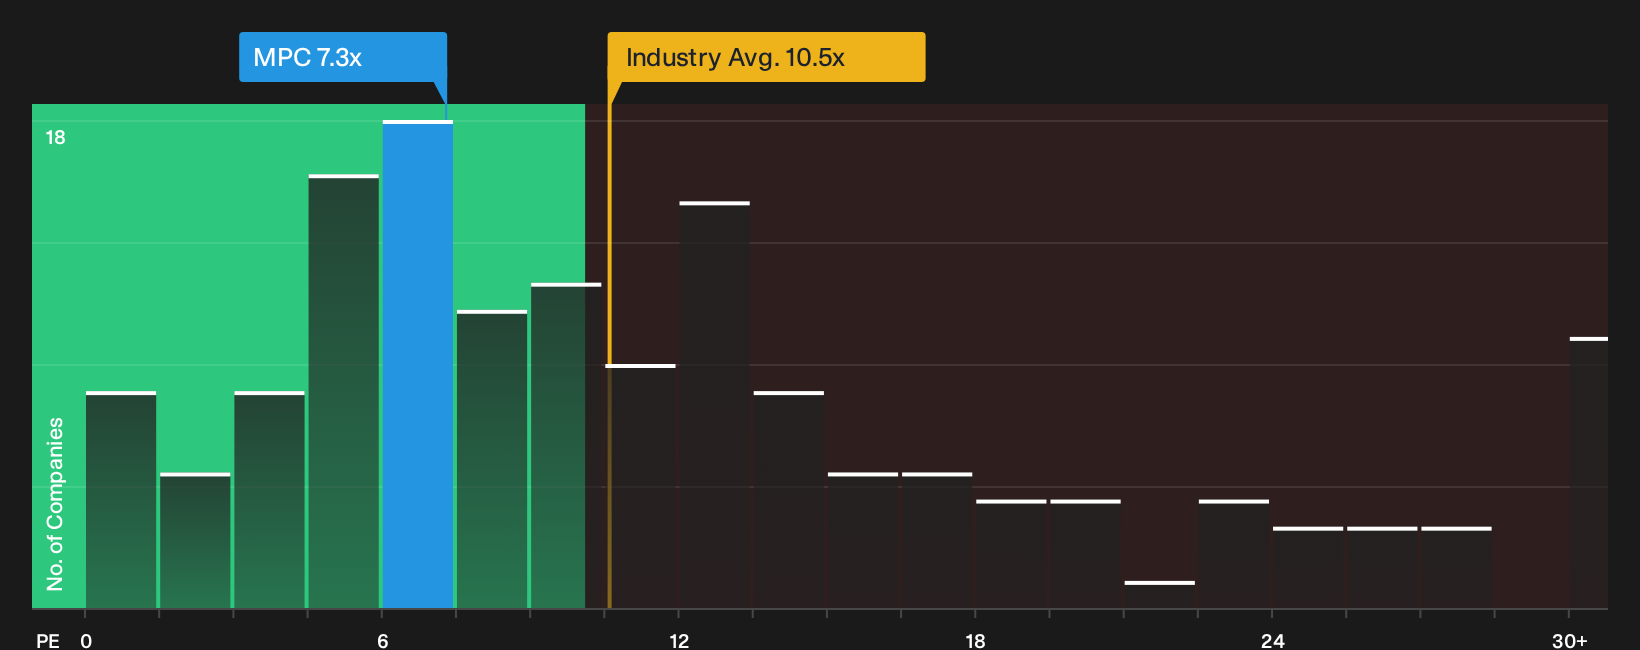
Market pricing tells a different story to the narrative fair value. Marathon Petroleum trades on a P/E of 7.3x, which is cheaper than the US market at 17.4x and below its own fair ratio of 10.7x, yet it is more expensive than peer averages at 5.9x. Does that mix point to a cushion or a value trap?
To see how those P/E gaps stack up against both peers and the fair ratio that the market could eventually lean toward, take a closer look at the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Marathon Petroleum usually split opinion. Move quickly through the data, weigh both sides, and ground your call in the full picture of 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Marathon Petroleum?
Do not stop with Marathon Petroleum. Broaden your watchlist with a few focused stock sets that match different risk and return profiles across the market.
Scan curated ideas built from hard data, then pressure test which ones truly fit your plan before any capital moves.
- Target future upside potential by reviewing companies that screen as attractively priced on quality metrics through the 33 high quality undervalued stocks.
- Prioritise consistency and income by checking out businesses in the 6 dividend fortresses that combine higher yields with robust underlying fundamentals.
- Dial down portfolio stress by focusing on resilient businesses using the 30 resilient stocks with low risk scores before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com