


EN
Will Strong Earnings Guidance Change Nucor (NUE) Stock Narrative
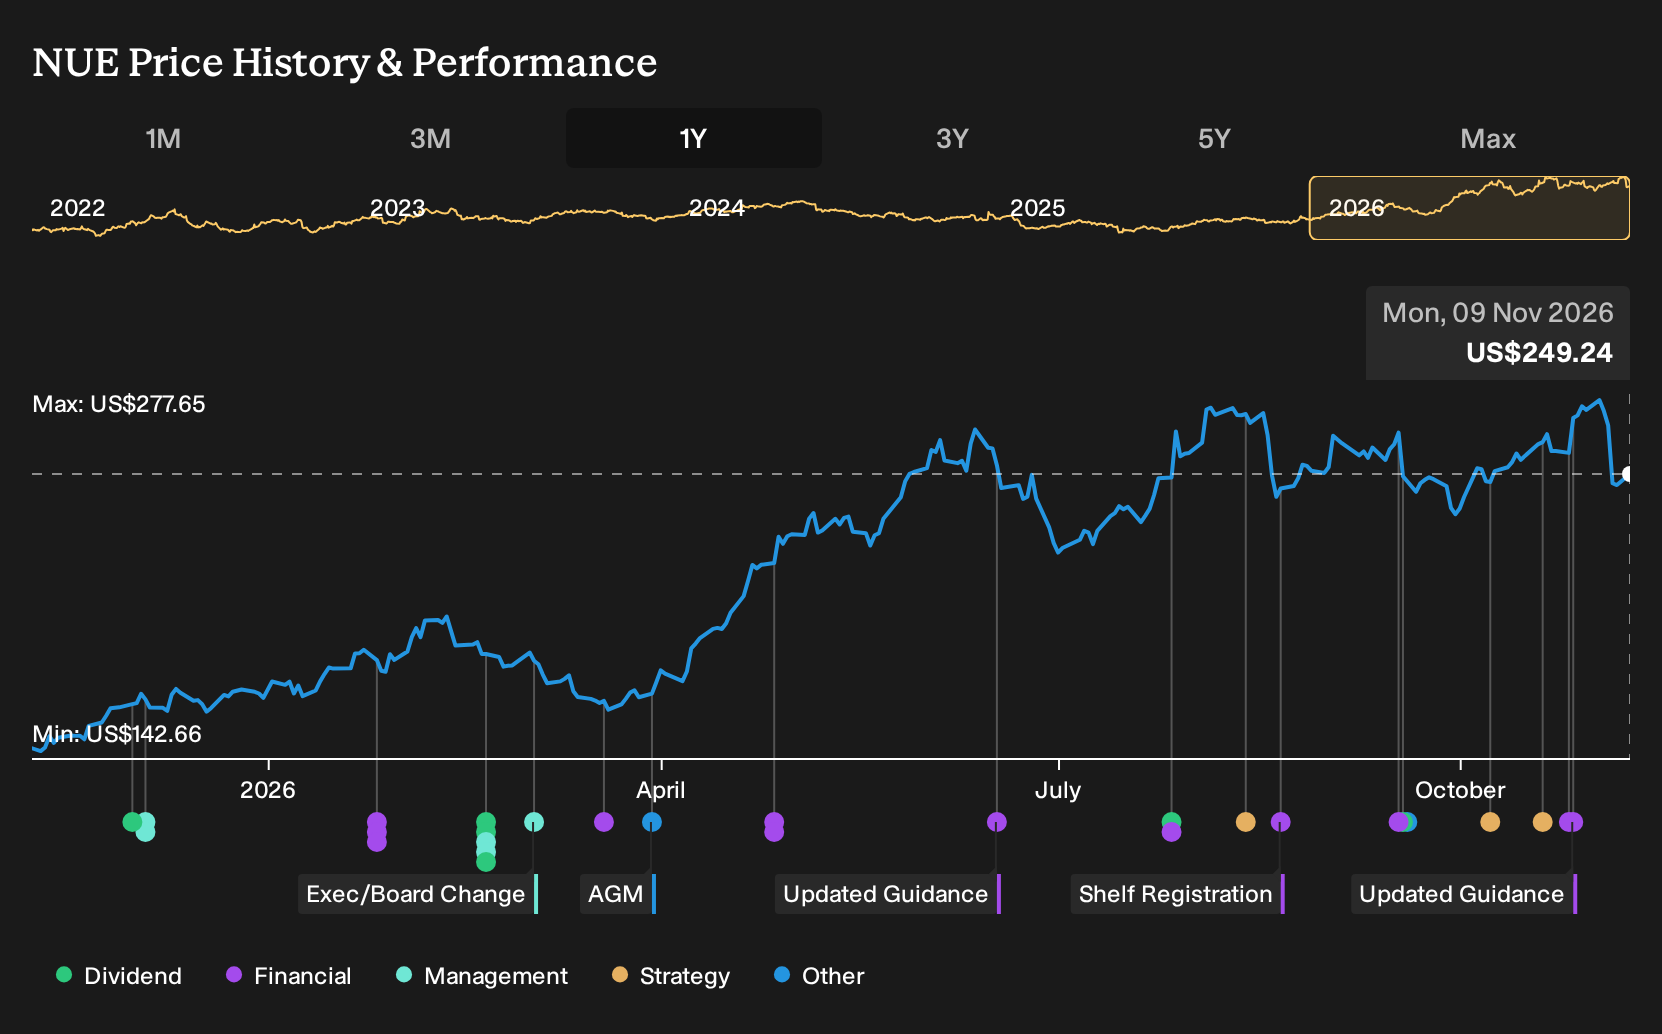
- Nucor reported third quarter 2026 sales of US$11,249 million and net income of US$1,319 million, with fourth quarter earnings guided to be in line with or modestly higher than the prior quarter.
- The combination of higher earnings per share for both the quarter and nine month period and guidance that points to continued earnings stability highlights how Nucor is converting recent capital investment and market conditions into stronger reported profitability.
- The focus now is on how Nucor's stronger recent earnings and steady fourth quarter outlook may reshape the existing investment narrative.
See how Nucor's earnings stability compares with peers by checking stocks screened for list of solid balance sheet and fundamentals (25 results) in similar heavy-industry and capital-intensive sectors.
Nucor Investment Narrative Recap
For you to own Nucor, the big belief is that a capital heavy steel producer can still generate resilient earnings through cycles, supported by tighter U.S. trade policy and a long project backlog. The analyst consensus Narrative on Simply Wall St highlights new mills and downstream assets moving from heavy spending to stronger cash contribution.
The latest guidance that fourth quarter earnings should match or slightly exceed third quarter results points to near term stability rather than a fresh catalyst. The more immediate swing factor remains macro driven steel demand, while key risk sits in execution on projects like the West Virginia sheet mill and in managing raw material volatility.
The most relevant update around this news is the third quarter and nine month result, which showed US$11,249 million of quarterly sales and US$1,319 million of net income, alongside US$31,142 million of sales and US$3,218 million of net income for the nine month period. You can see how the recent earnings step up aligns with the multi year capital program highlighted in the analyst consensus Narrative on Simply Wall St.
That print matters for catalysts because it provides a concrete read on how Nucor is handling higher pre operating and start up costs, raw material swings and demand from nonresidential and infrastructure projects. It also frames the risk that any slowdown in construction activity or commissioning delays at projects like West Virginia could quickly change the tone of future quarters.
Nucor's narrative projects US$40.6b revenue and US$4.5b earnings by 2029. This assumes 1.5% yearly revenue growth and an earnings increase of about US$0.9b from current earnings of US$3.6b.
Uncover why Nucor's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on Nucor's growth projects as a potential upside catalyst. Those bullish analysts were penciling in revenue of about US$45.1b and earnings of US$5.4b by 2029, well above consensus. You can use this more optimistic path as a reference point and compare several potential future narratives after this earnings news settles in.
Explore 2 other Nucor fair value estimates, including one that suggests as much as 21% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nucor research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nucor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nucor's overall financial health at a glance.
Looking For More Ideas Beyond Nucor?
If this Nucor update has sharpened your view on heavy industry, you can widen the opportunity set by scanning other businesses that fit different risk, income, and value profiles using the Simply Wall St Screener.
- For investors hunting for potentially mispriced quality, check out a curated group of 33 high quality undervalued stocks that pair strong fundamentals with more modest valuations.
- If resilience matters most, focus on businesses with healthier finances and steadier profiles through our 30 resilient stocks with low risk scores.
- Income focused investors can zero in on companies prioritizing cash returns to shareholders by reviewing 6 dividend fortresses that combine higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com