


EN
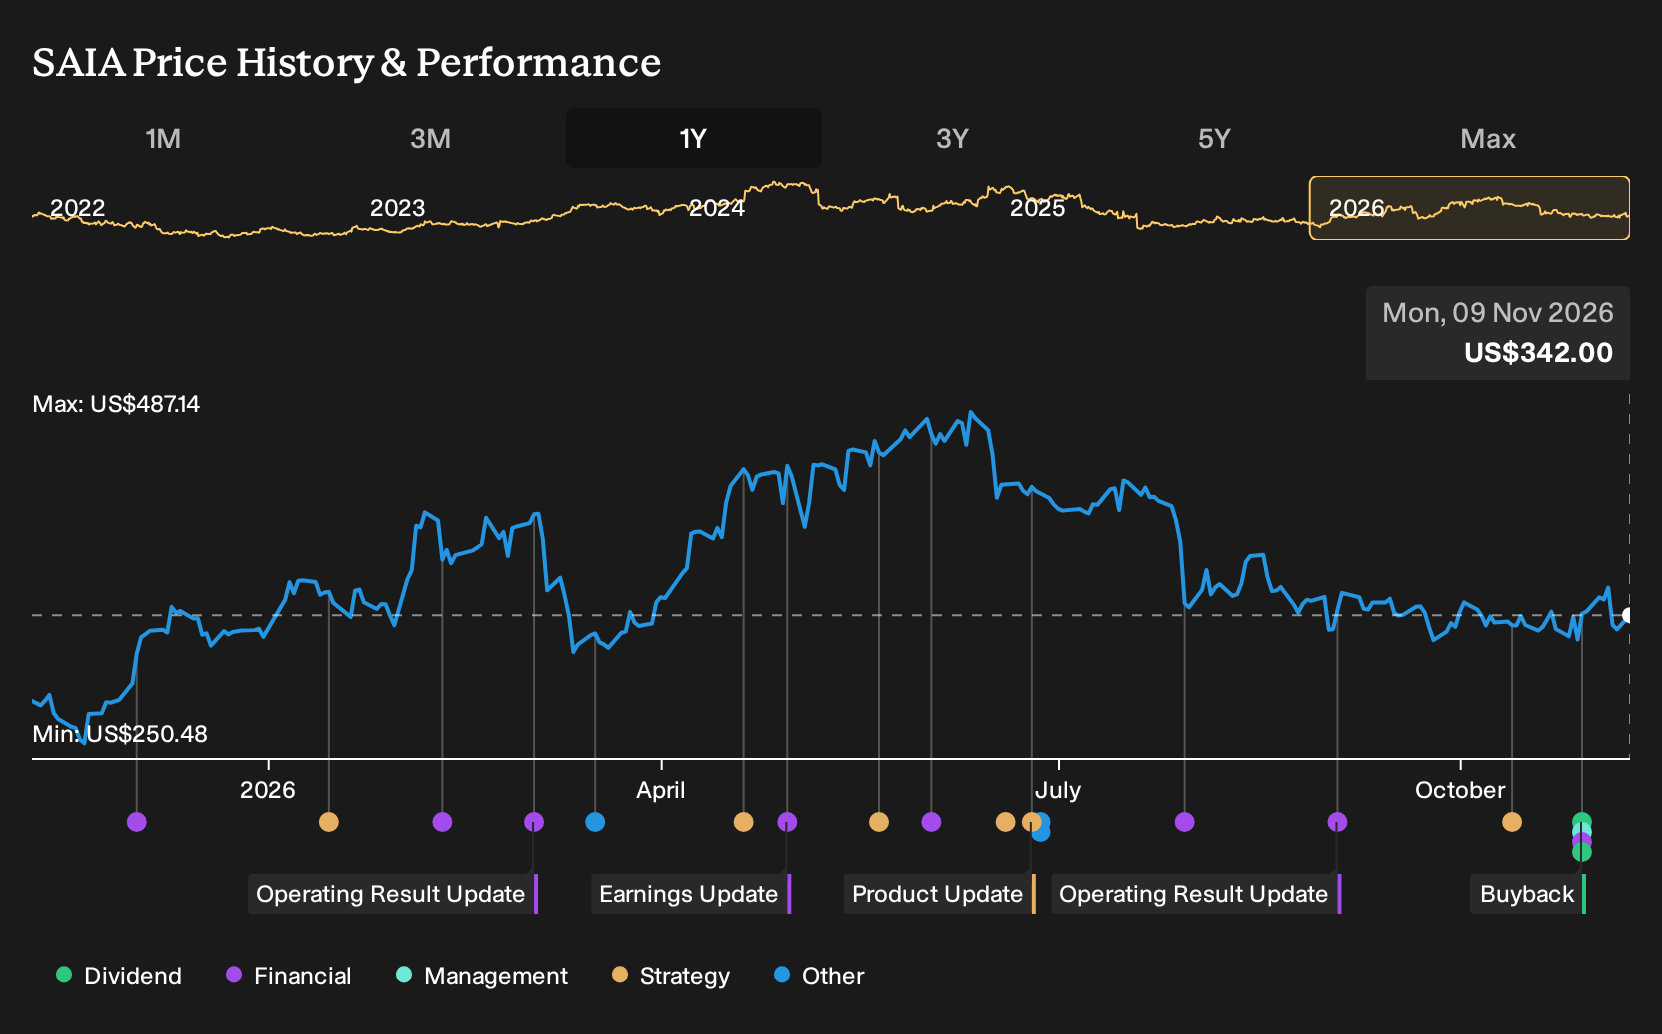
How $250 Million Buyback Will Impact Saia (SAIA) Stock
- Saia, Inc. reported third quarter 2026 sales of US$982.45 million and net income of US$91.45 million, alongside a new US$250 million share repurchase program authorized by the Board with no expiration date.
- The appointment of Todd C. Fowler to Saia’s Board and Audit Committee adds deep transportation, capital markets and autonomous trucking experience that directly aligns with the company’s technology and efficiency focus.
- We will now look at how Saia’s new US$250 million buyback authorization could influence the investment narrative already built around its network.
Saia Investment Narrative Recap
To own Saia, you need to believe its dense less than truckload network and Saia REV technology can keep offsetting higher wages, fuel, claims and insurance. The analyst consensus Narrative on Simply Wall St leans on that thesis. The latest quarter shows revenue of US$982.45 million and net income of US$91.45 million, so the operating engine is still producing cash.
In the short term, the key swing factor is cost pressure relative to pricing and efficiency. Wage, benefit and fuel lines have already been moving higher, and that remains the biggest operational risk. The new share repurchase authorization does not materially change that near term earnings sensitivity; it only adjusts how any excess cash may be deployed.
The new US$250 million buyback plan is the announcement that most directly touches the current investment setup. With Saia trading on a P/E above the internal fair P/E estimate, repurchases rely on management’s conviction in the long term earnings path rather than on a clear discount to intrinsic value. That is important context for you as a shareholder or prospective investor.
In practice, the authorization can amplify catalysts if the network densification and Saia REV tools keep supporting revenue and margin resilience as analysts expect. It can also magnify downside if wage, fuel and insurance costs stay elevated and forecast profit growth does not materialize, since more capital would have been recycled into equity instead of kept on the balance sheet or in the physical network.
Saia's narrative projects US$4.4b revenue and US$510.4 million earnings by 2029. This implies 8.8% yearly revenue growth and an earnings increase of about US$232.4 million from US$278.0 million today.
Discover why Saia's fair value indicates a 23% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on a different risk. They worry that Saia’s heavy reinvestment and higher structural costs could cap future returns on the enlarged network. Their pre-news models pointed to revenue of about US$4.3b and earnings near US$456.3 million by 2029, which is a more cautious path than the consensus. Todd Fowler’s appointment and the US$250 million buyback may shift those expectations over time. You can treat this spread in views as a reminder to compare several narratives before deciding where you stand.
Explore 4 other Saia fair value estimates, including one that suggests as much as 51% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Saia research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Saia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Saia's overall financial health at a glance.
Looking For More Ideas Beyond Saia?
If you want to pressure test your view on Saia against other opportunities, the Simply Wall St Screener can help you line up alternatives with very different risk and return profiles.
- Focus on financial resilience by scanning companies with stronger balance sheets and fundamentals through our list of solid balance sheet and fundamentals (25 results).
- If value is your priority, compare Saia with a 33 high quality undervalued stocks that combine healthy cash flows with robust fundamentals.
- For investors who prefer a calmer ride, you can concentrate on 30 resilient stocks with low risk scores that score well on our risk checks and may offer smoother equity exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com