


EN
How Sweater Quality Backlash At Abercrombie Has Changed Its Investment Story
- Abercrombie & Fitch recently faced criticism after shoppers highlighted that newly launched men’s sweaters use 100% natural fibers, while women’s sweaters, sold at similar prices, rely on acrylic and polyester blends.
- The outcry centers on perceived value and transparency, with many shoppers questioning whether female customers are effectively paying a quiet quality premium for synthetics.
- We will look at how Abercrombie & Fitch's broader investment narrative intersects with this fiber quality controversy in its new sweaters.
Pressure test Abercrombie & Fitch against peers that aim to align price, materials and perceived quality by scanning our curated list of list of solid balance sheet and fundamentals (25 results)
Abercrombie & Fitch Investment Narrative Recap
To own Abercrombie & Fitch, you need to believe the retailer can keep converting its multi brand, omnichannel setup into steady earnings, even as growth expectations are moderate in the analyst consensus Narrative on Simply Wall St. The near term swing factor is execution on merchandising and marketing that keeps customers engaged at current price points.
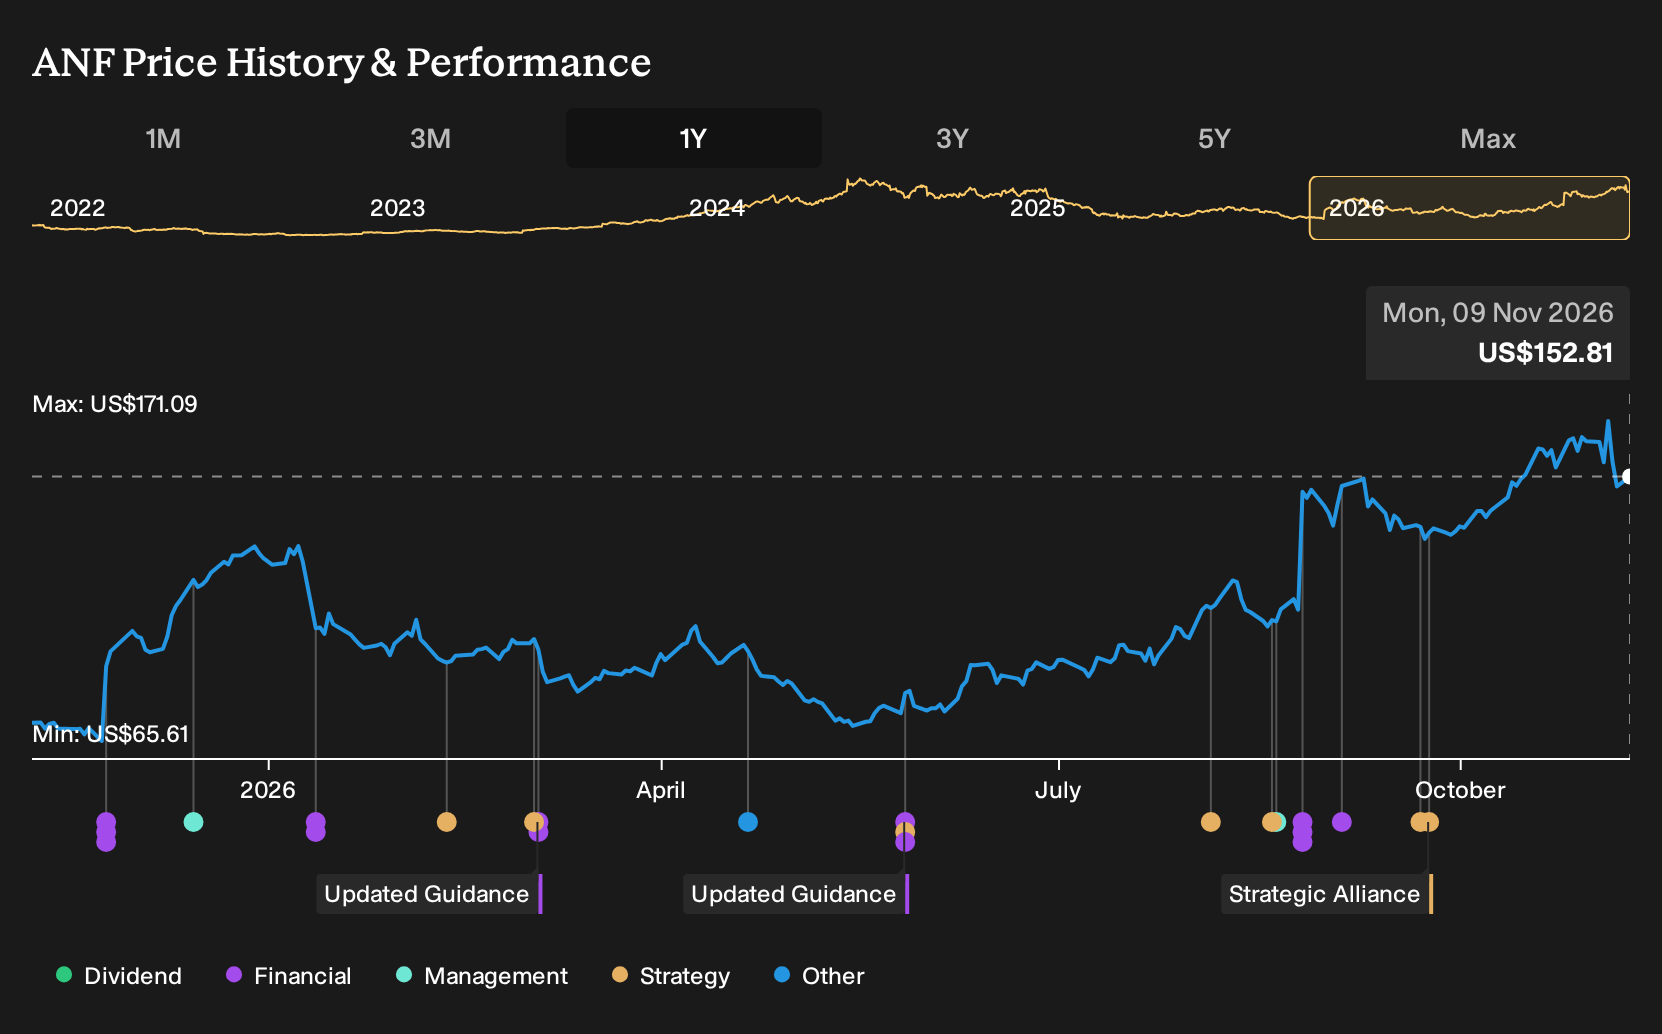
The sweater fiber backlash looks more reputational than financial for now. The bigger watch items remain tariffs, softness in EMEA and APAC and any hit to net margins if IEEPA refunds fade. If the pricing fairness debate starts to affect average unit retail or traffic, that would turn this story into a more material risk.
No single recent announcement directly addresses the sweater criticism. However, the merchandising ERP go live in March 2026 stands out as most relevant. Better inventory chase and shipment visibility give Abercrombie & Fitch more control over what materials and assortments reach which channels, which matters when customers are scrutinising fiber content this closely.
For you as an investor, that ERP rollout links into the same catalysts as before, including tariff mitigation and store remodels. The system should help the business test and react faster if customers reject certain fabric mixes or price points. Execution quality here sits alongside reputational management as a practical near term watch point.
Abercrombie & Fitch's analyst narrative points to revenues of US$6.2b and earnings of US$560.9 million by 2029, which lines up with an assumed 4.8% yearly revenue growth rate and an earnings increase of about US$24.9 million from the current US$536.0 million level.
Uncover why Abercrombie & Fitch's fair value indicates a 7% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the lowest Abercrombie & Fitch analysts lean hard into reputational risk. They worry that controversies like the sweater fiber gap could chip away at trust and make the existing store footprint feel heavier. Before this news, that group was already pencilling in about US$6.1b of revenue and US$576.7 million of earnings by 2029. You do not need to agree with that more cautious script. It is worth treating it as one possible path and asking how this fiber debate might push forecasts closer to, or further from, that lower bar.
Explore 4 other Abercrombie & Fitch fair value estimates, including one that suggests it could be worth just $163.55.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Abercrombie & Fitch research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Abercrombie & Fitch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Abercrombie & Fitch's overall financial health at a glance.
Looking For More Ideas Beyond Abercrombie & Fitch?
Once you have a view on Abercrombie & Fitch, it helps to compare that thesis with other businesses that match your preferred balance of quality, risk and income. The Simply Wall St Screener can surface stocks that line up with the type of portfolio you want to build, rather than whatever happens to be trending today.
- If resilience is your priority, you can filter for companies with stronger balance sheets and steadier fundamentals through our curated list of solid balance sheet and fundamentals (25 results).
- If you are hunting for potential mispricings, you can set your sights on value focused opportunities using the 33 high quality undervalued stocks that our data highlights.
- If reliable cash payouts matter most to you, you can concentrate on income focused opportunities via the high yield 6 dividend fortresses available in the screener.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com