


EN
Is Regis Resources (ASX:RRL) Undervalued On The Duketon South Mine Shutdown?
Regis Resources (ASX:RRL) is in focus after a contract worker died at its Duketon South gold mine, leaving the Rosemont process plant shut and raising fresh questions about operational risk and valuation.
The tragedy hit a stock that has already been through a mixed stretch, with the 30 day share price return down 4.31% and the year to date share price return down 9.70%. Yet Regis Resources still shows a 1 year total shareholder return of 7.37% and a very large 3 year total shareholder return, suggesting long term momentum has been far stronger than the shorter term pullback.
Compare how Regis Resources stacks up on risk and valuation by scanning our hand picked 34 elite gold producer stocks alongside this incident driven pause at Duketon.
Bulls point to Regis Resources’ lower P/E and long run total returns, while bears lean on recent share price weakness and cost and dilution concerns. Which story does the current valuation actually support?
Most Popular Narrative: 11% Undervalued
Against a last close of A$6.89, the analyst consensus Narrative on Simply Wall St pins Regis Resources' fair value at A$7.73, implying a discount that rests on specific cost, cash and project assumptions rather than broad optimism.
The company’s focus on operational efficiency and cost control is now set against structurally higher diesel and all in sustaining costs, so any improvement in productivity or input prices from recent elevated A$3,617/oz levels has scope to lift net margins and earnings.
Regis Resources’ debt free position and cash and bullion balance of about A$1.28–1.3b after record FY26 dividends give it capacity to fund organic projects and selective deals without relying solely on external debt, which can support future production growth and cash flow.
See why 41 investors see Regis Resources as 11% undervalued.
Result: Fair Value of A$7.73 (UNDERVALUED)
Still, higher all in sustaining costs at A$3,617 per ounce and weather disruption at Duketon could pressure Regis Resources’ margins and test that undervaluation story.
Find out about the key risks to this Regis Resources narrative.
Another View: Cash Flow Model Flips The Story
There is a sharp contrast when switching from the analyst fair value of A$7.73 to the Simply Wall St DCF model. On that framework, Regis Resources at A$6.89 trades well above an estimated future cash flow value of A$2.42, which frames the stock as expensive rather than cheap. That gap invites a harder question about which set of assumptions you trust more.
For readers who want to see how that future cash flow estimate has been built line by line, take a few minutes to walk through the SWS DCF workings for Regis Resources via Look into how the SWS DCF model arrives at its fair value.. The visual below shows where the current price sits against that intrinsic value output. It can help you judge whether the cash flow lens or the earnings multiple story feels more realistic for your own thesis.
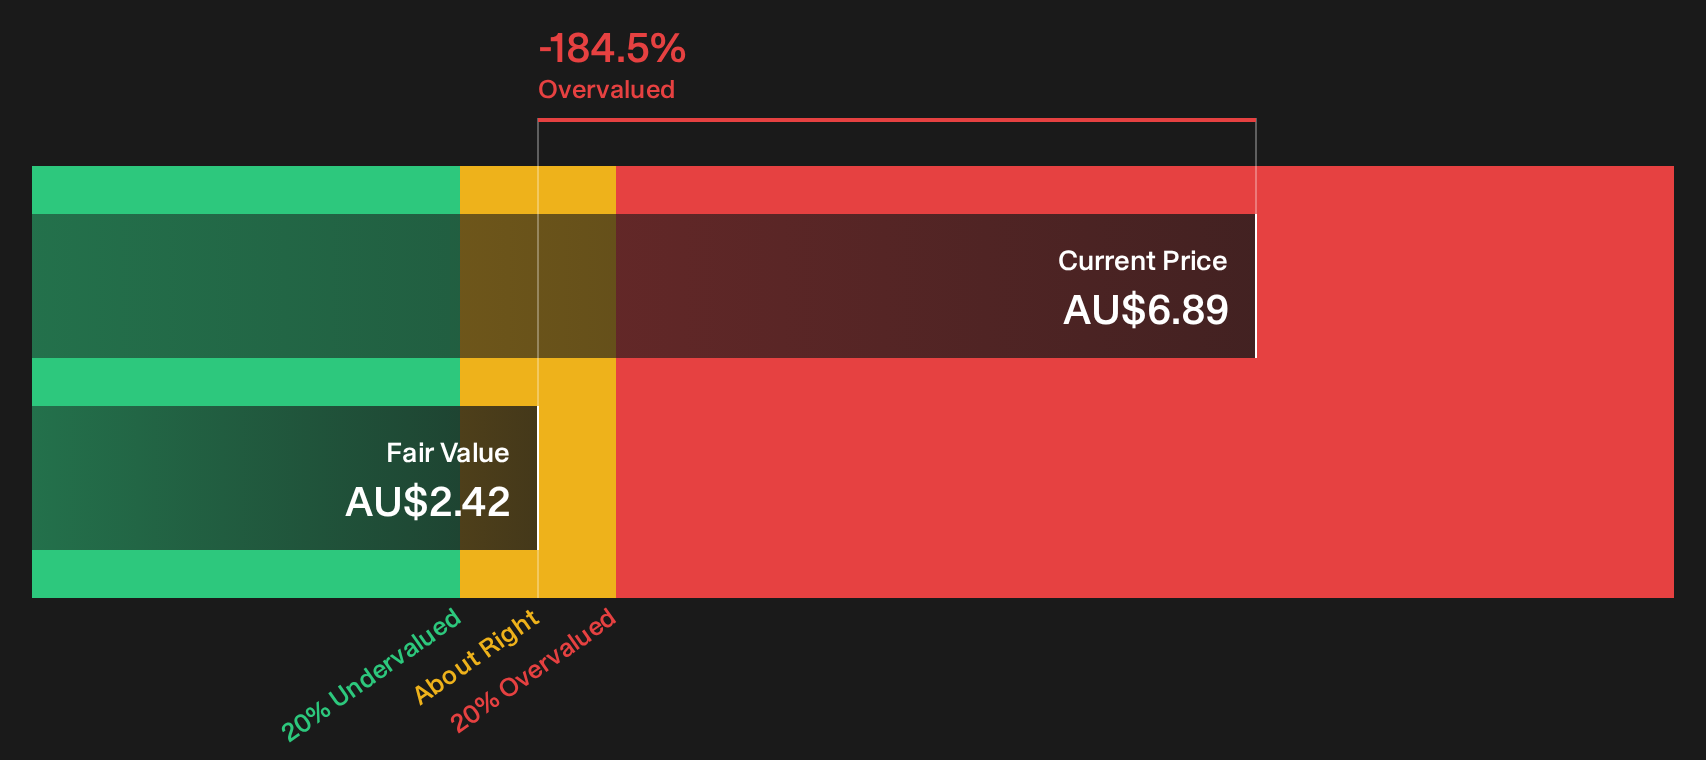
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Regis Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Regis Resources are only useful if they push you to test the numbers yourself and decide where you stand. Take a few minutes to weigh both the risk flags and potential upsides in the 3 key rewards and 2 important warning signs.
Looking for more Regis Resources style investment ideas?
If Regis Resources has you rethinking your watchlist, now is the moment to broaden your research and line up a few fresh contenders.
- Spot potential mispriced opportunities early by scanning companies on the 2 high quality undervalued stocks before the crowd catches on.
- Strengthen your income game by reviewing the 4 dividend fortresses that could complement or contrast Regis Resources' profile.
- Dial down portfolio risk by filtering for resilient businesses using the 6 resilient stocks with low risk scores while others stay overexposed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com