


EN
What Bank of Montreal (TSX:BMO)'s AI Service Rollout Means For Shareholders
- In early November 2026, Bank of Montreal launched AI Agent Assist for its Virtual Connect contact centre. The initiative aims to reduce the 12 to 14 minute average resolution time on more than 500,000 annual Canadian credit card transaction calls and to automate a portion of eligible credit refund processing.
- The AI Agent Assist rollout provides Bank of Montreal with a reusable, human supervised AI toolkit that can be applied across operations. This directly connects its customer service workflows with the bank’s broader plan to translate enterprise AI spending into measurable efficiency and revenue benefits by 2030.
- We will examine how Bank of Montreal’s efficiency focused investment narrative is affected by the AI Agent Assist rollout in servicing.
Bank of Montreal Investment Narrative Recap
To own Bank of Montreal, you need to believe the analyst consensus narrative on Simply Wall St that steady North American loan demand, fee income and AI driven efficiency can support progress toward higher returns without credit losses or funding costs eroding that story. The biggest near term swing factor remains how economic conditions feed into impaired loans and provisions.
The AI Agent Assist rollout in credit card servicing looks incremental rather than thesis changing. It plugs directly into the efficiency and AI value creation catalyst, but it does not obviously move the needle on the key risk that technology and compensation costs could outrun revenue growth and squeeze operating leverage.
The AI Agent Assist launch lines up neatly with the existing catalyst that Bank of Montreal is targeting more than $1b in AI enabled revenue growth, productivity and efficiency gains by 2030. It is one of the first visible tools aimed at that goal, focused on a large, repetitive volume of credit card transaction calls.
For investors watching catalysts, the interesting comparison is between this AI servicing deployment and other recent moves like the BMO eclipse Visa Infinite Privilege upgrades. One leans into better economics and client experience, the other into tech driven cost control and consistency, and execution across both areas will shape how much of the efficiency narrative actually shows up in results.
Bank of Montreal's current narrative links analyst forecasts of CA$43.3b in revenue and CA$11.6b in earnings by 2029 to a projected 6.7% yearly revenue growth rate and an earnings increase of about CA$2.9b from CA$8.7b today.
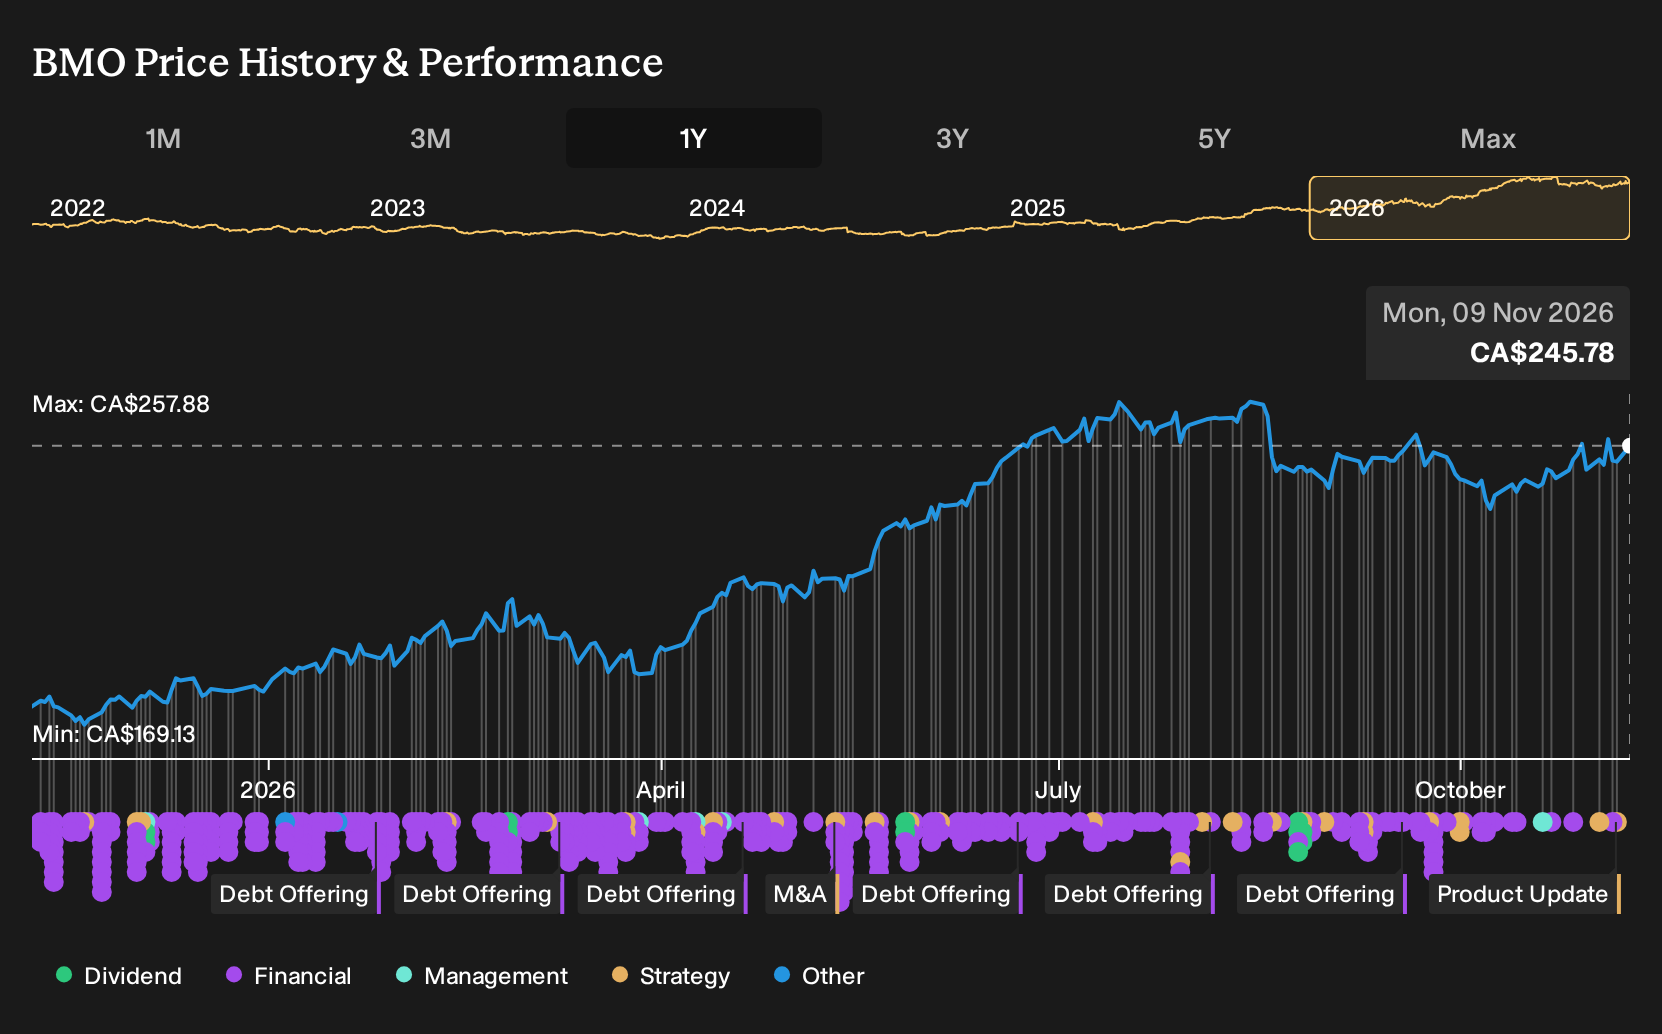
Uncover why Bank of Montreal's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly CA$255 to CA$323, which already shows how far private investors can disagree on Bank of Montreal. When you set that against fresh AI Agent Assist deployment and recent bond issuance, real questions arise about how future efficiency and funding costs could reshape the story. Readers should explore more of these differing views before leaning too heavily on any single narrative.
Explore another Bank of Montreal fair value estimate, including one that suggests potential upside of as much as 31% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank of Montreal research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Montreal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of Montreal's overall financial health at a glance.
Looking for more investment ideas beyond Bank of Montreal?
Once you have a view on Bank of Montreal, it can help to compare that thesis with other listed companies that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener gives you a quick way to line up those alternatives without needing to build complex filters from scratch.
- If you want steadier candidates with an emphasis on resilience, start with a group of 9 resilient stocks with low risk scores that may suit a more capital preservation focused approach.
- For readers hunting for quality at a reasonable price, scan through 6 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
- To broaden the watchlist with companies that have cleaner finances and fewer balance sheet concerns, take a look at a list of solid balance sheet and fundamentals (5 results) that can anchor a longer term portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com