


EN
Kinetik Holdings (KNTK) Shares Moved, So What Is Driving Attention Today?
Kinetik Holdings (KNTK) just posted third quarter results that featured record gas processing volumes, higher revenue and earnings compared with a year earlier, as well as plans for a dividend increase and expanded processing capacity.
Despite the strong third quarter update, Kinetik Holdings’ recent share price action has been mixed. The stock is up 3.2% on the day to US$50.33, but down 6% over the past week and 5.9% over the past month. Even with that cooling in near term momentum, the year to date share price return of 38% and 1 year total shareholder return of 58.6% indicate that investors who have stayed through recent swings have still seen material gains that reflect both income and price moves.
Spot opportunities around Kinetik Holdings by comparing its recent run to a hand-picked 33 high quality undervalued stocks. This comparison may offer a different balance of price, quality, and momentum.The recent pullback leaves Kinetik Holdings trading at a discount to both intrinsic estimates and analyst targets. Is that a genuine mispricing after a strong quarter, or a fair reflection of the market’s caution around the story?
Most Popular Narrative: 12% Undervalued
Kinetik Holdings is trading at $50.33 against a fair value from the analyst consensus Narrative on Simply Wall St of $57.31, which points to a material discount based on those cash flow and earnings assumptions.
Kinetik Holdings is progressing a large scale buildout in the Delaware Basin, with Kings Landing II sanctioned as a US$260 million, 300 MMcf/d gas processing plant expected online by mid 2028 and procurement already underway for another cryogenic plant. Together, these projects point to higher future throughput capacity that can support revenue and EBITDA growth as producer development fills this system.
See why 10 investors see Kinetik Holdings as 12% undervalued.
Based on that framework, the Narrative applies a 7.24% discount rate to analyst forecasts and arrives at a fair value of $57.31 per share, around 12% above the latest close and modestly higher than the current analyst target of $59.19.
The thesis leans on higher throughputs, a larger fee based contract mix, and planned Gulf Coast connections, while acknowledging capital intensity, Waha pricing risk and accounting volatility as key pressure points that could challenge those assumptions.
Result: Fair Value of $57.31 (UNDERVALUED)
Still, Kinetik Holdings faces real pressure points if high capital spending squeezes cash flow or if prolonged Waha price dislocations continue to weaken margins.
Find out about the key risks to this Kinetik Holdings narrative.
Another View: Kinetik Holdings On Earnings Multiples
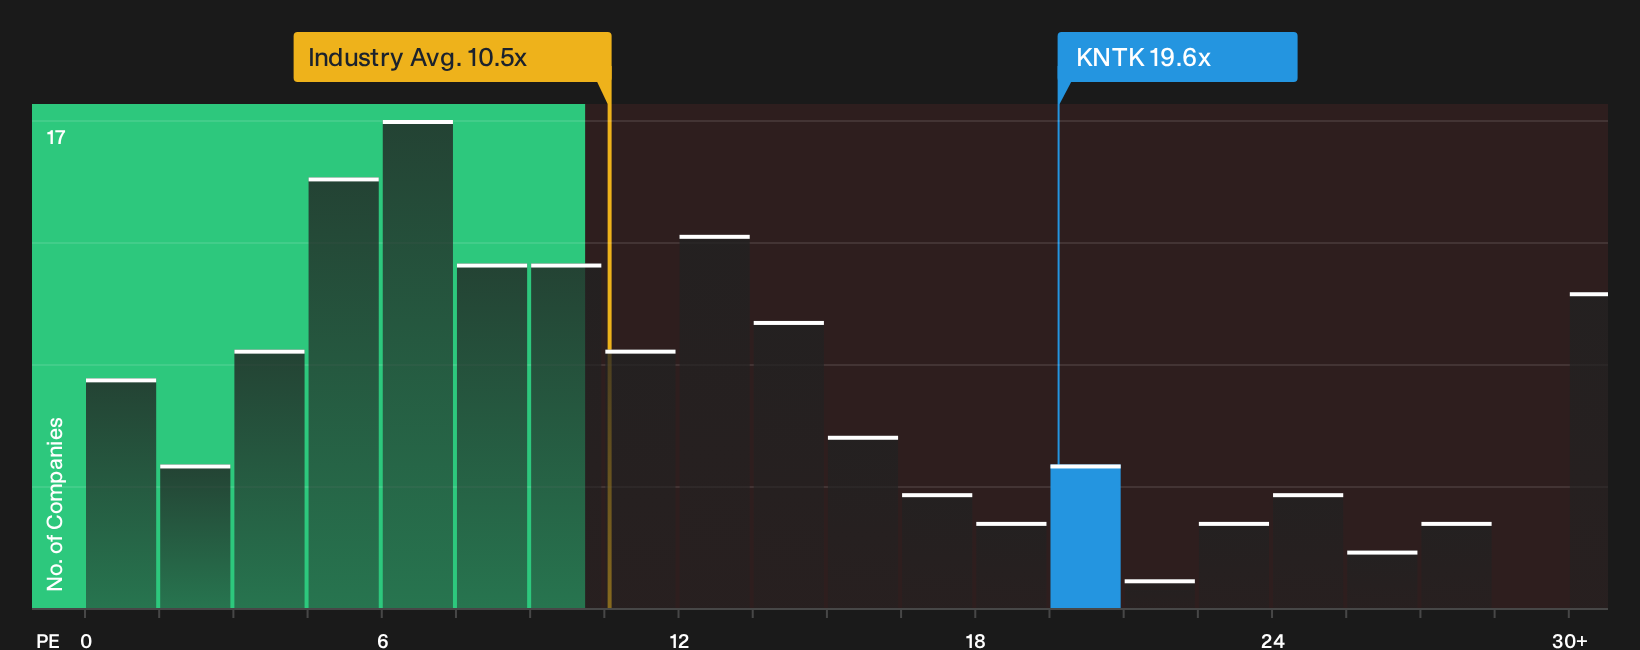
The cash flow model suggests Kinetik Holdings looks cheap, but the P/E picture is less generous. The stock trades on 20.3x earnings compared with a fair ratio of 17x, the US Oil and Gas sector on 10.5x, and peers at 14x. Is that premium justified if growth and balance sheet risk stay as they are?
To unpack what that valuation gap could mean for upside or downside risk, look at how the earnings multiple stacks up in our detailed breakdown: See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual on how that premium compares with other operators, review the latest relative P/E snapshot:
Next Steps
Mixed views run through this Kinetik Holdings story, so move quickly, look through the full data set, and decide where you stand using these 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kinetik Holdings?
If Kinetik Holdings has your attention, do not stop here. Use this momentum to broaden your watchlist with fresh opportunities using the Simply Wall St screener.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that can help you stress test your portfolio for tougher conditions.
- Hunt for mispriced quality and compare Kinetik Holdings with a 19 high quality undiscovered gems that may not yet be crowded trade ideas.
- Prioritise capital preservation and smoother ride potential by filtering through a 30 resilient stocks with low risk scores that focuses on businesses with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com