


EN
Great West Lifeco (TSX:GWO) Could Be 3% Undervalued As Third Quarter Earnings Land
Great-West Lifeco (TSX:GWO) just paired a fresh set of third quarter earnings with new dividend decisions on both common and preferred shares, giving investors updated income figures to weigh against the stock’s recent performance.
Those fresh dividend decisions and third quarter figures land after a powerful run in Great-West Lifeco’s share price, with the stock at CA$91.93 and a year to date share price return of 37.0%, while long term investors have seen a 1 year total shareholder return of 58.75% and a 5 year total shareholder return of 205.70%. This performance suggests momentum has been strong as earnings and income policies shape how investors are reassessing both growth potential and risk.
Scan beyond Great-West Lifeco and line up other income focused insurers showing strong momentum with our curated 3 dividend fortresses
After that kind of price run, steady earnings and fresh dividends from Great-West Lifeco sharpen the real question: Does the current tag still leave enough upside to justify the risk, or has most of the easy reward already been priced in?
Most Popular Narrative: 3% Undervalued
On the analyst consensus Narrative on Simply Wall St, Great-West Lifeco screens as modestly undervalued, with a fair value of roughly CA$95.23 against the latest close at CA$91.93. This puts more focus on how durable the current earnings mix really is under a 6.44% discount rate.
The main thing that has to go right is continued execution on scaling Empower and Capital and Risk Solutions while managing pockets of pressure such as Canadian group long-term disability claims and competition for spread income.
The view that Great-West Lifeco is fairly valued and bullish implies the current share price already reflects strong ROE around the high teens, high capital generation and a growing mix of capital-light earnings.
See why 47 investors see Great-West Lifeco as 3% undervalued.
Result: Fair Value of CA$95.23 (UNDERVALUED)
Still, that story can crack if fee pressure in U.S. retirement plans bites harder than expected, or if Canadian group disability claims keep straining profitability.
Find out about the key risks to this Great-West Lifeco narrative.
Another View: Great-West Lifeco Looks Pricy On Earnings
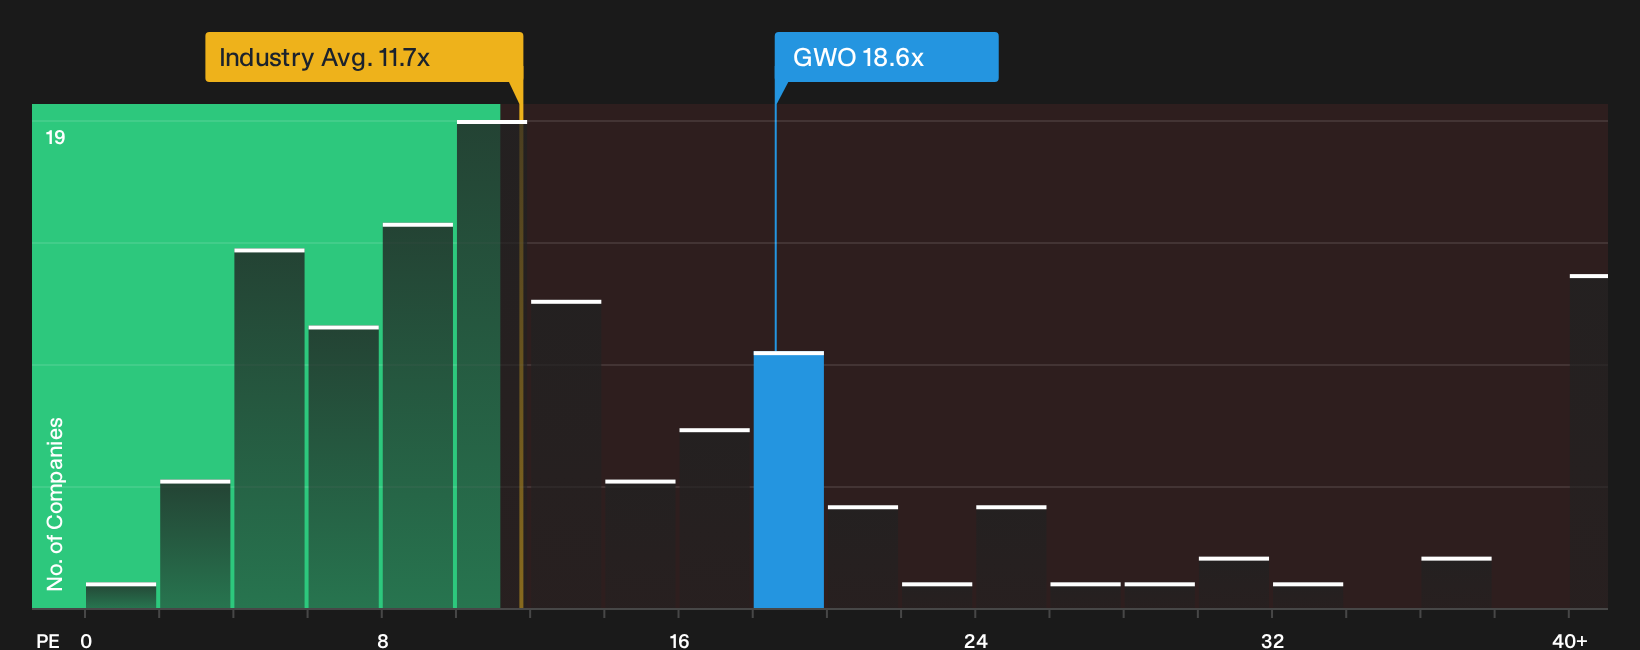
On cash flows Great-West Lifeco screens as cheap, yet the earnings multiple tells a different story. At a P/E of 18.6x versus a fair ratio of 14.6x, and well above the North American insurance group at 11.7x, the share price builds in a lot of optimism. How comfortable are you paying that kind of premium?
Before leaning too heavily on that single metric, it can help to see how the numbers stack up across a fuller earnings breakdown, valuation checks and peer comparisons, then weigh how much margin for error you really have at today’s price. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Great-West Lifeco is mixed enough that no single story feels complete on its own. This is exactly why you should pressure test the numbers, stress the assumptions and then weigh up the balance of 3 key rewards and 2 important warning signs.
Looking for more Great-West Lifeco sized ideas?
If Great-West Lifeco has sharpened your focus on quality, do not stop here. The right watchlist now could shape your portfolio outcomes for years.
- Target value with conviction by scanning a 6 high quality undervalued stocks that pairs strong fundamentals with pricing that still looks reasonable.
- Reinforce your capital with a list of solid balance sheet and fundamentals (5 results) so you are backing businesses that carry less financial strain.
- Spot tomorrow's potential early by tracking a 7 high quality undiscovered gems that highlights strong companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com