


EN
Should Q3 2026 Earnings Require Action From SpareBank 1 Sør Norge (OB:SB1NO) Investors?
- SpareBank 1 Sør-Norge reported Q3 2026 net interest income of NOK 2,236 million and net income of NOK 1,757 million, with nine-month net income at NOK 5,034 million and basic EPS from continuing operations of NOK 12.95.
- The slight year-on-year shift in quarterly net interest income, alongside higher net profit, highlights margin management and cost control as key focus areas for SpareBank 1 Sør-Norge.
- This article examines how SpareBank 1 Sør-Norge's investment narrative is influenced by higher net income despite softer quarterly net interest income.
Compare SpareBank 1 Sør-Norge's earnings story with a curated set of banks and financials that show resilient profits and balance sheets in the list of solid balance sheet and fundamentals (194 results).
SpareBank 1 Sør-Norge Investment Narrative Recap
To own SpareBank 1 Sør-Norge, you need to believe in steady banking economics, disciplined costs and a manageable competitive hit to lending margins. The analyst consensus Narrative on Simply Wall St leans heavily on merger synergies and a tight cost to income ambition. The latest quarter fits that story, with slightly softer net interest income alongside higher profit, pointing to efficiency and mix rather than volume as the near term engine.
The key short term catalyst still sits in delivering the raised synergy target and keeping the cost ratio trending lower. Competitive pressure on pricing and high liquidity remain the biggest operational risks. This Q3 print does not radically change either side of that equation, so the story is more confirmation than reset.
The fresh data point that really matters here is the Q3 and nine month earnings release itself. Net interest income of NOK 2,236 million for the quarter and NOK 6,562 million year to date, alongside NOK 5,034 million in nine month net income and basic EPS of NOK 12.95 from continuing operations, gives you a clean read on current profitability as of late October 2026.
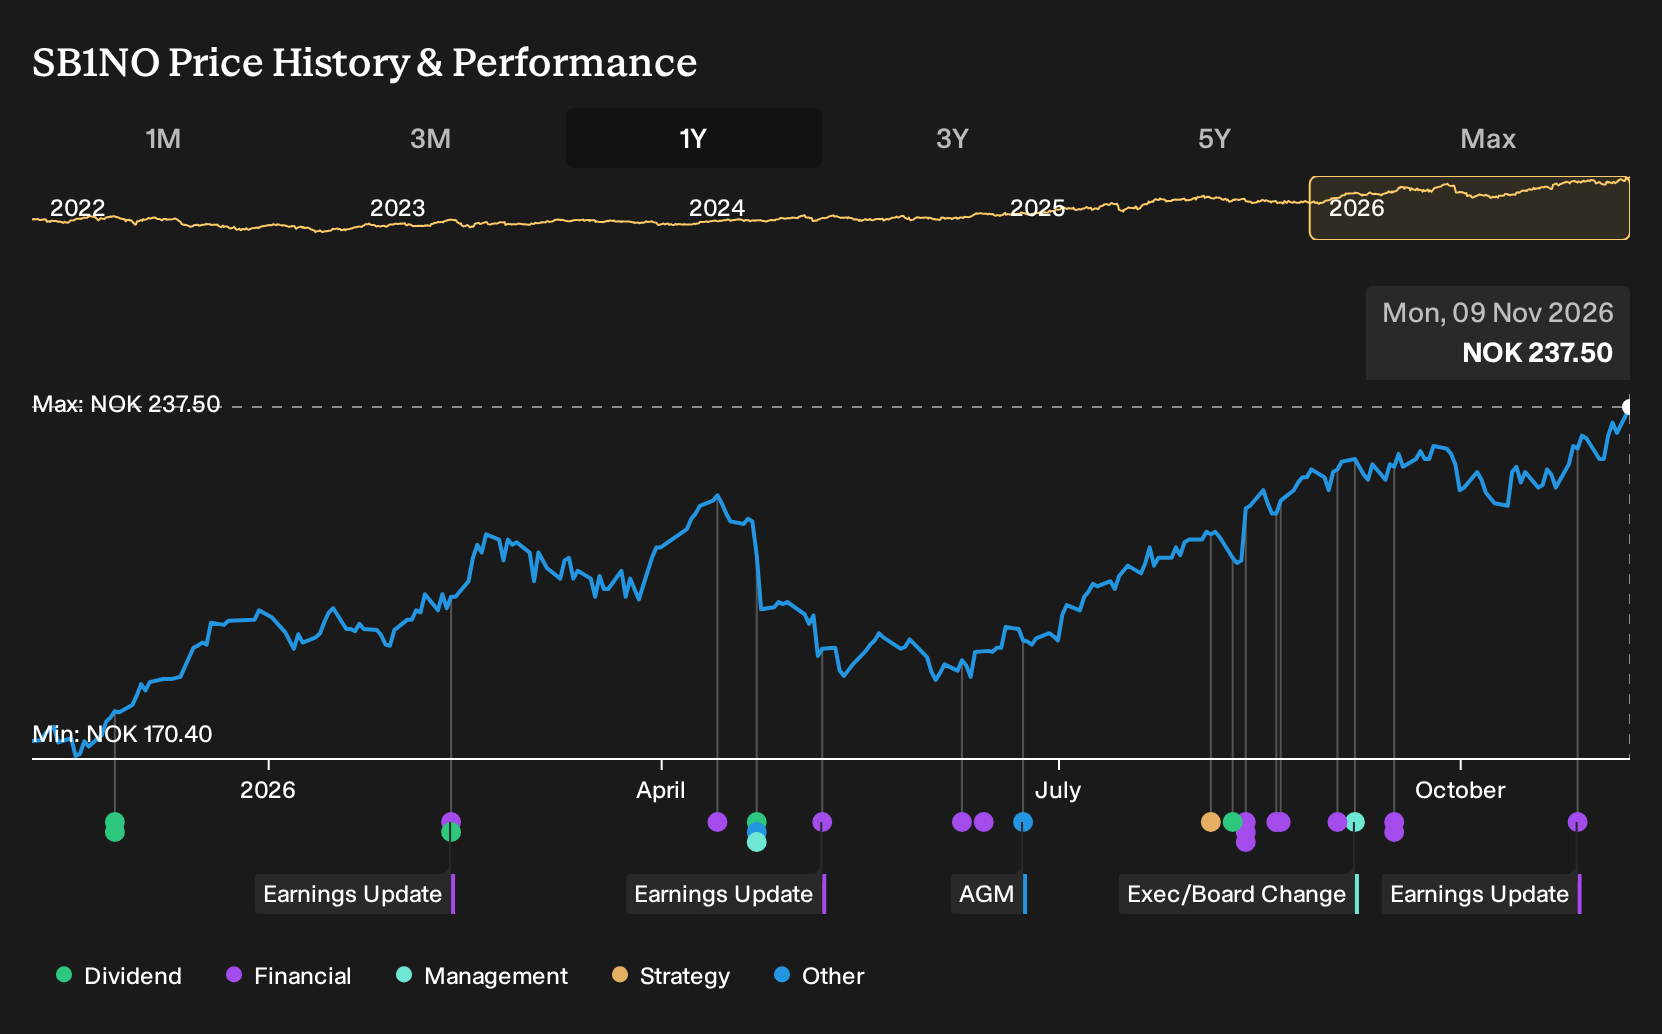
Those figures plug straight into the existing catalysts around efficiency, capital usage and competition. They sit against risks such as a relatively low allowance for bad loans and a funding mix where around half of liabilities come from higher risk sources. For you as a shareholder, the job now is comparing this earnings quality and risk profile with what you think is already reflected in the current P/E and recent share price performance.
SpareBank 1 Sør-Norge's current earnings are NOK 6.3b and analysts are projecting NOK 15.0b in revenue and NOK 7.7b in earnings by 2029. This projection implies 3.7% yearly revenue growth and an earnings increase of about NOK 1.4b from today.
Uncover why SpareBank 1 Sør-Norge's fair value indicates a 7% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly NOK 221 to about NOK 336 per share, so you are seeing everything from clear discount calls to much richer targets. Set those views against risks like intense lending competition and very high liquidity, then decide which SpareBank 1 Sør-Norge scenario you find most convincing.
Explore 2 other SpareBank 1 Sør-Norge fair value estimates, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your SpareBank 1 Sør-Norge research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SpareBank 1 Sør-Norge. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SpareBank 1 Sør-Norge's overall financial health at a glance.
Looking for more investment ideas beyond SpareBank 1 Sør-Norge?
If the SpareBank 1 Sør-Norge story has sharpened your thinking on risk, quality and valuation, broaden that lens by scanning a wider field of companies that fit different styles of opportunity.
- If you want potential upside with tighter balance sheet discipline, scan a curated set of financially healthy candidates through the 572 high quality undiscovered gems.
- If capital preservation and steadier profiles matter more to you right now, filter for companies with stronger resilience using the 202 resilient stocks with low risk scores.
- If income is your priority, build a shortlist of cash return candidates by screening for high yielding payers in the 222 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com