


EN
How Investors May Respond To Antero Resources Stock Strong Q3 Earnings
- Antero Resources released third quarter 2026 results, reporting US$1.56b in revenue, US$367.14m in net income and 390 Bcfe of combined production, with daily volumes of 4,234 MMcfe/d.
- The earnings report showed higher nine month revenue of US$5.07b and net income of US$1.18b, alongside lower impairment charges on property and equipment compared with the prior year period.
- This article examines how Antero Resources’ stronger third quarter profitability and production profile relate to the existing investment narrative.
Scan how Antero Resources’ latest production and regulatory moves compare with other gas producers that screen well on balance sheets and fundamentals through our curated list of solid balance sheet and fundamentals (25 results) list.
Antero Resources Investment Narrative Recap
Antero Resources is still an export linked Marcellus gas producer, so the big belief is that firm transport access and liquids rich volumes can support cash generation even when regional prices are weak. The immediate swing factor is execution on production and cost control while managing curtailments tied to low local pricing. The fresh flurry of FERC interventions around pipeline tariffs and service agreements looks more like routine blocking and tackling rather than a change to that thesis.
The biggest short term catalyst remains how efficiently Antero Resources converts its firm transport and gathering footprint into sustained volumes and margins as export demand shapes contract terms. The key near term risk is that regulatory or tariff outcomes increase transport costs or restrict flow options just as external analysis in the analyst consensus Narrative on Simply Wall St already highlights past pressure on margins.
The recent motions to intervene across multiple FERC dockets, including new and revised negotiated rate service agreements on Equitrans, ANR, Columbia, Midwestern, Rockies Express and Natural Gas Pipeline Company of America, sit directly on top of that thesis. This activity speaks directly to how Antero Resources manages access to pipes that move Marcellus volumes toward Gulf Coast and Midwest end markets.
Those filings intersect with catalysts around firm transport optimization and cost reduction. The LNG and export linked story only works operationally if these long term agreements keep capacity available on acceptable terms and preserve route flexibility as tariffs evolve. The risk for shareholders is that less favorable outcomes on these dockets could limit how much of the cash cost reduction and export pricing uplift the business can actually realize.
Antero Resources' current narrative assumes revenues reach US$7.1b and earnings come in at US$1.4b by 2029. This outlook is built on analysts' expectations for roughly 7.0% yearly revenue growth and an earnings increase of about US$300m from US$1.1b today.
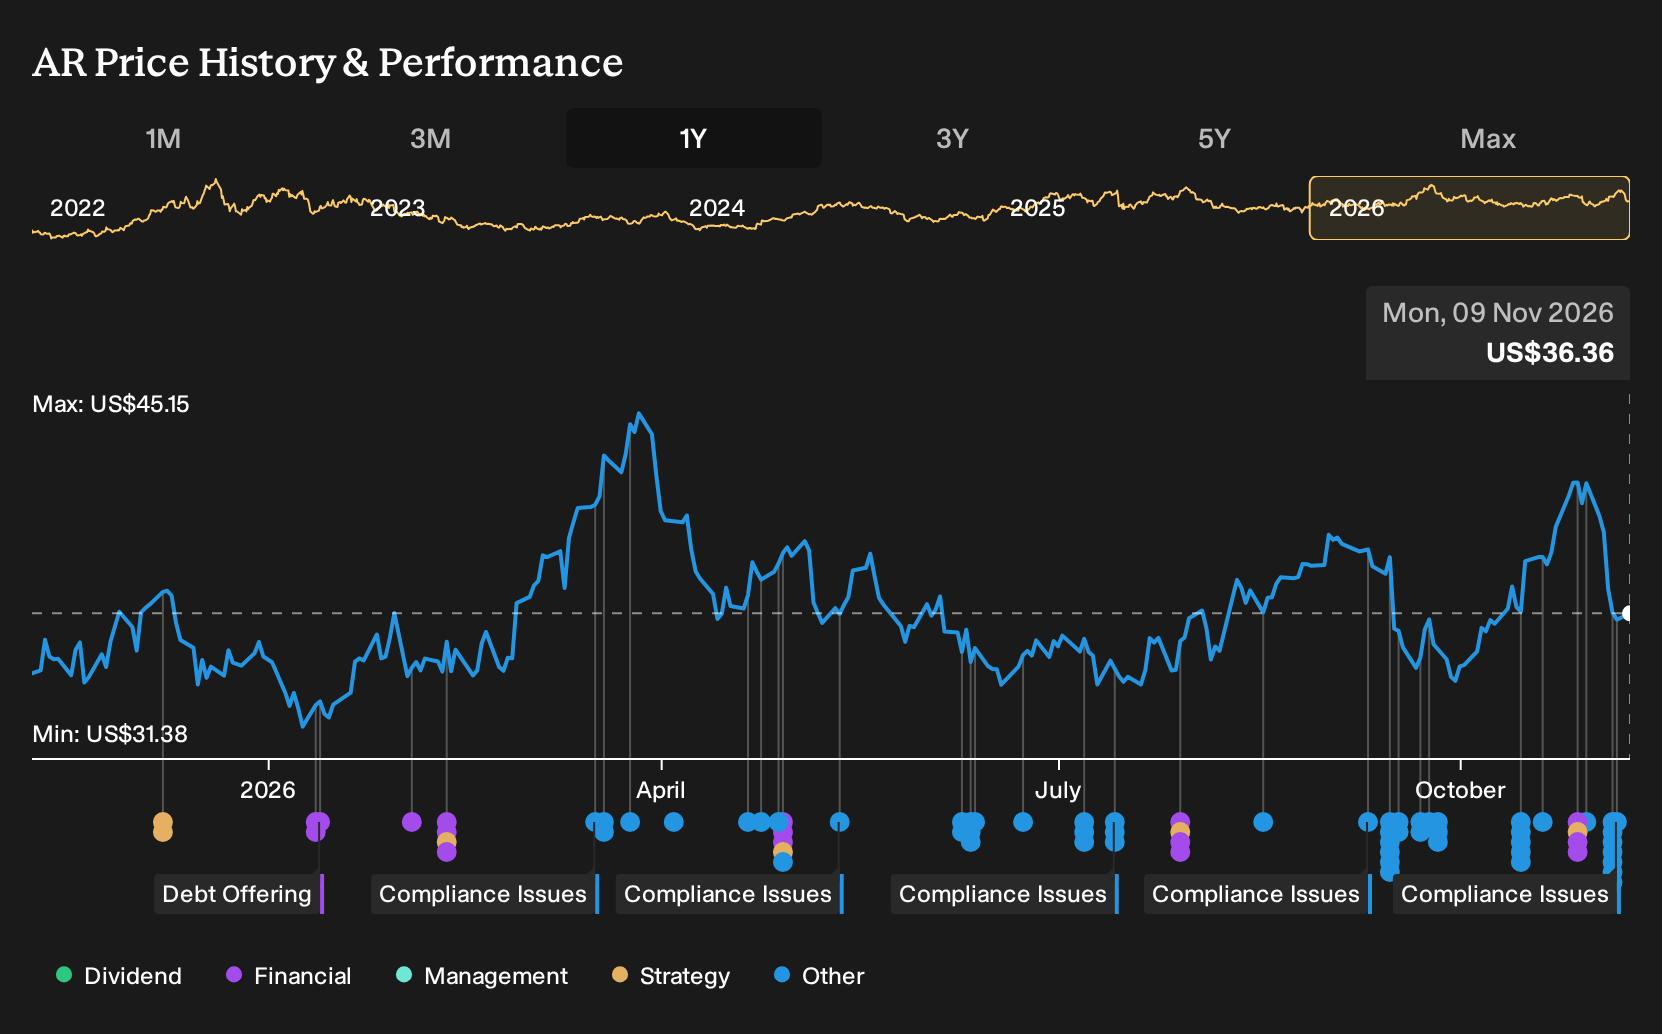
Uncover why Antero Resources' fair value points to a 38% potential upside to its current price that could close sooner than the market expects.
Exploring Other Perspectives
One alternate view focuses less on LNG demand and more on transport risk. In that lens, Antero Resources’ flurry of FERC interventions might flag concern that future pipeline tariffs could squeeze profitability. The most cautious analysts already modeled only US$7.1b of revenue and about US$1.4b of earnings by 2029, and those forecasts may change as this regulatory story evolves.
Explore 3 other Antero Resources fair value estimates, including one that suggests it could be worth just $50.19!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Antero Resources research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Antero Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Antero Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Antero Resources?
If the Antero Resources story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you zero in on other companies that match your preferred balance of quality, risk and income.
- For investors who care most about financial resilience, you can filter for companies with stronger balance sheets and consistent fundamentals using our curated list of solid balance sheet and fundamentals (25 results).
- If you are hunting for potential mispricings, you can scan a focused set of opportunities that screen as high quality yet potentially misvalued through the 33 high quality undervalued stocks.
- Income focused readers who put steady cash flows first can review a hand picked group of companies offering higher yields and robust payout profiles via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com