


EN
Will Raised Earnings Guidance Change Toray Industries' (TSE:3402) Narrative
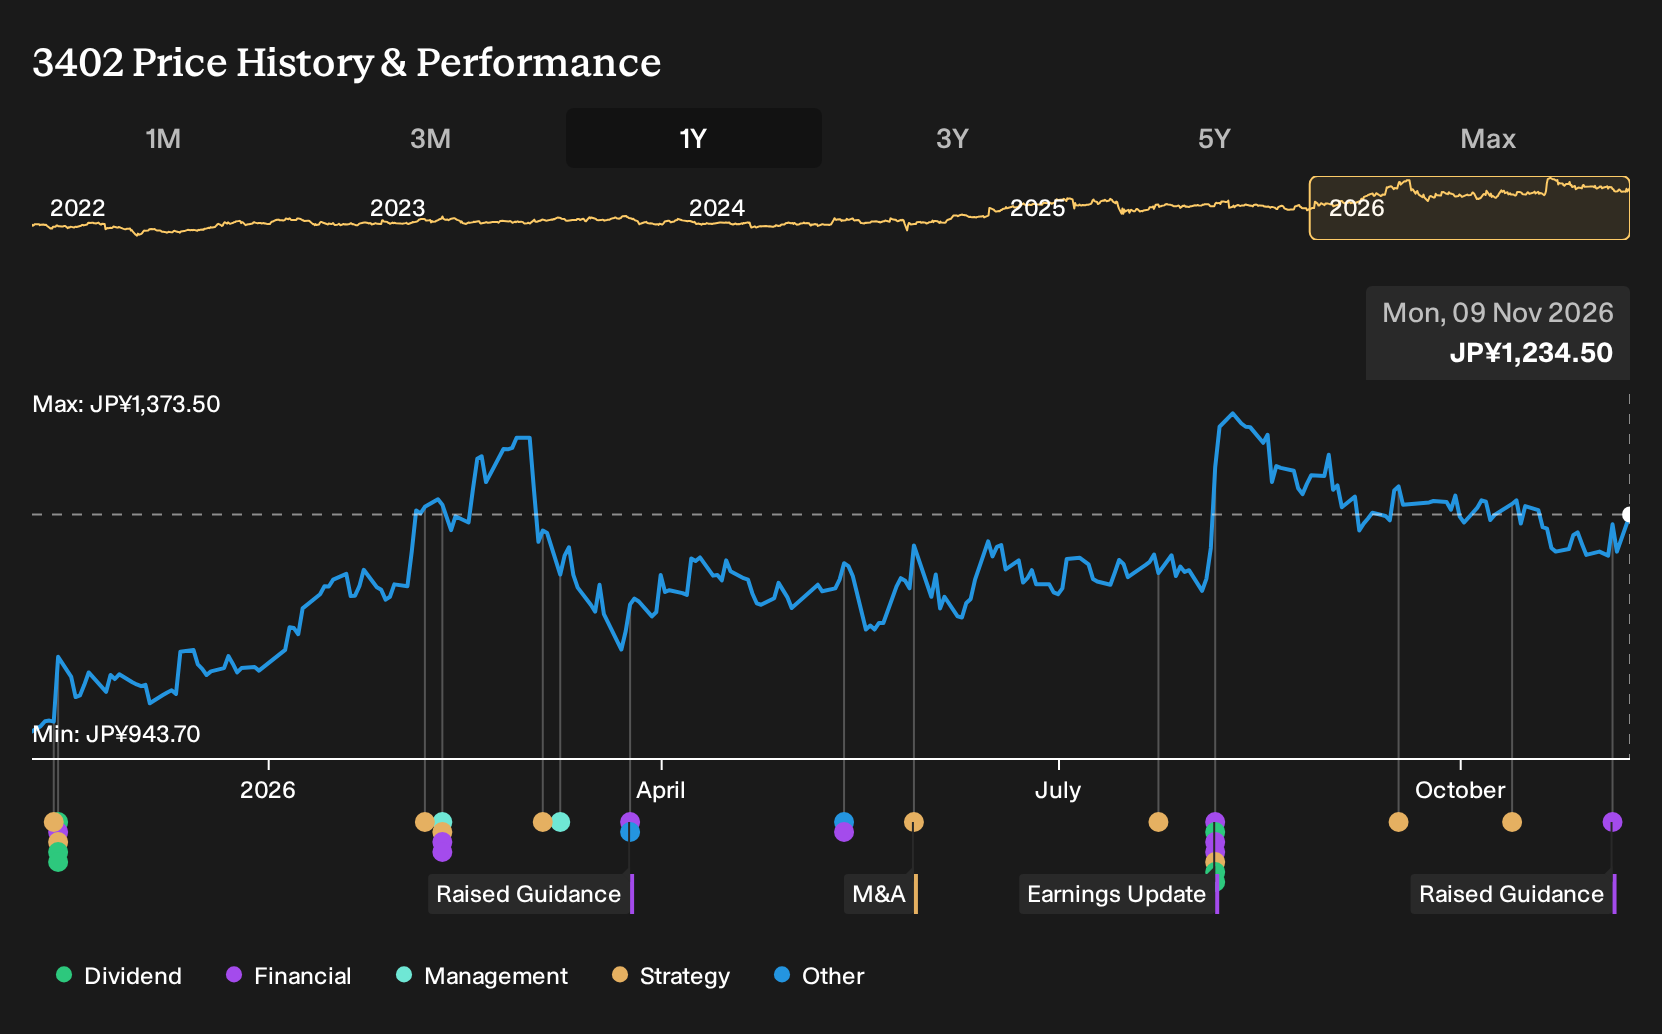
- Toray Industries revised its guidance for the six months ended September 30, 2026, now expecting revenue of ¥1,399,700 million and profit attributable to owners of parent of ¥69,100 million, or ¥47.45 per basic share.
- Management links the higher forecast to steady Performance Chemicals and other segments, as well as better non recurring items, which highlights how operational mix and one off factors are shaping Toray Industries earnings profile.
- We will look at how Toray Industries investment narrative is affected by this higher profit guidance and stronger Performance Chemicals contribution.
Scan how Toray Industries' updated guidance compares with 76 high quality undiscovered gems that also pair steady segment performance with improving one off items.
Toray Industries Investment Narrative Recap
To own Toray Industries, you need to be comfortable with a materials group that is reshaping its portfolio while dealing with uneven demand in areas like EV related battery separator films. The analyst consensus narrative on Simply Wall St focuses on Performance Chemicals, carbon fiber composites and water treatment carrying more weight over time. The raised half year profit outlook, tied to steadier Performance Chemicals and cleaner non recurring items, gives that portfolio shift a little more operational backing in the near term.
The near term swing factor still appears to be execution on Performance Chemicals and the Darwin Project reforms rather than any single macro driver. Weakness in resins, chemicals and certain films remains an active risk, especially if pricing and mix cannot offset it. The revised guidance does not remove those issues, but it suggests current measures are at least preventing further pressure on group profitability.
The guidance change itself is the key announcement here. Management now expects ¥1,399,700 million in revenue and ¥69,100 million in profit attributable to owners for the six months to September 30, 2026, up from earlier forecasts. That indicates operations are steadier than previously assumed, supported by Performance Chemicals and better non recurring items.
In terms of catalysts, this sits alongside longer term projects such as IGNITION 2028 and carbon fiber expansion. The raised outlook gives Toray Industries a bit more scope to fund capital expenditure and R&D plans while it works on improving returns in weaker areas such as EV related films. Execution risk in those underperforming pockets remains, but the updated numbers signal that group level profit is holding up as those adjustments continue.
Toray Industries’ projections assume revenue of ¥3.0722b and earnings of ¥136.9b by 2029, based on analysts incorporating 4.8% yearly revenue growth and an earnings increase of about ¥43.3b from current earnings of ¥93.6b.
Discover why Toray Industries' fair value suggests a 16% potential upside to its current price, which may materialize sooner than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts were already leaning on a stronger Performance Chemicals recovery at Toray Industries, pencilling in revenue of ¥3,244.8b and earnings of ¥171.9b by 2029 before this guidance lift. You can treat this raised forecast as a fresh data point and compare it with your own view to see how far it sits from that bullish camp.
Explore another Toray Industries fair value estimate, including one that suggests up to 16% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Toray Industries research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Toray Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toray Industries' overall financial health at a glance.
Looking for more Toray Industries style ideas?
If Toray Industries has sharpened your focus on segment quality, balance sheets, and risk, it can help to line it up against a wider set of candidates using the Simply Wall St Screener.
- If you care most about valuation support and solid fundamentals, compare Toray Industries with a wider pool of companies screened for 22 high quality undervalued stocks that fit similar quality criteria.
- For investors who put capital strength first, set Toray Industries alongside a list of solid balance sheet and fundamentals (23 results) to see which businesses carry the kind of financial resilience you want to own.
- If risk control is at the top of your checklist, broaden your watchlist beyond Toray Industries by filtering for 18 resilient stocks with low risk scores that better match your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com