


EN
Can Strong Earnings Change The Bull Case For ICF International Stock (ICFI)?
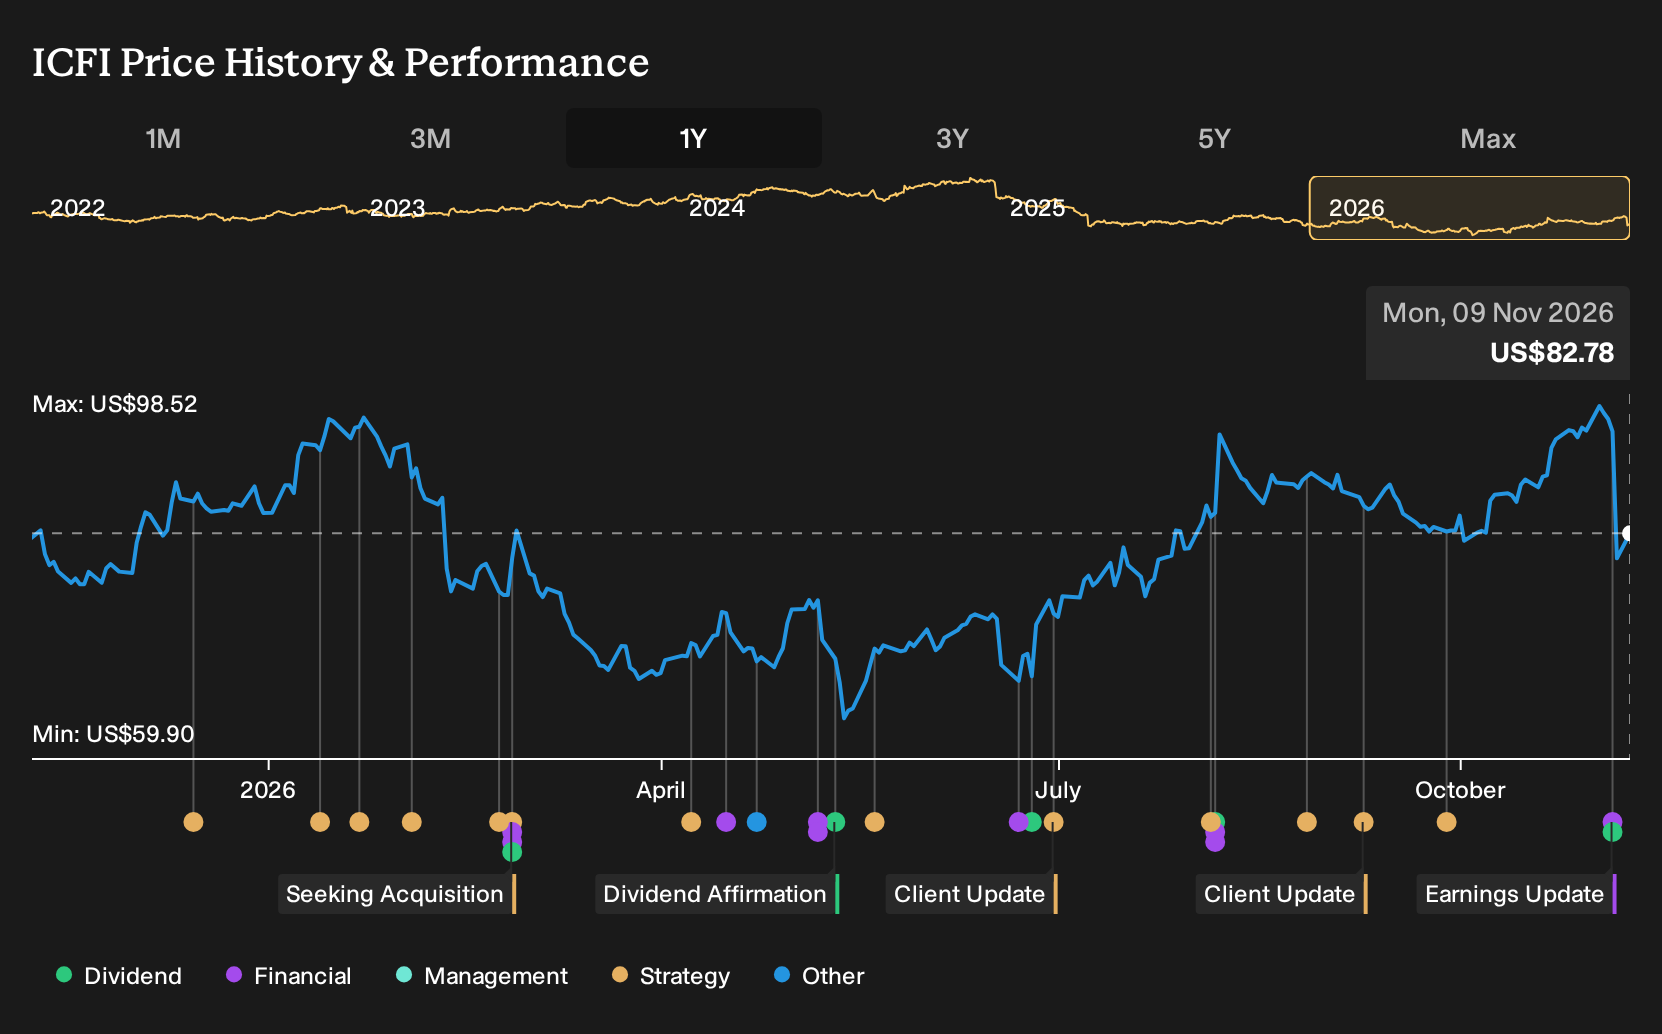
- ICF International reported third quarter 2026 sales of US$470.5 million and net income of US$31.73 million, with diluted EPS from continuing operations of US$1.76, and affirmed a quarterly dividend of US$0.14 per share payable in January 2027.
- The combination of higher earnings per share alongside a steady dividend indicates that ICF International is currently converting its consulting and implementation work into firmer profitability while also returning cash to shareholders.
- We will now look at how ICF International's third quarter earnings relate to the earlier investment narrative around mix shift and margins.
Scan beyond ICF International's latest earnings and dividend update to spot other consultants and contractors with resilient fundamentals using the hand picked list of solid balance sheet and fundamentals (25 results).
ICF International Investment Narrative Recap
To own ICF International, you need to believe that the shift toward commercial energy, state and local, and international work can offset pressure in U.S. federal contracts. The third quarter showed higher earnings on roughly flat quarterly sales, which supports that mix shift story but does not fully resolve the federal funding overhang.
The near term swing factor remains whether the US$9.3b pipeline and recent awards turn into a healthier backlog and steadier book to bill. Federal budget delays and prior backlog pressure are still the main operational risk, so this latest result helps sentiment but does not materially change that key watchpoint yet.
The analyst consensus narrative on Simply Wall St focuses on rising demand for energy efficiency, electrification, and grid resilience to support higher margin commercial energy work. In that context, ICF International’s third quarter net income of US$31.73 million and diluted EPS of US$1.76 show the business converting existing contracts into firmer profitability.
That profit progression matters because execution on current programs needs to fund investment in areas such as AI enabled federal IT modernization and disaster recovery, which analysts identify as important catalysts. If awards linked to those themes ramp as expected while federal revenue stabilizes, the recent earnings run rate could help support the margin and cash flow ambitions in that narrative.
ICF International's narrative projects US$2.2b revenue and US$149.6 million earnings by 2029. This corresponds to 7.1% yearly revenue growth and an earnings increase of about US$61 million from current earnings of US$88.5 million.
Uncover why ICF International's fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One contrasting angle on ICF International focuses on backlog risk rather than the commercial energy opportunity you keep hearing about. The most cautious analysts were already baking in roughly US$2.3b of 2029 revenue and US$152.8 million of earnings before this quarter. That camp sees the stock as fairly valued and might read these results very differently. It can therefore help to compare several narratives before deciding what you think this latest report really means.
Explore another ICF International fair value estimate, including one that suggests it could be worth just $107.25!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ICF International research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ICF International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICF International's overall financial health at a glance.
Looking For More Investment Ideas Beyond ICF International?
If this ICF International update has sharpened your view on quality and risk, use that same lens to scan a wider watchlist. The Simply Wall St Screener can help you quickly filter for businesses that fit the balance of resilience, income, or value you want, instead of chasing whatever is moving today.
- If capital preservation sits high on your list, start with a basket of companies flagged as relatively resilient using the 30 resilient stocks with low risk scores.
- Income focused investors can concentrate on stocks with higher yields by screening for sturdier payers through the 6 dividend fortresses.
- For those hunting for mispriced opportunities backed by fundamentals, cast a wider net using the hand picked 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com