


EN
Is Saab (OM:SAAB B) Undervalued After Its SEK 2,000 Million Naval Group Contract?
Saab (OM:SAAB B) drew investor attention after agreeing a roughly SEK 2,000 million contract with Naval Group to equip four FDI frigates for Sweden, with deliveries scheduled between 2027 and 2034.
The recent contract win comes at a time when Saab’s share price has been firming. The 30 day share price return stands at 6.64% and the year to date share price gain is 14.24%. The 1 year total shareholder return of 22.29% sits on top of a very large 5 year total shareholder return that is close to 10x the original investment, pointing to strong long term momentum despite some shorter term pullbacks.
Scan other defense and aerospace stocks showing similar contract driven momentum through our curated 202 resilient stocks with low risk scores, which emphasises resilient balance sheets and lower overall risk profiles.
Saab’s latest contract and strong long term return profile raise a simple tension. Are investors now paying more for the same earnings power, or has the underlying business reset what counts as a fair valuation?
Most Popular Narrative: 1.9% Undervalued
Saab’s last close at SEK639.50 sits just below the analyst consensus Narrative fair value of about SEK651.71. The analyst consensus Narrative on Simply Wall St bases this on detailed forecasts for revenue, earnings and margins, all discounted at 6.17%.
The record SEK 318b order backlog, with about 60% scheduled within 2.5 years and SEK 120b contracted from year three onwards, gives Saab multi year revenue visibility that can help support steadier cash generation and earnings quality.
Recent gross margin at a record level and more than 1 percentage point expansion year on year, helped by scale in Surveillance and Dynamics as programs like Giraffe 1X ramp, indicates that efficiency gains and higher volumes can continue to support net margins and EBIT.
See why 119 investors see Saab as 2% undervalued.
Result: Fair Value of SEK651.71 (ABOUT RIGHT)
Still, the Saab narrative could be knocked off course if supply chain bottlenecks slow conversion of the SEK 318b backlog, or if lower margin open book contracts dilute profitability.
Find out about the key risks to this Saab narrative.
Another View: Saab Looks Expensive On Earnings
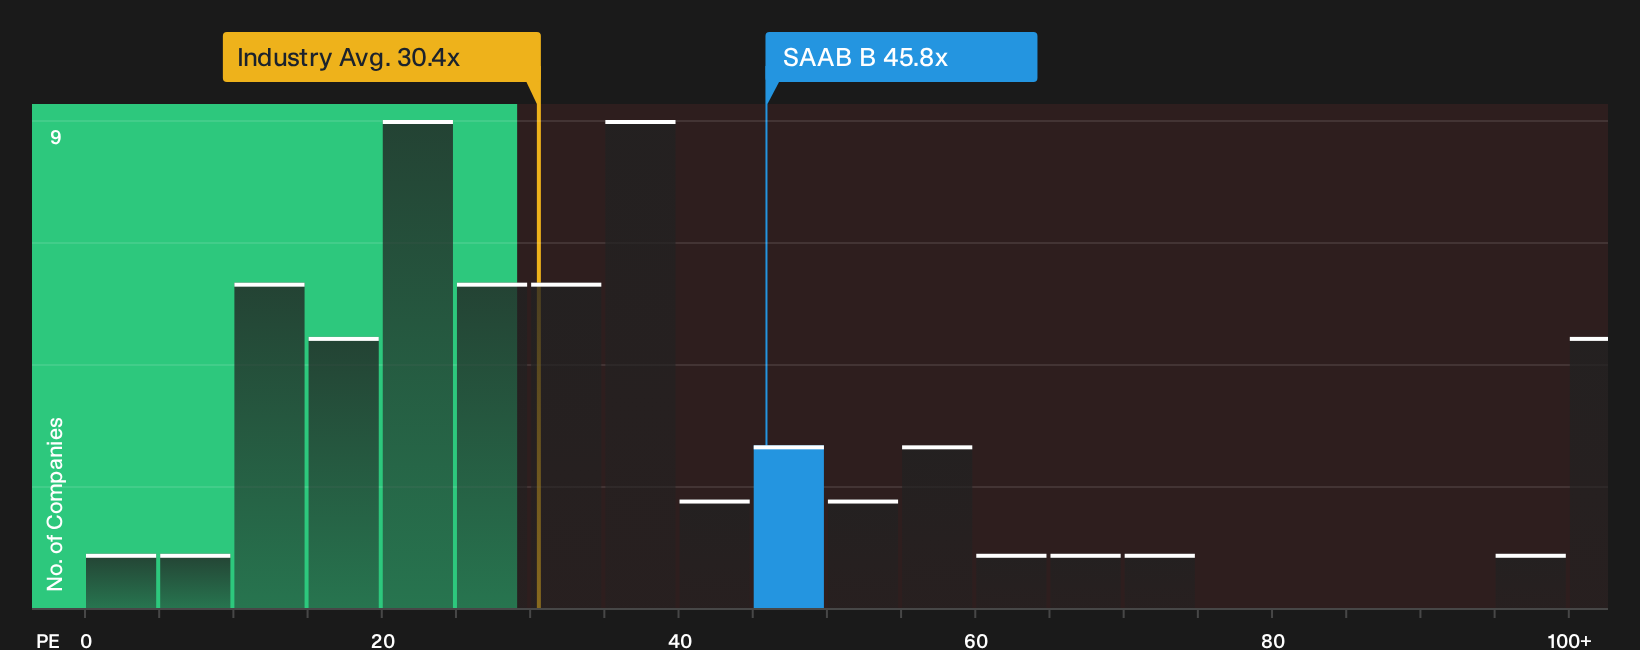
The fair value narrative paints Saab as roughly correctly priced, but the P/E ratio tells a tougher story. At about 45.8x earnings versus 30.4x for the European Aerospace & Defense group and a fair ratio of 34.9x, investors are paying a clear premium. Is that rich multiple really the risk profile you want?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Saab’s valuation story. Use the data, not the headlines, to frame your own stance and weigh up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Saab?
If you only stop at Saab, you risk missing other opportunities where quality, price and durability of returns line up in a way that suits your style.
- Target potential mispricings by scanning a curated universe of businesses trading below assessed value through the 210 high quality undervalued stocks.
- Strengthen your passive income plans by focusing on reliable payers and payout strength using the 222 dividend fortresses.
- Prioritise resilience by zeroing in on companies with robust finances and clean balance sheets through the list of solid balance sheet and fundamentals (194 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com