


EN
Novanta’s (NASDAQ:NOVT) Q3 2026 sales beat estimates but guides down full-year adjusted EPS
Medicine and manufacturing technology provider Novanta (NASDAQ:NOVT) announced better-than-expected revenue in Q3 2026, with revenue up 23.1% year on year to $305 million. The company expects next quarter’s revenue to be around $309 million, close to analysts’ consensus estimates. Its non-GAAP profit of $1.05 per share was 8.6% above analysts’ consensus estimates.
For more on Novanta, read our free full research report.
Novanta (NOVT) Q3 2026 highlights:
- Revenue $305 million vs S&P analyst consensus of $301 million (23.1% year-on-year growth, 1.3% beat)
- Adjusted EPS $1.05 vs S&P analyst consensus of $0.97 (8.6% beat)
- Adjusted EBITDA $80.34 million vs analysts’ consensus estimates of $76.96 million (26.3% margin, 4.4% beat)
- Revenue guidance $309 million at the midpoint for Q4 2026, roughly in line with analysts’ consensus estimates
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $3.69 at the midpoint, a 0.7% decrease
- EBITDA guidance $275.5 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 4.6%, down from 11.5% in the same quarter last year
- Free cash flow margin 10%, up from 1.7% in the same quarter last year
- Market capitalization $5.11 billion
“The third quarter marked a significant milestone for Novanta as we closed the largest acquisition in our history and delivered strong financial results that exceeded our expectations,” said Matthijs Glastra, Chair and Chief Executive Officer. “Momentum continued in the third quarter as revenue advanced 23% and we achieved an Adjusted EBITDA margin of 26%, which improved 290 basis points year-over-year. Customer bookings increased 29%, reflecting strong commercial momentum and providing a solid foundation for future growth, expanding our backlog to $543 million. Equally important, Riverpoint Medical is performing in line with expectations as we continue to make meaningful progress on our operational synergies, while driving an exciting new product pipeline. Collectively, these results demonstrate the strength of our strategy and our continued commitment to driving sustainable growth and long-term shareholder value.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a poor business can perform well for one or two quarters, but a top-tier one grows for years. Novanta’s 10.6% annualized revenue growth over the last five years was strong. Its growth beat the average industrials company and shows its offerings resonate with customers.
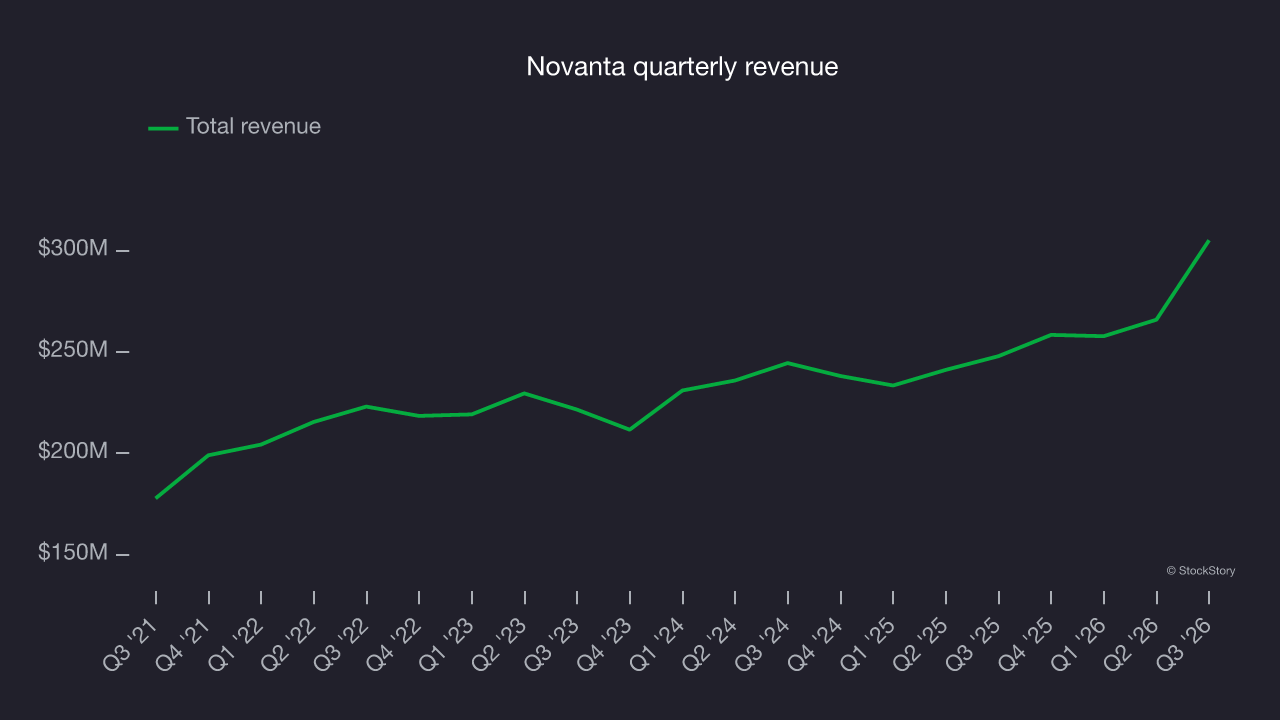
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Novanta’s annualized revenue growth of 8.5% over the last two years is below its five-year trend, but the results still suggest healthy demand. 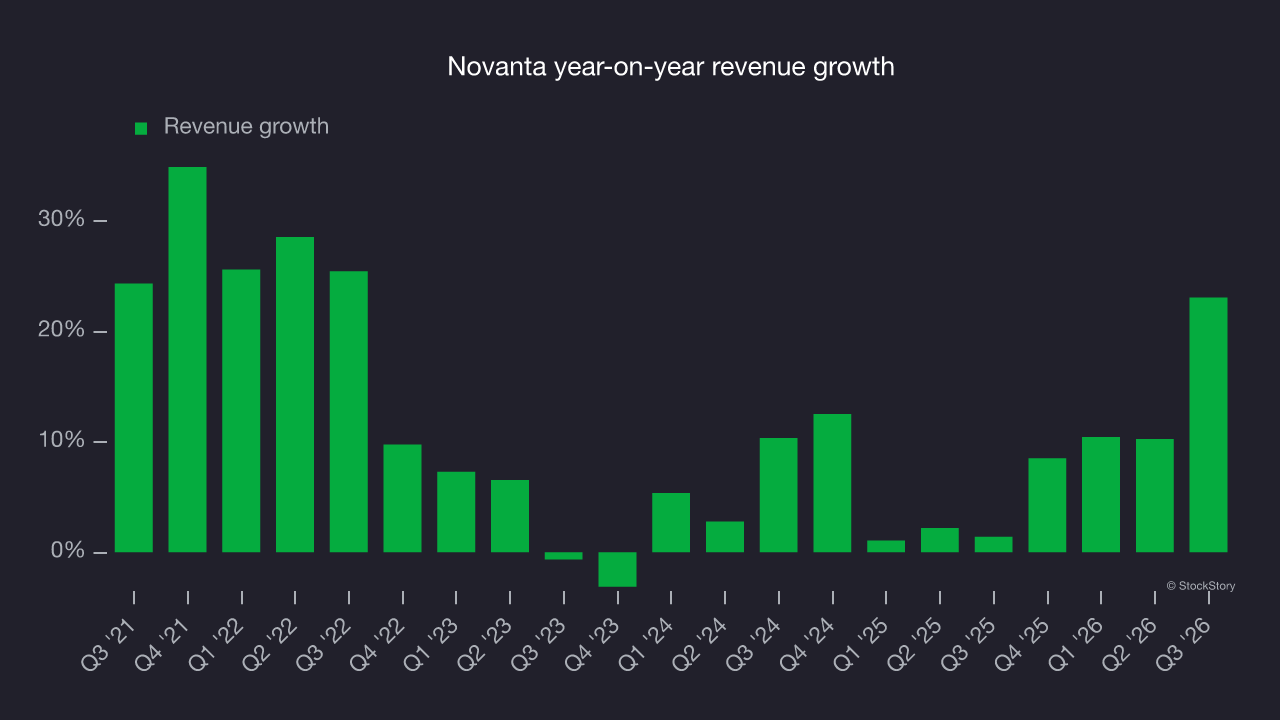
This quarter, Novanta reported strong year-on-year revenue growth of 23.1%, and its $305 million of revenue topped Wall Street’s consensus estimates by 1.3%. Management is guiding for a 19.6% year-on-year increase in revenue next quarter.
Projected revenue growth also helps assess companies, but not enough Wall Street analysts cover Novanta for it to have reliable consensus estimates. This suggests Novanta could be an overlooked investment opportunity because it gets little attention from professional brokers.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, or the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Over the last five years, Novanta’s operating margin fell by 2.2 percentage points. This deterioration shows its costs grew relative to revenue, putting pressure on profitability. Its trailing 12-month operating margin was 9.6%.
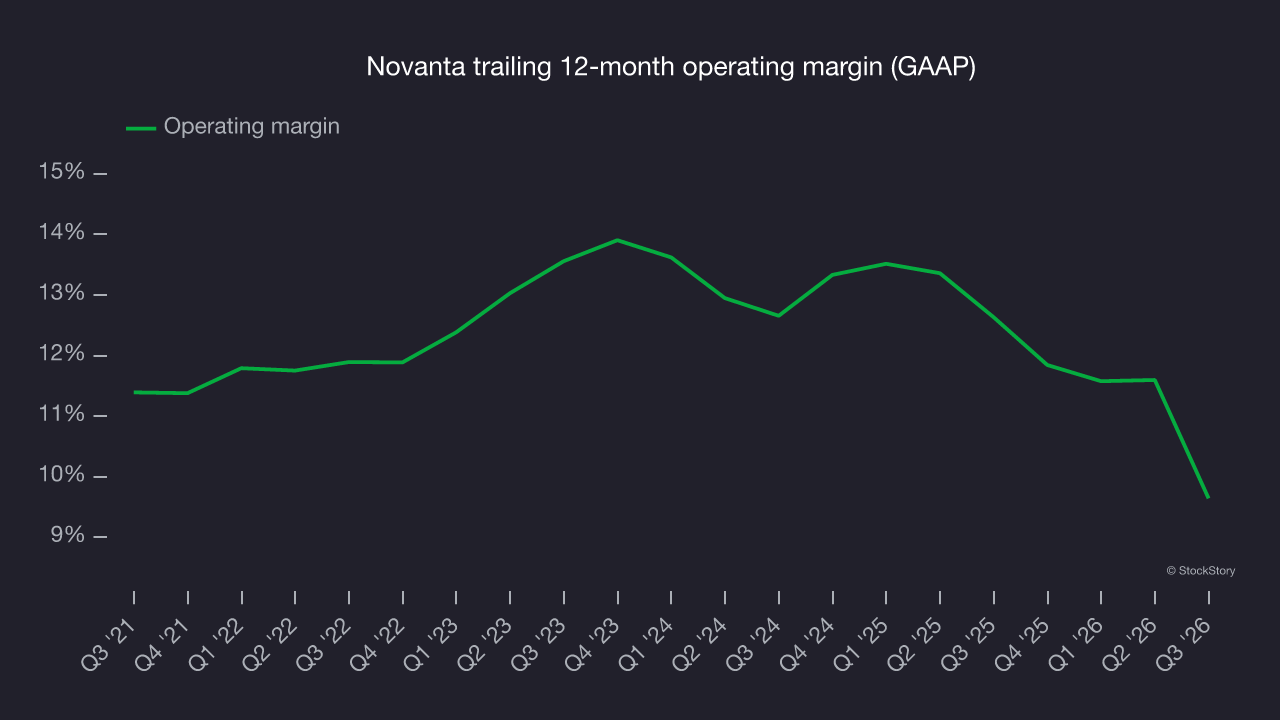
In Q3, Novanta generated an operating profit margin of 4.6%, down 6.9 percentage points year on year. Its operating margin fell more than its gross margin, indicating reduced efficiency as expenses such as marketing, research and development and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Novanta’s EPS grew at an uninspiring 8.1% compounded annual growth rate over the last five years, lower than its 10.6% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
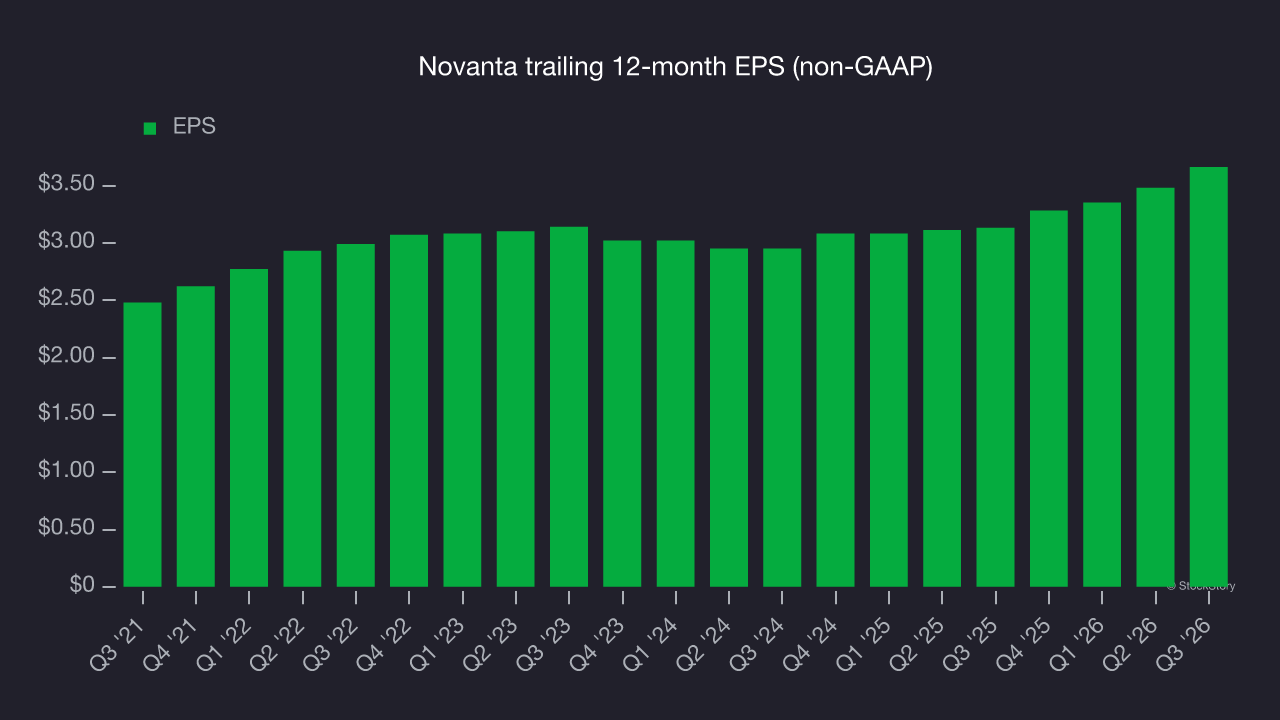
A closer look at Novanta’s earnings helps explain the drivers of its performance. As mentioned earlier, Novanta’s operating margin declined by 2.2 percentage points over the last five years. Its share count also grew by 19.4%, meaning the company not only became less efficient with its operating expenses but also diluted its shareholders. 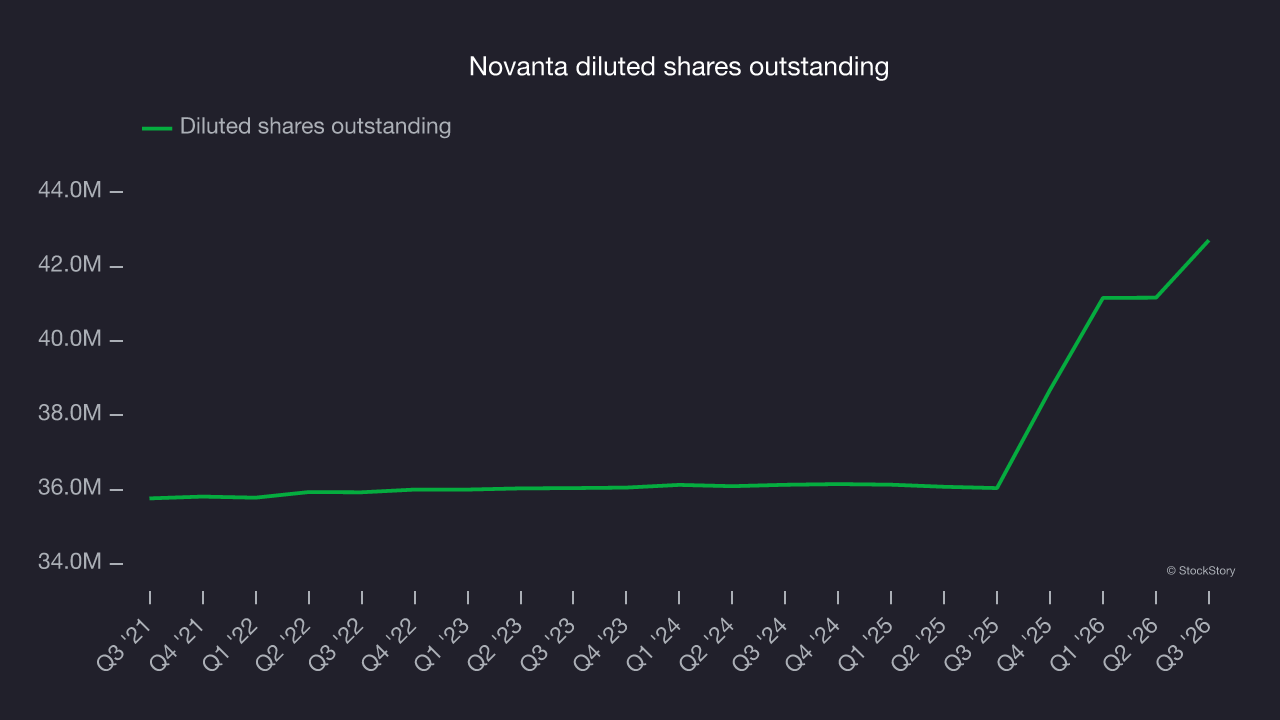
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Novanta, its two-year annual EPS growth of 11.4% was higher than its five-year trend. Accelerating earnings growth is almost always a positive sign.
In Q3, Novanta reported adjusted EPS of $1.05, up from $0.87 in the same quarter last year. This result beat analysts’ consensus estimates by 8.6%. Over the next 12 months, Wall Street expects Novanta’s full-year EPS to grow 13.2% from $3.66 to $4.14, according to S&P.
Key takeaways from Novanta’s Q3 results
Novanta’s Q3 results had some key positives: EBITDA beat analysts’ consensus estimates, and revenue came in narrowly ahead of Wall Street’s consensus. But EBITDA guidance for next quarter fell short of expectations. Investors were likely hoping for more, with shares falling 3% to $141.86 immediately after the release.
Before investing, it’s important to consider the stock’s valuation, business quality and what happened in the latest quarter. Read the full research report here (it’s free).