


EN
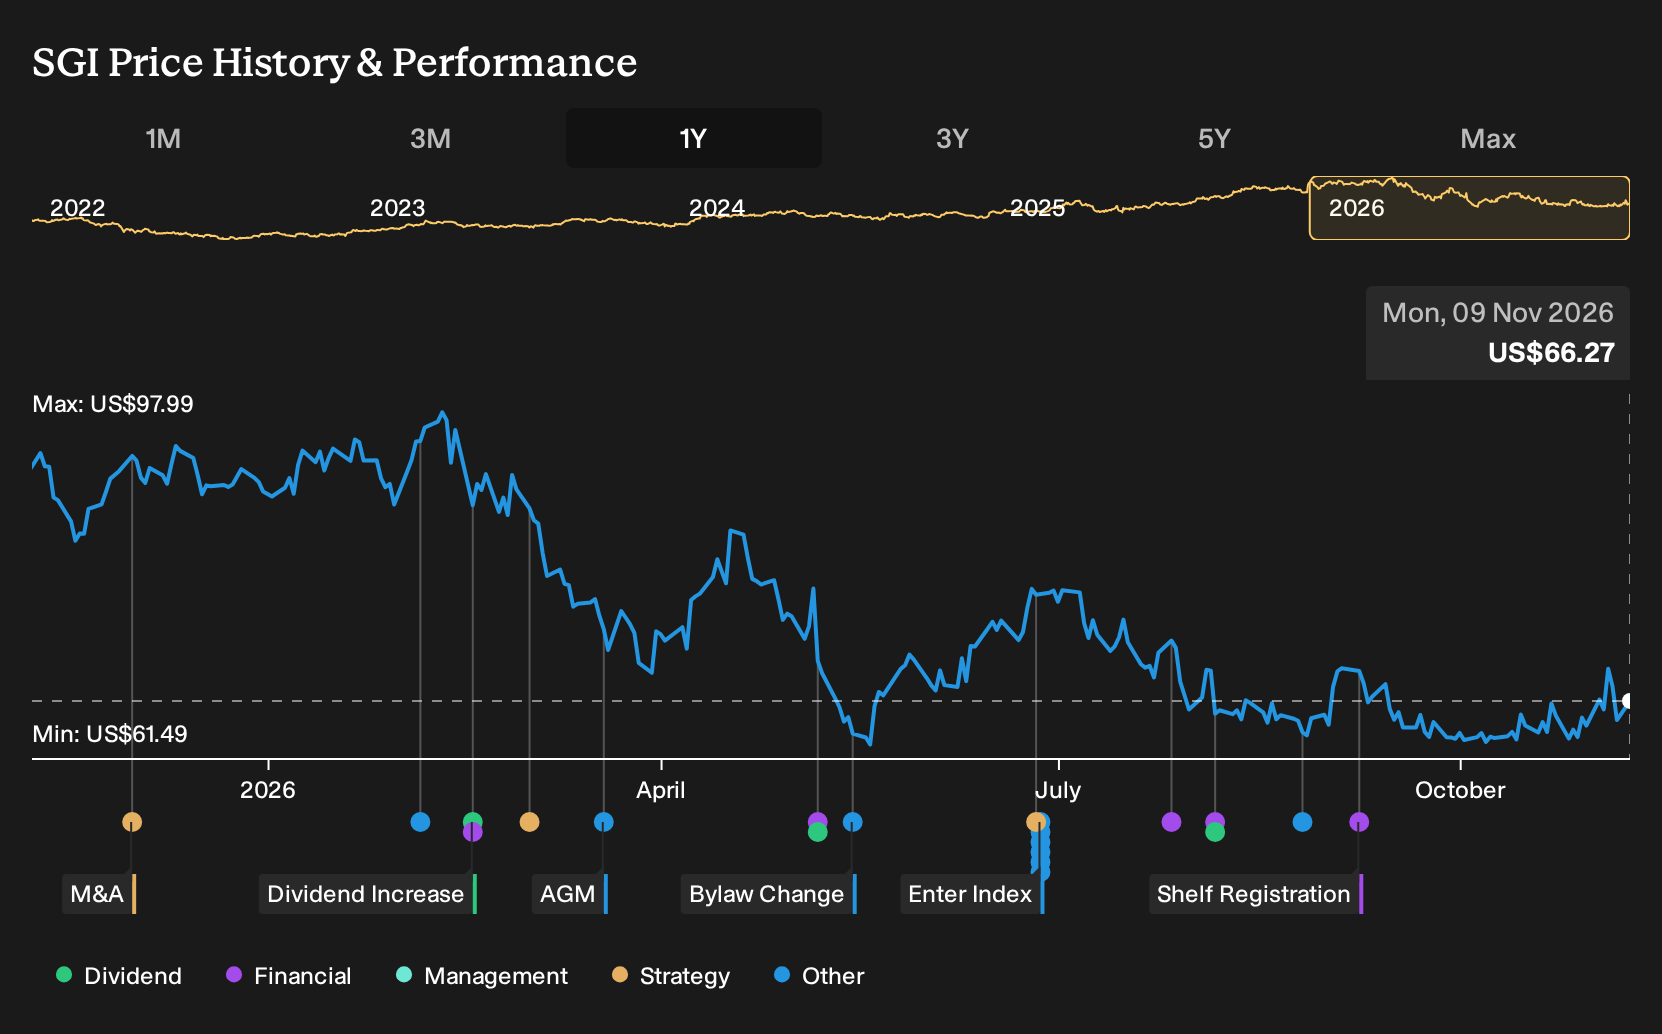
Did Mixed Earnings And Dividend Affirmation Just Shift Somnigroup International (SGI) Investment Narrative?
- Somnigroup International reported third quarter 2026 sales of US$2,350.8 million and net income of US$163.5 million, and the board approved a US$0.17 per share fourth quarter dividend payable on December 7, 2026 to investors on record as of November 23, 2026.
- The mix of higher sales alongside lower quarterly earnings per share from continuing operations, paired with a maintained cash dividend, highlights how Somnigroup International is balancing top line momentum with profitability pressures and shareholder cash returns.
- Next, the focus turns to how Somnigroup International's mixed earnings and affirmed dividend could influence the longer term investment narrative.
Compare Somnigroup International's income and dividend profile with a hand picked 7 dividend fortresses to see how other cash returning businesses stack up on yield and consistency.
Somnigroup International Investment Narrative Recap
To own Somnigroup International, you need to believe the bedding group can turn higher sales and its Mattress Firm integration into durable earnings, even as quarterly EPS from continuing operations eased. The analyst consensus Narrative on Simply Wall St highlights cost synergies, international expansion and sleep technology as supporting factors, while you weigh how realistic those levers feel.
The key near term swing factor is execution on cost control and pricing, given pressures from input costs, digital competitors and Somnigroup International's debt load. The latest quarter, where sales and net income moved in different directions, does not radically shift that story but keeps attention on margins.
The most relevant update for that thesis is Somnigroup International's third quarter and nine month earnings release. Sales reached US$2,350.8 million for the quarter and US$5,975.8 million for the nine months, while net income was US$163.5 million and US$378.6 million respectively, framing how the Mattress Firm integration and broader bedding portfolio are feeding through to the income statement.
Basic EPS from continuing operations of US$0.75 in the quarter and US$1.78 across nine months, alongside a US$0.17 per share dividend, provide concrete numbers to compare against the analyst consensus Narrative on Simply Wall St regarding earnings and margins. The risk side remains focused on Somnigroup International's high debt, exposure to North America and competition from digital native bedding brands.
Somnigroup International's current analyst storyline points to revenue of US$12.2b and earnings of US$1.1b by 2029, with this implying 16.9% yearly top line growth and an earnings increase of roughly US$566.7m from US$533.3m today.
Uncover why Somnigroup International's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The lowest analysts latch onto integration risk. They argue Somnigroup International could see earnings track closer to about US$1.1b on roughly US$12.4b of revenue by 2029, with less P/E expansion than consensus implied. That more cautious script looked conservative even before this fresh dividend and earnings update, so it may evolve.
Explore 2 other Somnigroup International fair value estimates, including one that suggests it could be worth just $90.44!
Decide For Yourself
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Somnigroup International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Somnigroup International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Somnigroup International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Somnigroup International?
Somnigroup International might be the starting point for your research, but your portfolio decisions usually benefit from comparing it with other businesses that match your risk tolerance, income needs and return goals. The Simply Wall St Screener can help you quickly filter for different types of opportunities that align with what you want from the market.
- If capital preservation sits high on your priority list, consider screening for 31 resilient stocks with low risk scores that combine more resilient balance sheets with lower volatility profiles.
- If you are hunting for potential mispricings, look across 40 high quality undervalued stocks where stronger fundamentals and pricing signals line up.
- If you prefer to back under the radar opportunities, scan through 19 high quality undiscovered gems that pair solid financials with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com