


EN
What Elekta Holders Saw Early
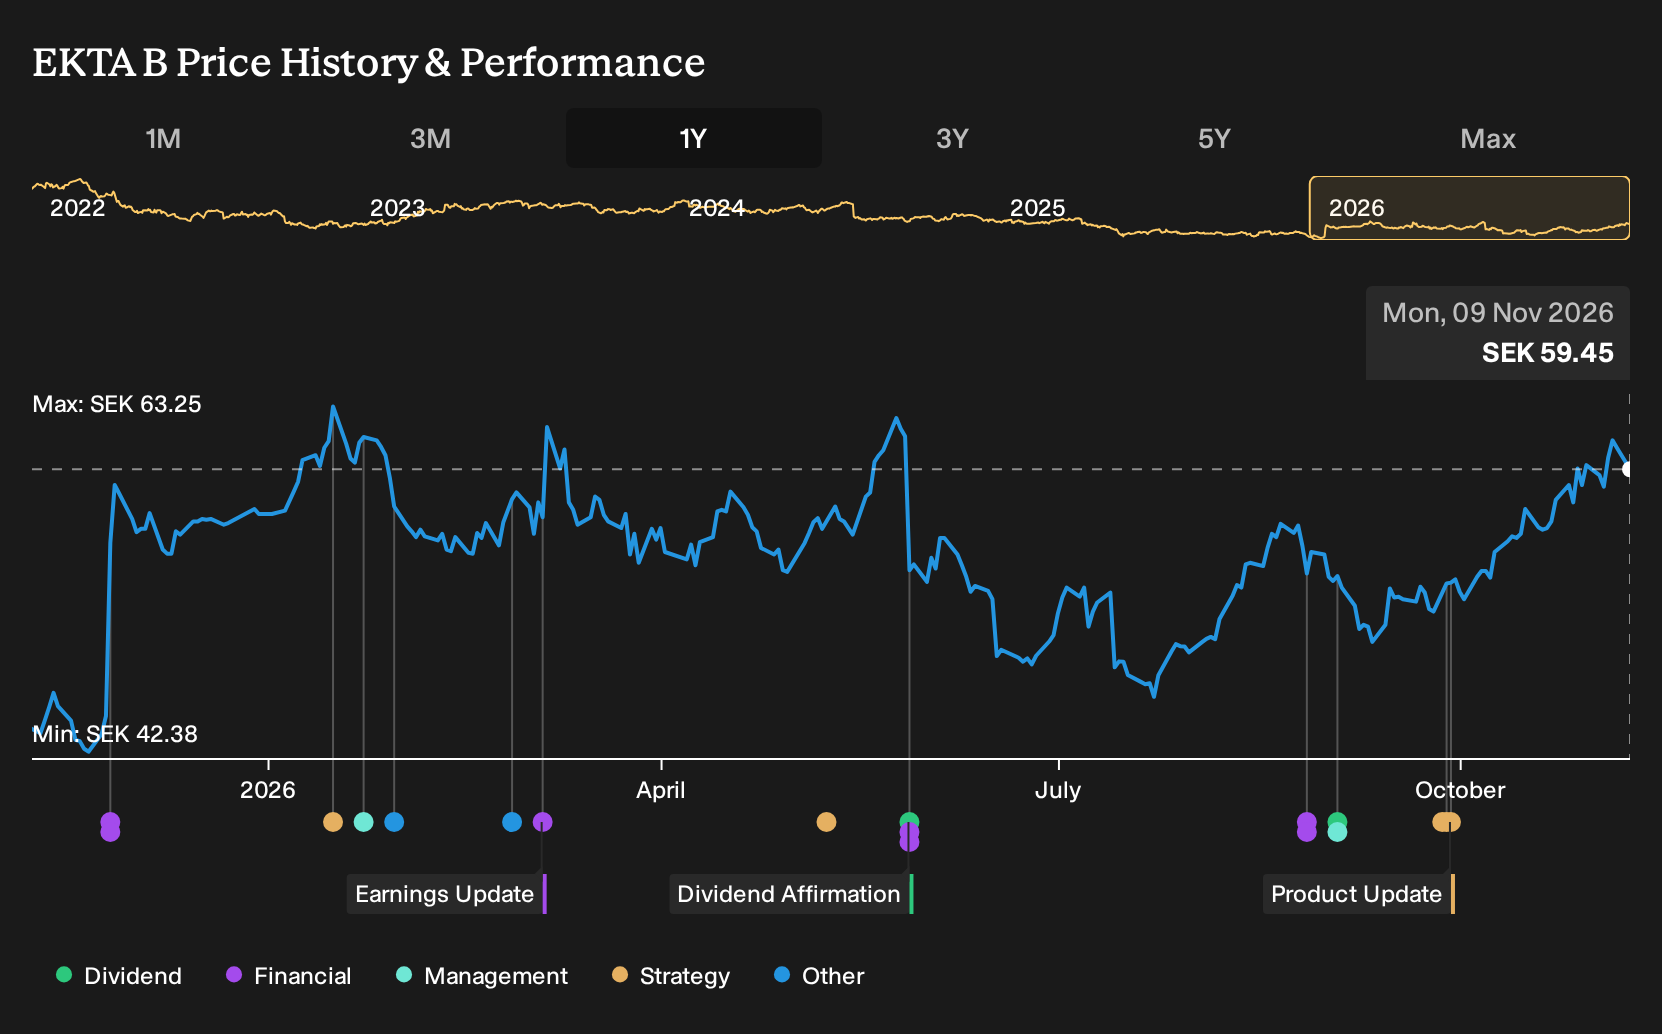
If Elekta had sat on your watchlist instead of in your portfolio, the past year might feel like a missed call. Investors who held Elekta over the past year are up 42.8%, including dividends. That is a strong outcome for a business that entered the period with analysts split between a European software driven upswing and margin pressure from tariffs and competition. If you go back to November 2025, how clearly was the bet on expanding precision radiotherapy adoption already on the table?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Elekta is not the only name tied to this theme. Zero in on 127 healthcare AI stocks and compare how each one is priced.
The Two Elekta Stories Investors Had In Front Of Them
The shares cost SEK43.9 at the start of the period, and Elekta sat between two very different but reasonable stories about where the business might head next.
The bullish narrative saw European software launches and a recovery in China lifting precision radiotherapy adoption, with a Fair Value of SEK53.79 based on assumptions such as 4.4% annual revenue growth.
The bearish view put Fair Value at SEK34, focused on trade barriers and reimbursement pressure, and built around a more cautious 1.0% revenue growth assumption and the risk of underinvestment in R&D.
What The Results Changed For The Elekta Case
The clearest new fact was Elekta’s Q1 2027 result, where revenue moved from SEK3,646m to SEK3,536m while net income excluding extra items rose from SEK107m to SEK264m. That combination, together with margin improving from 2.9% to 7.5%, supported the optimistic margin story. Cost cuts and the transformation plan also echoed the bull case, although softer orders kept the cautious thesis alive.
The practical takeaway is simple. When a thesis depends on margin repair, focus on net income and net margin, not just sales. For the next company on your list, test any profitability claim directly against those two figures in each quarterly report.
What Elekta’s Price Already Assumes
Elekta shares now trade at SEK59.45, with this cautious Narrative’s Fair Value sitting below that level. The bearish analyst Narrative on Simply Wall St frames the gap as a question about how solid the margin repair really is while headline sales stay soft in several regions.
For today’s price to add up, you would be assuming that cost savings, adaptive radiotherapy uptake and software attachment keep offsetting weaker solution sales and pressure in APJ, China and TIMEA.
"Although Elekta reports higher gross and EBIT margins supported by cost savings, the recent 2% constant currency decline in net sales and 9% drop in solution sales indicate that trade frictions and tariff volatility could resurface against a weaker top line and compress future gross margin and earnings rather than just fluctuate around current levels."
One Narrative disagrees with today's price. → See where this Narrative says Elekta should trade
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 43% below our estimate - targets recurring test orders from emerging AI server and data center programs.
- Company 2 - 20% below our estimate - converts deep partnerships into higher margin cloud, security and AI implementation work.
- Company 3 - 25% below our estimate - pivots core shipbuilding backlog toward cleaner dual fuel and LNG powered fleets.
Three companies from the same screener. Open every one of the 218 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com