


EN
How Investors May Respond To Pilgrim's Pride (PPC) Lower Earnings
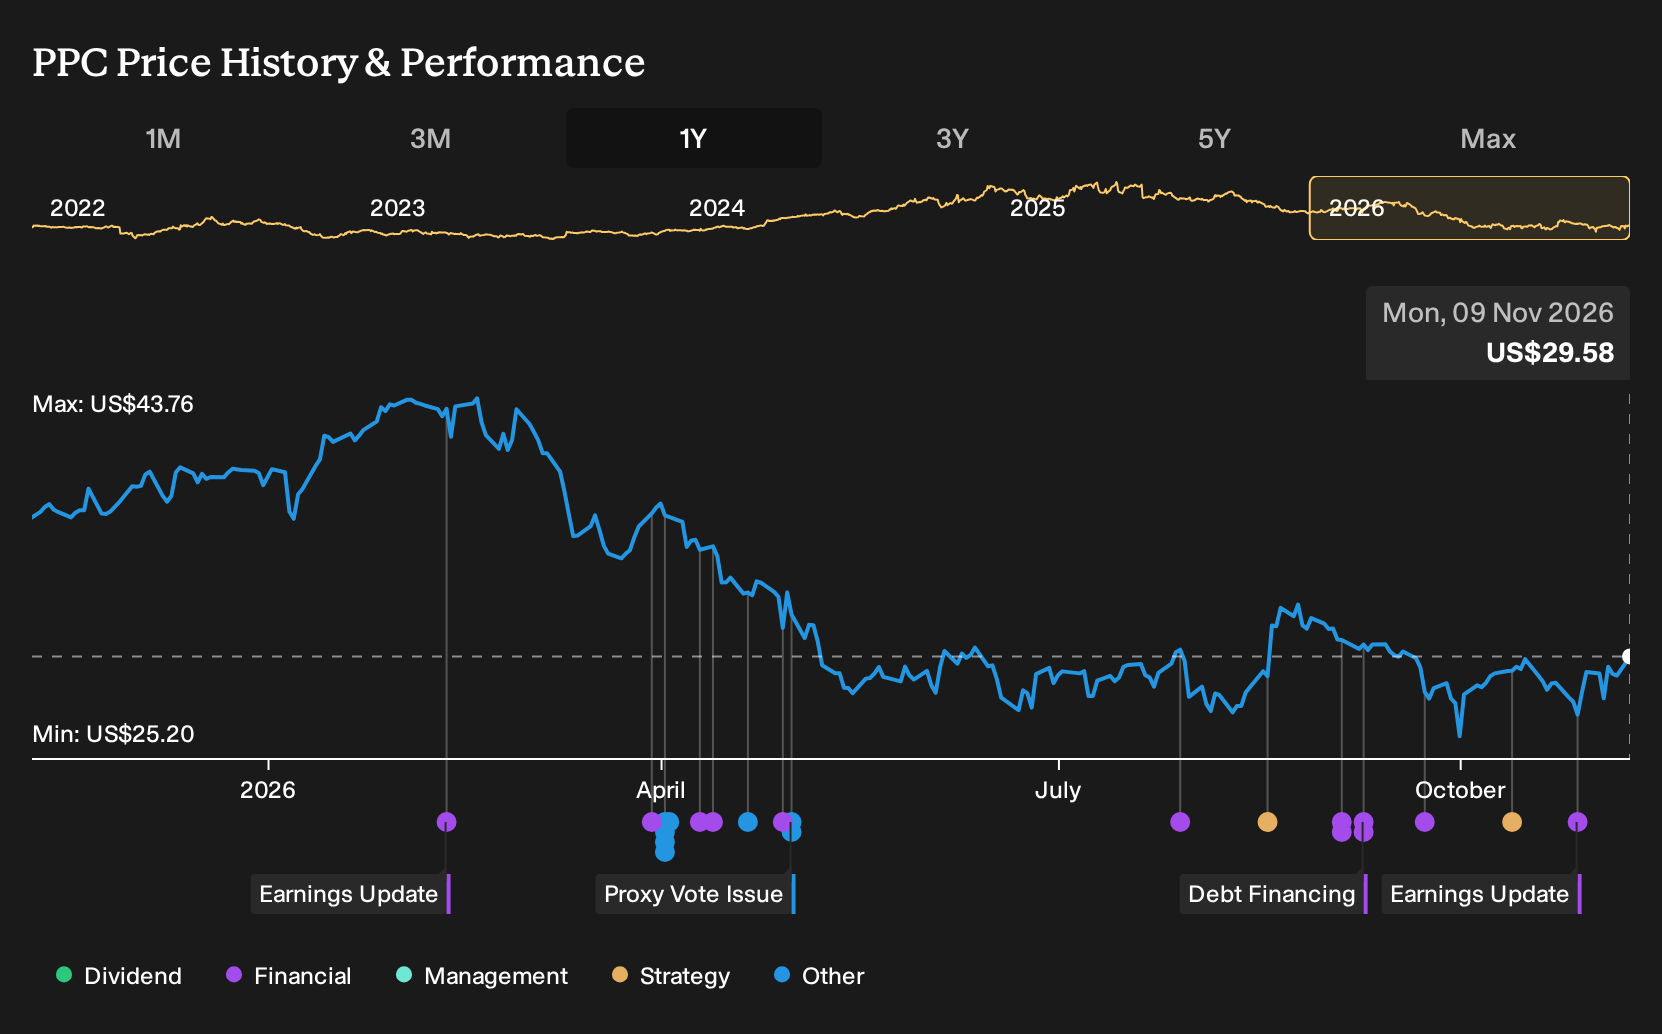
- Pilgrim's Pride reported third quarter 2026 sales of US$4,653.21 million and net income of US$117.61 million, with earnings per share from continuing operations of US$0.49.
- For the first nine months of the year, Pilgrim's Pride reported lower profitability, as net income declined to US$232.41 million and earnings per share dropped below US$1, indicating pressure on the underlying meat processing business.
- Next is an assessment of how Pilgrim's Pride's investment narrative could evolve in light of weaker earnings compared with the prior year.
Compare how Pilgrim's Pride's earnings reset stacks up against other meat and food producers facing margin pressure by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
Pilgrim's Pride Investment Narrative Recap
For a shareholder in Pilgrim's Pride, the core belief is that heavy spending on prepared foods, brands and efficiency projects eventually earns a solid return, even when commodity chicken cycles are rough. The latest results, with nine month net income of US$232.41 million and earnings per share below US$1, keep the focus on whether margins can rebuild from a weaker base.
The analyst consensus narrative on Simply Wall St highlights prepared foods mix, consumer trade down to chicken and international expansion as key supports. In the near term, the main swing factor is still chicken supply and pricing. The biggest risk remains prolonged margin pressure in the U.S. and Mexico, especially if legal costs stay elevated and debt feels heavier on thinner earnings.
With no fresh corporate announcements alongside the third quarter release, this earnings update itself is the main reference point for Pilgrim's Pride right now. The step down in quarterly profit to US$117.61 million and basic earnings per share of US$0.49 versus the prior year keeps attention on how quickly ongoing capex and mix upgrades can influence results.
In terms of potential catalysts, investors are likely to track whether prepared and branded products start to form a larger share of that US$4,653.21 million quarterly sales figure, and whether Mexico and Europe move closer to supporting group profitability rather than pulling it back. Execution against these operational goals, under the weight of prior one off legal costs and a high debt load, sits at the center of the current balance between risks and potential rewards.
Pilgrim's Pride is currently modelled by analysts to reach US$19.6b in annual revenue and US$854.6 million in earnings by 2029, based on an assumed 2.1% yearly revenue growth rate and an earnings increase of about US$309 million from current earnings of US$545.6 million.
Discover why Pilgrim's Pride's fair value indicates a 13% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Pilgrim's Pride focuses on Mexico eventually turning into a stronger earnings engine rather than just a drag. The most optimistic analysts were penciling in about US$20.9b of revenue and roughly US$1.2b of earnings by 2029 before this report. You can compare that upbeat view to these weaker 2026 results and decide which storyline feels more realistic, knowing both sets of forecasts may shift after this earnings reset.
Explore 2 other Pilgrim's Pride fair value estimates, including one that suggests potential upside of as much as 13% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pilgrim's Pride research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Pilgrim's Pride. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pilgrim's Pride's overall financial health at a glance.
Looking for more Pilgrim's Pride style investment ideas?
Once you have a view on Pilgrim's Pride, it can help to line it up against other opportunities that share similar financial traits. The Simply Wall St Screener lets you quickly filter for businesses that fit the balance of quality, risk and return potential you are aiming for.
- If you want potential value coupled with resilience, take a look at 40 high quality undervalued stocks that combine solid fundamentals with prices the market has not fully rewarded yet.
- For investors who put capital protection first, focus on 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- Income focused readers may prefer to start with 7 dividend fortresses offering higher yields that can help support total return through the cycle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com