


EN
Is Freshpet (FRPT) Cheap As Guidance Rises And The Buyback Lands?
Why Freshpet’s latest earnings and guidance shift matter for investors
Freshpet (FRPT) has raised its 2026 net sales growth guidance, reported new quarterly results, and completed a US$102.26 million buyback. These developments are drawing renewed attention to the stock’s risk and reward profile.
The recent guidance hike and completed buyback come after a choppy run for Freshpet, with the share price down 7.5% over the past week and 10.3% over 90 days, yet supported by a 16.3% 1-year total shareholder return that points to improving longer-term momentum.
Compare Freshpet’s guidance upgrade and buyback to other potential opportunities by scanning our hand picked list of 19 high quality undiscovered gems with similar fundamentals and different risk profiles.
Freshpet’s sharper sales targets and completed buyback sit against a share price that has slipped in the short term. Is this move more about the pet food business or shifting sentiment around the stock?
Most Popular Narrative: 24% Undervalued
Freshpet’s last close of $64.39 sits well below the fair value of $84.25 implied by the analyst consensus Narrative on Simply Wall St, which builds off detailed revenue and earnings forecasts discounted at 7.24%.
The main thing that has to go right is that Freshpet continues to convert more households into higher spending MVP and online shoppers, while managing logistics costs and competitive pressure so that rising volumes translate into the margin and cash flow outcomes management is targeting.
See why 13 investors see Freshpet as 24% undervalued.
Result: Fair Value of $84.25 (UNDERVALUED)
Still, Freshpet’s story can change quickly if logistics expenses keep rising or if household penetration slows further and growth relies too heavily on existing MVP users.
Find out about the key risks to this Freshpet narrative.
Another View: Freshpet looks pricey on earnings multiples
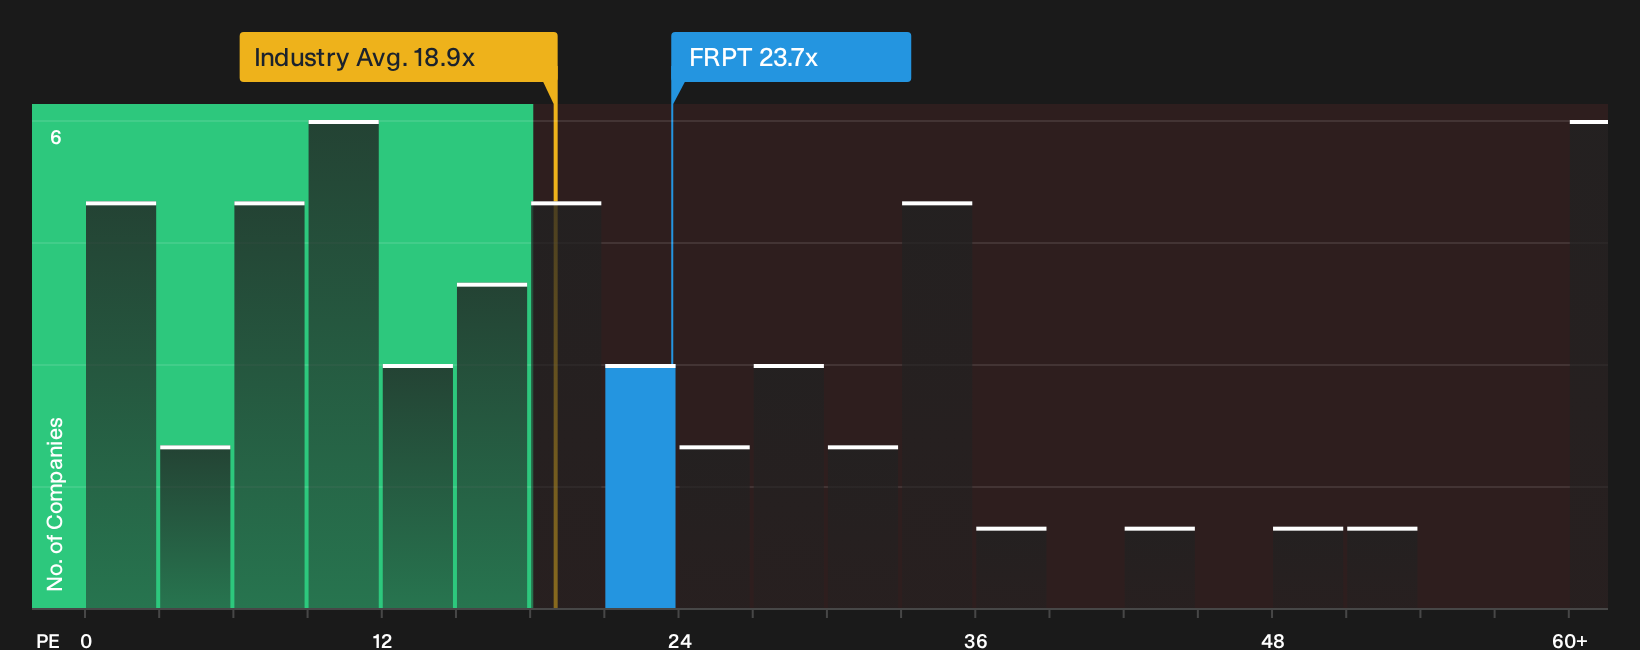
Freshpet might look appealing against an $84.25 fair value from the analyst Narrative, yet the current P/E of 23.7x is richer than the US Food industry at 18.9x, above the peer average of 21.6x, and well ahead of a 16.1x fair ratio the market could move toward. Is the premium a cushion or a source of future valuation pressure if expectations cool?
That is where valuation checks using earnings multiples need extra context, because richer pricing against the industry, peers, and a lower fair ratio can mean less room for error if growth or margins miss the script, even when other models suggest upside. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Freshpet story so far. If you want to move quickly and build your own stance, weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Freshpet?
You have seen what matters for Freshpet. Do not stop there. Broaden your watchlist now and give yourself more options before the next move.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) so you focus on companies with financial foundations that can better handle business shocks.
- Hunt for mispriced opportunities with a 40 high quality undervalued stocks that highlights businesses combining quality fundamentals with valuations that differ from market expectations.
- Prioritise stability and income potential by reviewing a 7 dividend fortresses that filters for higher yielding companies with stronger underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com