


EN
Fresnillo (LSE:FRES) Eyes A Major Mexico Silver Mine, Is The Stock Cheap?
Fresnillo (LSE:FRES) has come back into focus after fresh commentary on its direct silver exposure and plans for a major new underground mine in Mexico, set against tight global silver supply.
Recent trading tells a mixed story. Fresnillo’s share price has jumped 4.97% in the last day and 12.88% over the past week, yet is down 21.30% year to date and 10.52% over 90 days. Over three years, the total shareholder return of about 4.7x suggests that investors continue to factor in both upside potential and risk related to its silver exposure and new mine plans.
Scan for other precious metal producers showing similar leverage to tight supply by reviewing the hand picked 10 top silver producer stocks alongside Fresnillo’s latest move in Mexico.
Fresnillo trades below analyst targets after a sharp short term rebound, while revenue and earnings trends look more muted. Is that discount signalling opportunity, or is the market simply pricing in a cautious outlook?
Most Popular Narrative: 18% Undervalued
Fresnillo’s last close at £26.38 sits below the analyst consensus Narrative fair value of about £32.25, which is framed using an 11.53% discount rate and long term production and earnings forecasts in the analyst consensus Narrative on Simply Wall St.
Planned development of Guanajuato Sur as a large underground silver operation with projected output of 15 to 17 million ounces of silver per year and capex of about US$700 million to US$900 million provides a long life project that could underpin future group revenue and cash generation once in production.
See why 30 investors see Fresnillo as 18% undervalued.
Result: Fair Value of £32.25 (UNDERVALUED)
Still, Fresnillo’s substantial US$3b growth capital expenditure plan, together with rising cost pressures in Mexico, could squeeze cash generation and test that undervalued narrative.
Find out about the key risks to this Fresnillo narrative.
Another View: Fresnillo Through A Cash Flow Lens
The analyst narrative frames Fresnillo as about 18% undervalued around £32.25 per share. Our DCF model tells a different story. On that approach, the estimated future cash flow value is about £13.89 per share, which implies the current £26.38 price is expensive on this metric. Which lens feels more realistic to you: a long range production story, or the cash in and out that can be mapped today?
Look into how the SWS DCF model arrives at its fair value.
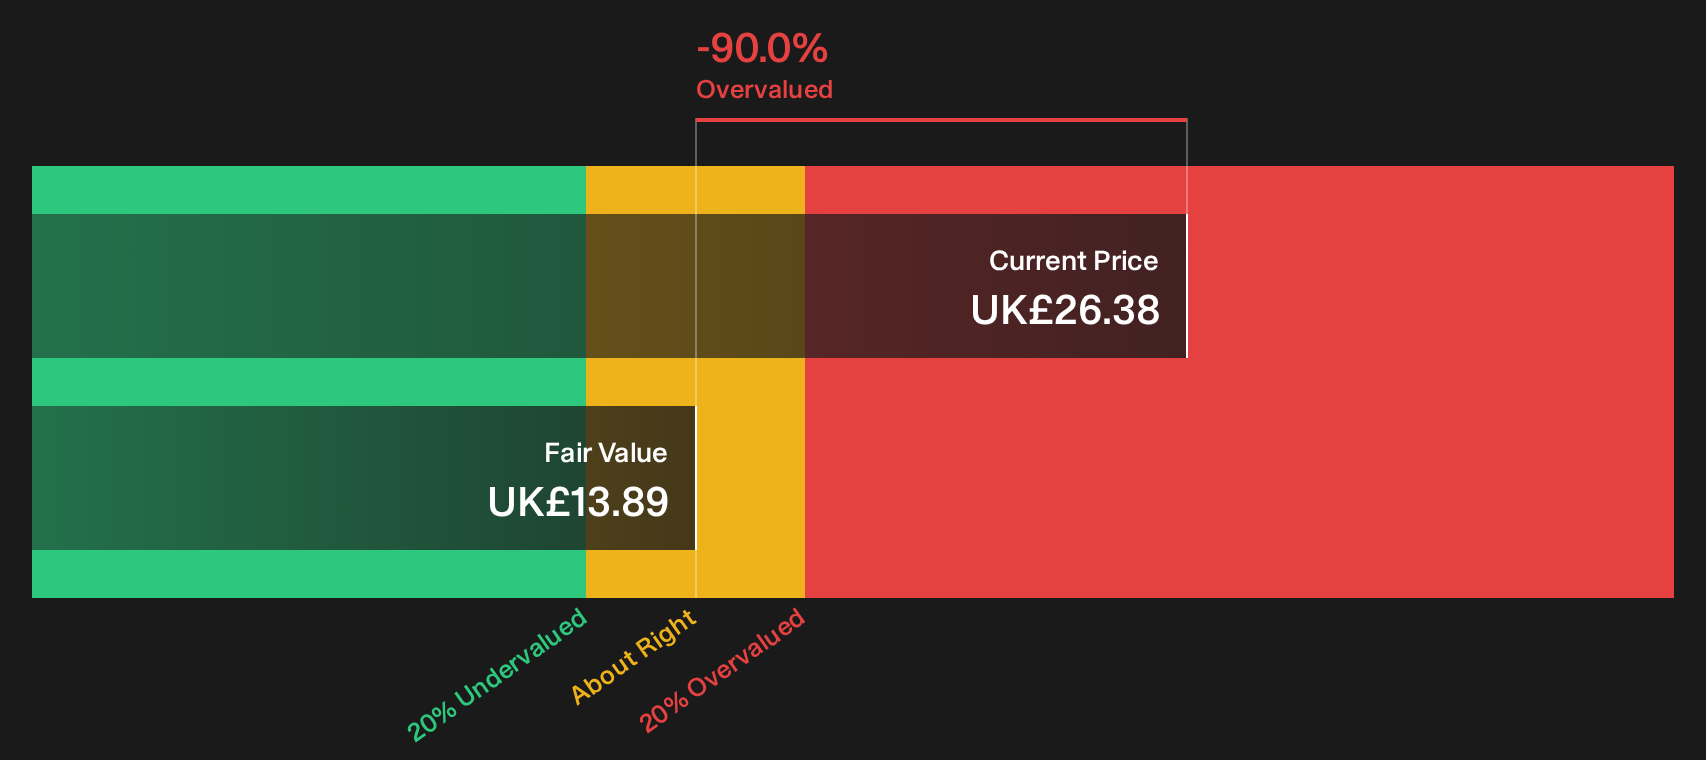
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fresnillo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicting stories around Fresnillo’s value and risk profile are already on the table. Use the data, timelines and risk flags to pressure test your own stance, then weigh up the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Fresnillo?
If Fresnillo has sharpened your focus on opportunities, use that momentum. A wider watchlist now can mean fewer regrets when the next move arrives.
- Target potential mispricing by scanning a curated 16 high quality undervalued stocks that filters for quality companies trading below their assessed worth and backed by solid fundamentals.
- Prioritise durability and support more consistent sleep by checking a 4 resilient stocks with low risk scores that highlights businesses with more resilient balance sheets and lower risk scores.
- Spot potential future leaders early by running through a 5 high quality undiscovered gems that focuses on strong fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com