


EN
Learn Why The Bull Case For Greenbrier Companies Stock Could Change Following Annual Earnings Decline
- Greenbrier Companies reported full year 2026 revenue of US$2,461.1 million and net income of US$79 million, with basic EPS from continuing operations of US$2.55.
- The extent of the revenue and earnings decline against the prior year highlights pressure on Greenbrier Companies’ profitability at its current scale of operations.
- We will examine how Greenbrier Companies’ investment narrative is reshaped by this sharp drop in annual earnings and revenue performance.
Scan beyond Greenbrier Companies and pressure-tested freight manufacturers by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) to see how other operators handle earnings resets.
Greenbrier Companies Investment Narrative Recap
To own Greenbrier Companies, you need to believe this railcar maker can convert a cyclical, capital heavy manufacturing base into steadier earnings through its leasing and management arm. According to LunaRodas, an investor in the Simply Wall St Community, the recurring revenue buildout is already progressing, which matters now that profit margins have compressed and interest costs weigh more heavily on earnings.
The latest results, with revenue and net income below last year and basic EPS at US$2.55, put near term focus on execution against the new guidance ranges and on cash generation. The key short term risk is that thinner margins and interest coverage pressure limit flexibility just as the firm is trying to hit its recurring revenue and operating margin targets.
The appointment of Emanuel Pearlman to Greenbrier Companies’ board and audit committee is the clearest development to watch around governance and financial discipline. Pearlman brings more than 35 years of experience in investment management, restructuring and complex capital structures, which ties directly into the questions now hanging over Greenbrier’s earnings quality and interest coverage.
LunaRodas highlighted management’s changing disclosure around margins and deliveries, and that makes an experienced audit committee voice more relevant. If Pearlman helps sharpen focus on returns, capital allocation and balance sheet risk, that could affect how the market treats Greenbrier’s P/E, dividend sustainability and the credibility of its new guidance metrics over the next few years.
LunaRodas anchors a fair value of US$32.95 for Greenbrier Companies primarily on the view that recurring revenue progress and the shift toward leasing economics better reflect the business Greenbrier is becoming, rather than the one described by near term delivery and margin noise.
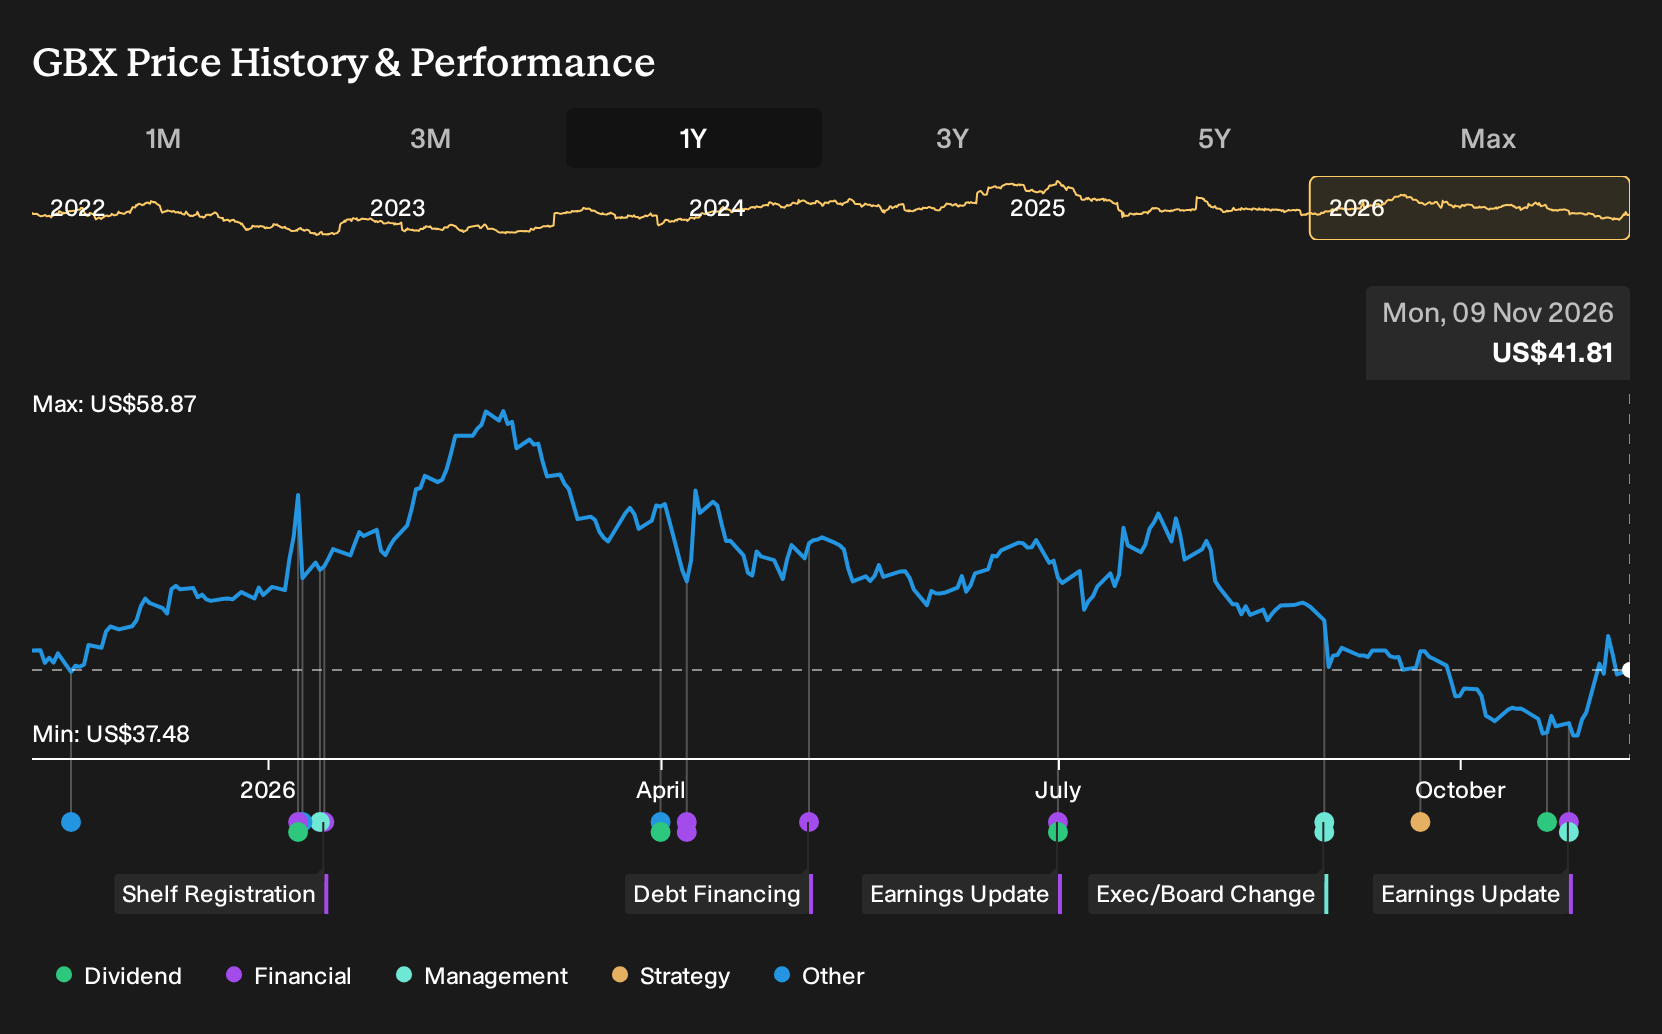
Discover why Greenbrier Companies' fair value indicates a 21% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Greenbrier Companies, the bearish twist is tariff risk. The lowest analysts were already cautious, working off pre announcement assumptions of roughly US$2.5b revenue and core EPS near US$2.60, and they saw tariff uncertainty choking tank car demand. Their narrative is materially more pessimistic and could shift again once this latest earnings reset is fully absorbed.
Explore 2 other Greenbrier Companies fair value estimates, including one that suggests as much as 97% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Greenbrier Companies research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Greenbrier Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Greenbrier Companies' overall financial health at a glance.
Looking for more investment ideas beyond Greenbrier Companies?
If Greenbrier Companies has sharpened your thinking about risk, income and balance sheet strength, use that momentum to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital preservation sits high on your list, start with a basket of 31 resilient stocks with low risk scores that may better match your comfort with volatility.
- For investors hunting for value, compare Greenbrier Companies with 40 high quality undervalued stocks that pair solid fundamentals with prices that look compressed on key metrics.
- If you want exposure to lesser known stories, broaden your watchlist with 19 high quality undiscovered gems that combine quality signals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com