


EN
Nebius Group (NBIS) Draws Fresh Scrutiny Over AI Data Center Permits
- Nebius Group (NasdaqGS:NBIS) faces rising scrutiny over its AI data center buildout after election driven regulatory shifts in key jurisdictions.
- Regulators and local authorities are reviewing operational permits for several Nebius AI facilities, with some approvals still pending as of early November 2026.
- Market commentators and industry analysts have publicly questioned whether unresolved permitting issues could affect the timing of Nebius Group's next phase of AI infrastructure expansion.
- The growing focus on election related regulatory changes and AI data center permit gaps is only one part of the Nebius Group story. Our analysis turns up 2 other big wins for Nebius Group as well.
For a broader view on how AI buildout pressures, regulation, and funding conditions intersect across the sector, explore 53 AI infrastructure stocks.
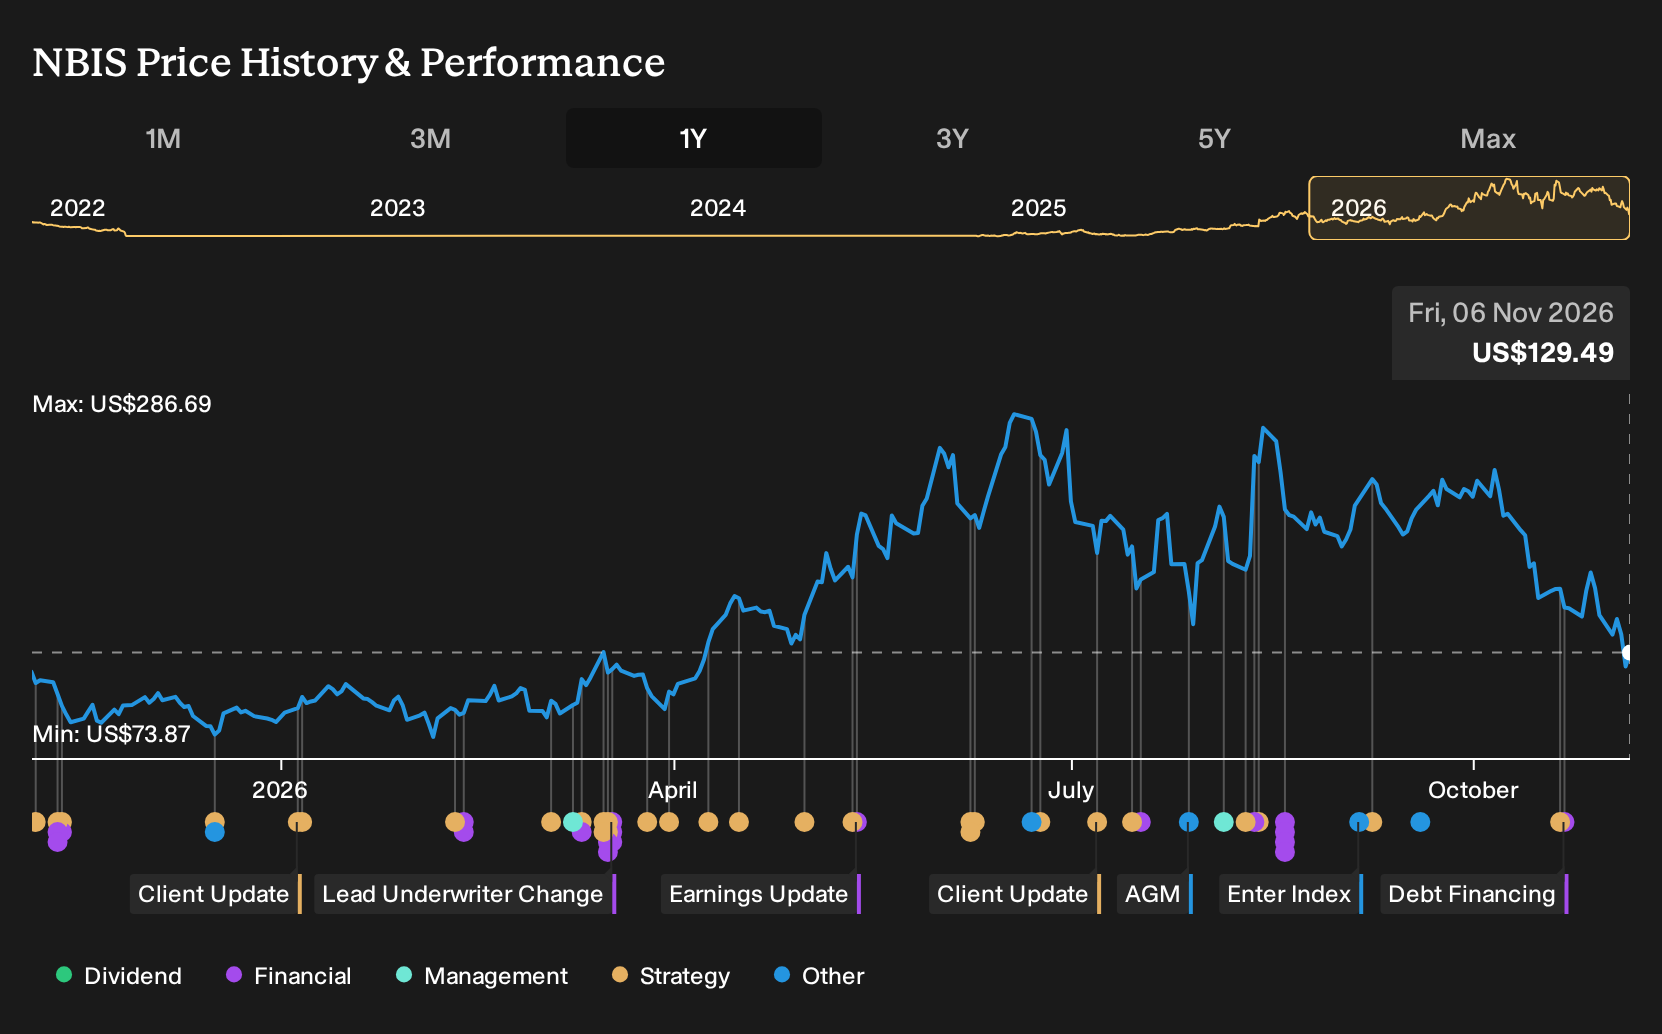
Nebius Group builds full stack infrastructure to support AI workloads across the US, the UK, and other international markets, so any scrutiny of its data center footprint goes straight to the core of how it delivers those services. With a market cap of $35.5b, it operates at a scale where regulatory outcomes around power, permits, and regional approvals can shape how quickly its AI facilities come online.
See how Nebius Group's balance sheet measures up.
Regulatory friction tests how much Nebius Group can really scale its AI buildout
The Nebius Group Narrative asks investors to back a capital-heavy AI cloud platform on the assumption that it can keep ramping capacity while holding pricing and margins together, even as competitors like CoreWeave and the big hyperscalers push hard. Fresh scrutiny of permits and election driven rule changes goes straight at that bet.
"As Nebius Group aggressively expands data center capacity and pursues greenfield builds to support future growth, heightened regulatory scrutiny regarding data sovereignty and localization, especially in core markets such as the U.S., Europe, and Israel, may significantly increase compliance costs and limit expansion potential..."
See how the full story points towards a $281 fair value for Nebius Group.
This round of permit reviews does not invent a new problem for Nebius Group. It reinforces an existing fault line in the story that analysts already tied to heavier regulation and environmental rules. The more permitting gets tied to politics, the greater the chance that capital spending runs ahead of what can legally be switched on and monetised.
At the same time, the business is still framed as having strong funding, multi region expansion plans and partnerships with Nvidia and others, so the Narrative leaves room to offset a tougher US stance with progress in Europe or Israel. The real financial hit would come if tighter rules start to limit connected power across several regions at once, which would squeeze the high growth forecasts and make already thin 3.1% margins work harder.
For anyone tracking Nebius Group, this regulatory news only really matters in the context of which version of the investment story you believe, because it either confirms a core risk or looks like a manageable cost of doing AI at scale.
The Nebius Group question the headlines skip
AI capacity, permits, and margins grab attention, yet the quieter issue is who actually steers Nebius Group and what incentives shape their decisions. See who is actually steering Nebius Group, and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com