


EN
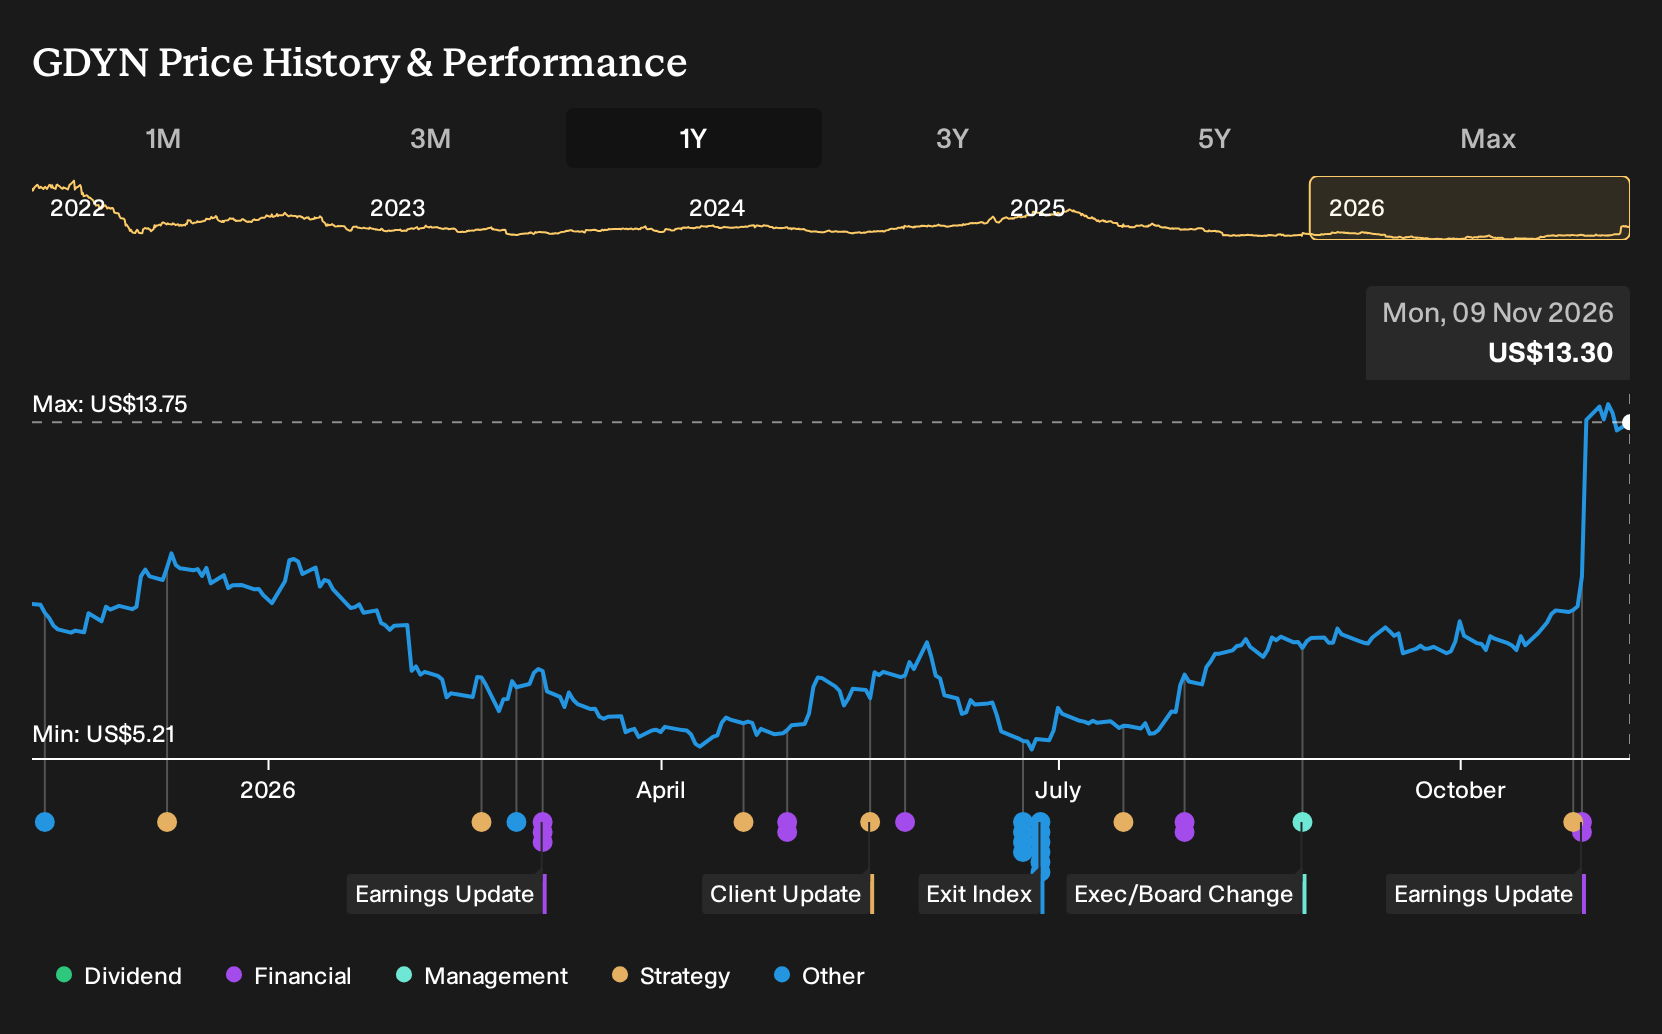
How Earnings And New AI Consulting At Grid Dynamics Holdings (GDYN) Has Changed Its Investment Story
- Grid Dynamics Holdings reported third quarter 2026 sales of US$114.29 million and net income of US$6.16 million, alongside the launch of a Business Process Consulting practice aimed at full lifecycle enterprise AI transformation.
- The new consulting arm ties AI engineering with process redesign and change management, which directly targets higher value, outcome focused work with large enterprises already turning to Grid Dynamics Holdings for AI led projects.
- This article examines how Grid Dynamics Holdings' stronger quarterly profitability and new AI consulting practice may be reshaping its broader investment narrative.
Grid Dynamics Holdings Investment Narrative Recap
To own Grid Dynamics Holdings, you need to believe that enterprise clients keep leaning on its AI led services, including higher value, outcome based work, even as automation tools evolve. The latest quarter shows higher quarterly revenue and net income, which supports that operating thesis in the short run but does not fully resolve pressure on net margins over the past year.
The analyst consensus Narrative on Simply Wall St still hinges on AI related projects scaling faster than any drag from customer concentration or FX swings. Third quarter earnings and fourth quarter revenue guidance in the US$113.5 million to US$115.5 million range keep execution risk very real if a large client delays work or budgets reset.
The launch of Grid Dynamics Holdings' Business Process Consulting practice is the most relevant operational update here because it connects existing AI engineering to process redesign and change management. That offers a clearer route from projects to measurable business outcomes at Fortune 1000 customers, which is exactly where the current AI revenue mix already skews.
This move also cuts directly across the biggest catalysts flagged in the analyst consensus Narrative on Simply Wall St, particularly the push toward higher value AI programs and operating leverage. Execution risk stays elevated though, since success depends on scaling a consulting motion while managing customer concentration, FX exposure, and the possibility that automated tools compress demand for human led services.
Grid Dynamics Holdings' current earnings sit at US$2.9 million, with analysts forecasting US$26.4 million of earnings on US$541.2 million of revenue by 2029. This implies revenue growth of 8.6% per year and an earnings increase of roughly 9x from today's level.
Uncover how Grid Dynamics Holdings' fair value indicates a 29% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
Some of the most optimistic analysts frame Grid Dynamics Holdings as a vendor consolidation winner, not just an AI contractor. Before this earnings print and the Business Process Consulting launch, the bullish camp was modeling revenue rising about 11.3% a year and earnings reaching roughly US$42.0 million by 2029. That is far ahead of consensus forecasts near US$541.2 million in sales and US$26.4 million in profit. If you buy into that more upbeat story, the latest profitability and new consulting arm might eventually support it. If you are more cautious, this split in expectations is a useful reminder to compare several narratives before deciding how the fresh numbers and guidance could reshape your own view.
Explore 3 other Grid Dynamics Holdings fair value estimates, including one that suggests the potential for as much as 13% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grid Dynamics Holdings research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Grid Dynamics Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grid Dynamics Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Grid Dynamics Holdings?
If the Grid Dynamics Holdings story has you thinking about where else strong execution and clear financials might show up, the Simply Wall St Screener can help you quickly filter for stocks that match your own risk and return preferences.
- If downside protection matters most to you, start with companies that score well on resilience and financial risk using our 31 resilient stocks with low risk scores.
- For readers who want balance sheets that can support reinvestment and shocks, filter for businesses with strong cash and low leverage through the list of solid balance sheet and fundamentals (25 results).
- When you want to uncover less crowded ideas with healthy fundamentals, cast a wider net across our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com