


EN
What Target Hospitality Stock's Q3 Revenue Growth And Wider Losses Mean For Shareholders
- Target Hospitality reported third quarter 2026 results, with quarterly revenue of US$129.06 million and a net loss of US$9.21 million, as well as nine-month revenue of US$287.3 million and a loss of US$31.16 million.
- The business is showing a larger sales base across both the quarter and year to date, while losses and loss per share from continuing operations have also widened. This raises questions about how current spending and contract mix are affecting profitability.
- We will now look at how Target Hospitality's higher revenue but wider net loss shapes the investment narrative around its WHS pivot.
Compare Target Hospitality's widening losses and contract driven WHS story with other operators by scanning the list of solid balance sheet and fundamentals (25 results) that may handle growth with tighter financial control.
Target Hospitality Investment Narrative Recap
To own Target Hospitality, you need to believe the Workforce Housing Solutions pivot can turn today’s larger revenue base into a more durable profit engine. The latest quarter keeps that story intact but does not settle it. Higher quarterly and year to date revenue alongside wider losses show the build out phase is still affecting earnings.
The key short term swing factor is how quickly new WHS communities tied to long term contracts contribute enough margin to offset transitional costs. The biggest risk remains heavy capital spending and a growing loss profile if contracted beds, pricing and utilization do not line up with the expanded asset base.
The third quarter 2026 earnings release is the update that matters for this catalyst thread. Revenue for the quarter reached US$129.06 million, with sales of US$64.86 million, while the business reported a net loss of US$9.21 million and a basic loss per share from continuing operations of US$0.09.
Over the first nine months of 2026, Target Hospitality recorded revenue of US$287.3 million and a loss of US$31.16 million, with a basic loss per share from continuing operations of US$0.31. For investors weighing the analyst consensus Narrative on Simply Wall St about WHS driven earnings improvement, these figures keep execution risk and balance sheet discipline firmly in focus.
Target Hospitality's narrative projects US$1.1b revenue and US$222.6 million earnings by 2029. This implies 47.0% yearly revenue growth and an earnings improvement of about US$260 million from current earnings of US$37.7 million in losses.
Uncover why Target Hospitality's fair value indicates a 122% potential upside to its current price, which could close faster than expected.
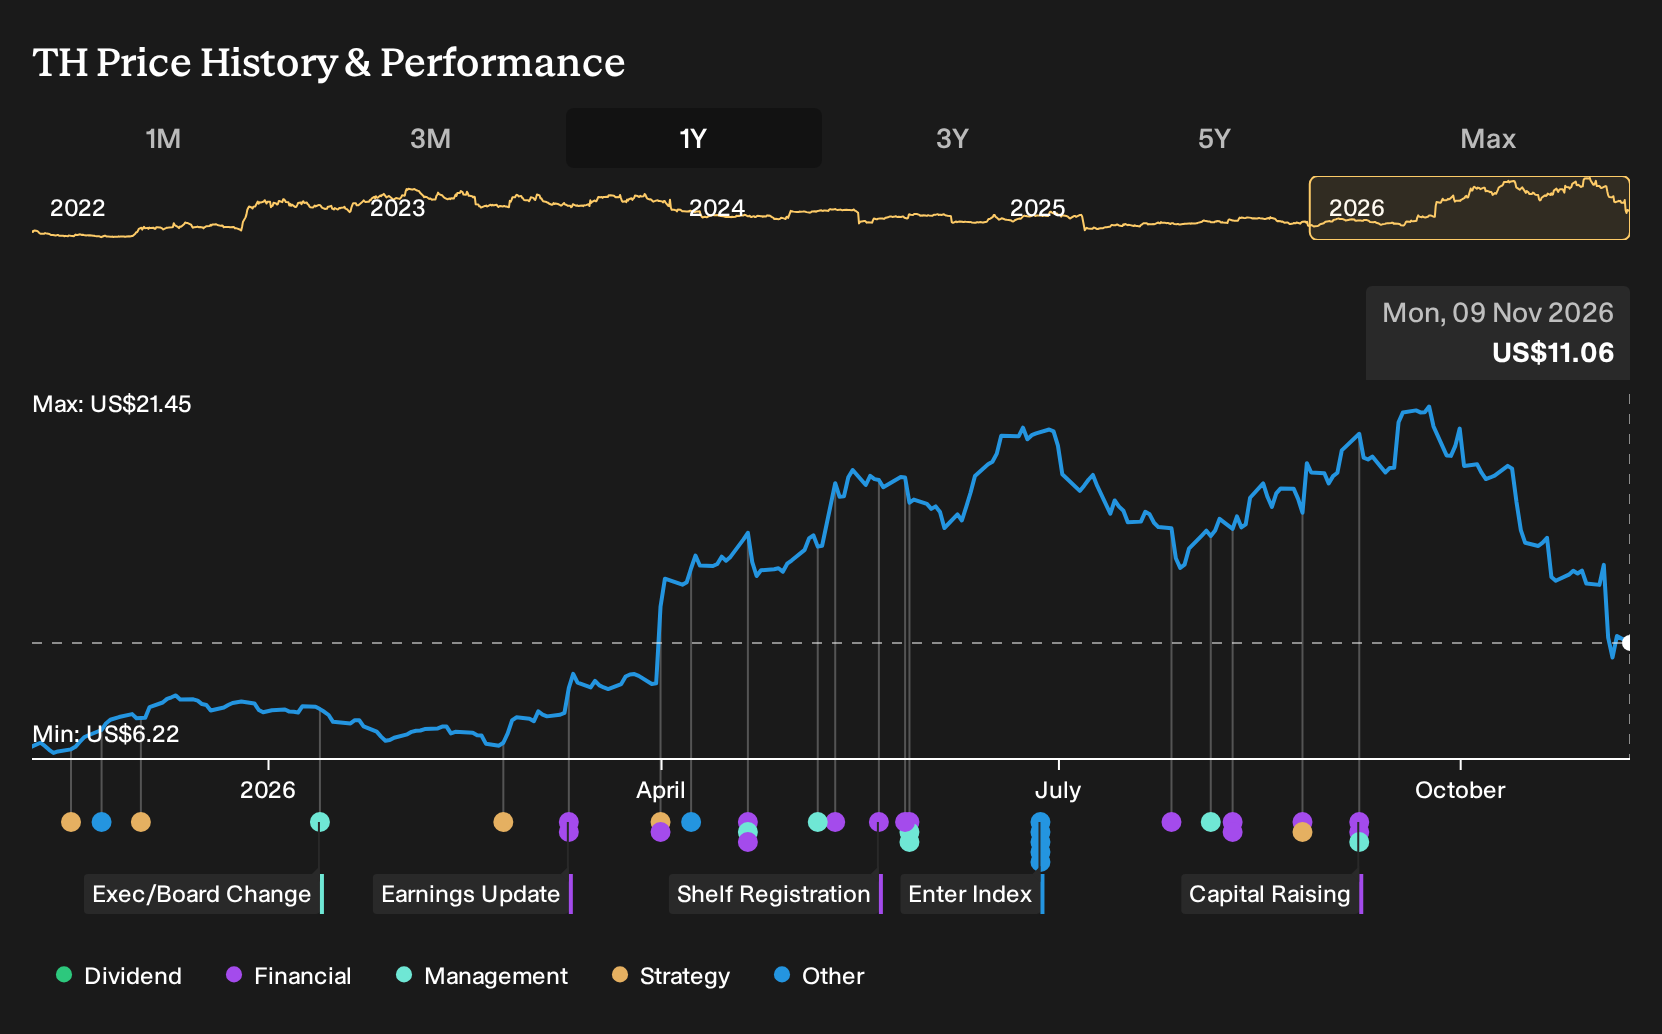
Exploring Other Perspectives
One alternate view puts the WHS contract backlog front and center. Bullish analysts were expecting Target Hospitality to reach about US$1.2b revenue and US$271.5 million earnings by 2029, which is far more optimistic than the baseline. Those projections were set before this earnings release, so you should expect opinions to shift and compare several angles yourself.
Explore another Target Hospitality fair value estimate, including one that suggests potential upside of as much as 133% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Target Hospitality research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Target Hospitality. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Target Hospitality's overall financial health at a glance.
Looking For More Investment Ideas Beyond Target Hospitality?
If the Target Hospitality story has you thinking about position sizing, risk and balance sheet strength, it can help to widen the lens and review other companies through the Simply Wall St Screener before making any moves.
- For readers who want businesses that combine financial resilience with cleaner accounts, start with the list of solid balance sheet and fundamentals (25 results) and compare those balance sheets to what you see at Target Hospitality.
- If value is your priority and you prefer situations where quality fundamentals meet potentially attractive pricing, scan the 40 high quality undervalued stocks and pressure test which candidates line up with your return objectives.
- Income focused investors who like to see cash coming back regularly can review the 7 dividend fortresses and weigh those payout profiles against the reinvestment story at Target Hospitality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com