


EN
Pets At Home Group (LSE:PETS) Could Be 17% Above Fair Value On New Insurance Push
Pets at Home Group (LSE:PETS) has launched a new multi tier pet insurance product while recently reporting slightly lower revenue and net income, leaving investors weighing fresh insurance ambitions against ongoing operational pressures.
Recent trading has leaned positive for Pets at Home Group, with a 1-day share price return of 2.76% and a 30-day share price return of 26.75% helping drive a 37.40% year to date gain. The 5-year total shareholder return of a 29.86% decline shows that the longer term picture has been weaker even as shorter term momentum has picked up on expectations around the vet division, retail recovery and the new insurance offering.
Compare Pets at Home Group's recent momentum with a curated set of other potential breakouts by scanning the 16 high quality undervalued stocks that also pair solid fundamentals with current pricing gaps.
Pets at Home Group now looks like a solid pet care platform whose share price has sprinted ahead. The real work starts in asking whether that recent surge still leaves enough value on the table.
Most Popular Narrative: 17% Overvalued
The analyst consensus Narrative on Simply Wall St places Pets at Home Group's fair value at about £2.29 per share. This sits below the last close of £2.68, so the current quote already leans ahead of that model.
With accessories and other ranges supported by improving retail trading trends, including Q4 volume growth above 5% and a return to positive sales growth, there is room for Pets at Home Group to convert better product mix and digital integration into higher retail revenue and contribution to earnings.
See why 58 investors see Pets at Home Group as 17% overvalued.
Result: Fair Value of £2.29 (OVERVALUED)
Still, a weak UK pet care market and past retail margin pressure, including the 60% drop in retail profit to £31m, could quickly puncture that upbeat Pets at Home Group narrative.
Find out about the key risks to this Pets at Home Group narrative.
Another View: Cash Flows Paint Pets at Home Group Differently
While analyst targets suggest Pets at Home Group looks about 17% overvalued at £2.29 per share, the SWS DCF model points in the opposite direction. On that framework, PETS at £2.68 trades below an estimated future cash flow value of £3.78, which implies an undervalued setup.
This gap between earnings based pricing and cash flow modelling leaves investors with a simple question. Which yardstick do you trust when the story on valuation risk is pulling in two directions?
Our DCF model is only as useful as the assumptions behind it, so it is worth seeing exactly how those cash flows are built and discounted in the SWS DCF model before leaning on it for a call. Look into how the SWS DCF model arrives at its fair value.
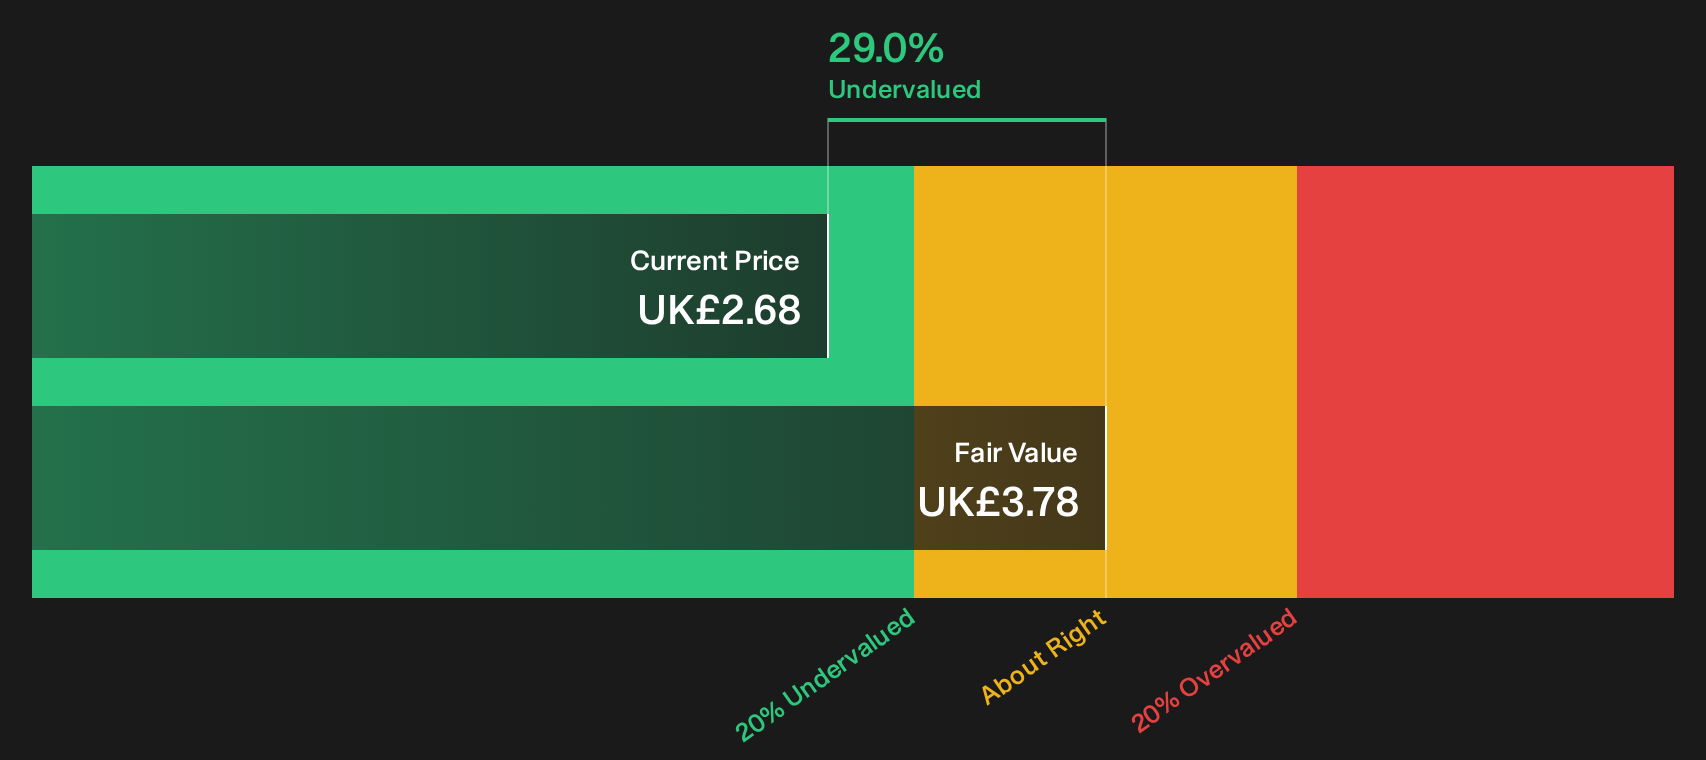
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pets at Home Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation usually split opinion. If you feel Pets at Home Group’s story is moving fast, check the underlying data now and weigh both sides of the argument using 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Pets at Home Group?
Do not stop your research with a single stock. Broaden your watchlist now and give yourself more options before the next wave of opportunities moves without you.
- Target potential mispricings by scanning companies that pair strong fundamentals with pricing gaps through the 16 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (9 results) so you can focus on businesses with sturdier financial foundations.
- Hunt for underfollowed opportunities by checking a curated pool of 5 high quality undiscovered gems that may not yet be on most investors' radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com