


EN
How Investors Are Reacting To Hitachi Construction Machinery Shares (TSE:6305) New Earnings Guidance
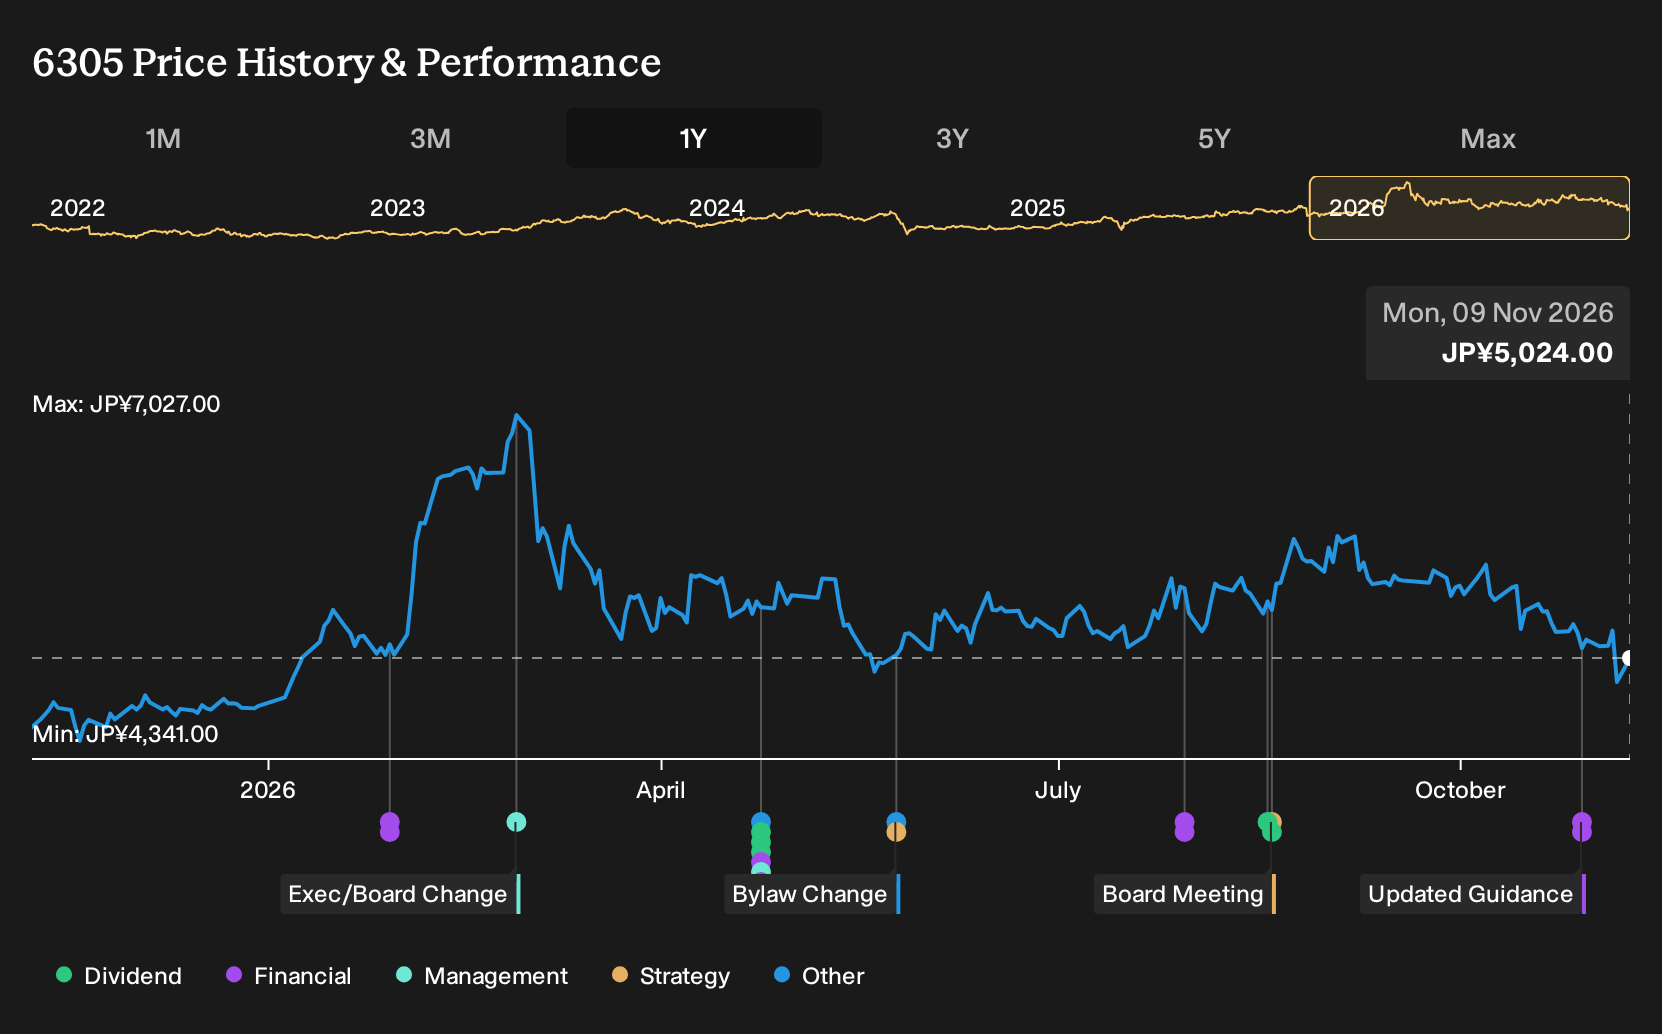
- Hitachi Construction Machinery reported half year results for the period ended September 30, 2026, with sales of JPY 698,076 million and net income of JPY 49,684 million, and issued new full year guidance targeting revenue of JPY 1,500,000 million and net income attributable to owners of the parent of JPY 90,000 million.
- The combination of higher half year earnings per share compared with a year earlier and fresh full year forecasts provides investors with clearer visibility into Hitachi Construction Machinery's current operating momentum and profit expectations.
- The next area of focus is how Hitachi Construction Machinery's stronger half year profitability might influence the broader investment narrative around the business.
Scan how Hitachi Construction Machinery's latest guidance compares with peers by reviewing a curated set of list of solid balance sheet and fundamentals (23 results) in similar capital intensive sectors.
What Is Hitachi Construction Machinery's Investment Narrative?
To stay invested in Hitachi Construction Machinery, you need to believe that a capital intensive, cyclical equipment maker can keep turning a large installed base and global footprint into resilient cash generation. The latest half year results and the new full year targets give a clearer read on current execution, from demand for excavators and mining trucks to how effectively the group is pricing and controlling costs. With earnings forecasts already pointing to moderate profit growth, this guidance anchors the near term story in concrete numbers rather than hope.
The key short term swing factors are still equipment order trends, utilization and service uptake, and how confidently management continues to deploy balance sheet capacity into capex and support for customers. Recent guidance, set against a share price that has fallen roughly 9% over three months, may influence how you weigh decent P/E headline value against slower forecast revenue growth and a patchy dividend history. The risk reward looks tighter if those forecasts meet heavier competition or weaker pricing power.
That said, there is a less comfortable angle to this story once you put Hitachi Construction Machinery's funding mix and capital needs side by side with ...
There's only one way to know the right time to buy, sell or hold Hitachi Construction Machinery. Head to Simply Wall St's company report for the latest analysis of Hitachi Construction Machinery's Fair Value.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster between ¥4,183.60 and ¥6,173.33, which already shows how far opinions on Hitachi Construction Machinery can stretch. These views pre date the October 29 guidance, so treat them as a starting point and explore more community perspectives before anchoring expectations.
Explore another Hitachi Construction Machinery fair value estimate, including one that suggests there may be as much as 23% upside from the current price!
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hitachi Construction Machinery research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hitachi Construction Machinery. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hitachi Construction Machinery's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hitachi Construction Machinery?
If this review of Hitachi Construction Machinery has sharpened your thinking, broaden your watchlist by scanning other companies that may better suit your risk profile, income needs, or valuation preferences using the Simply Wall St Screener.
- For investors who want potential mispricing on their side, focus on quality at a reasonable tag through 22 high quality undervalued stocks which already combines fundamentals with more attractive market expectations.
- If capital preservation and smoother portfolio swings matter most to you, concentrate on businesses screened for resilience and financial robustness via 18 resilient stocks with low risk scores which already clears a stricter risk filter.
- Those hunting for future compounders with less crowd attention can comb through 76 high quality undiscovered gems where stronger balance sheets and fundamentals have not yet drawn as much focus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com