


EN
Learn Why The Bull Case For Williams Sonoma Stock Could Change Following AI Tool Rollout
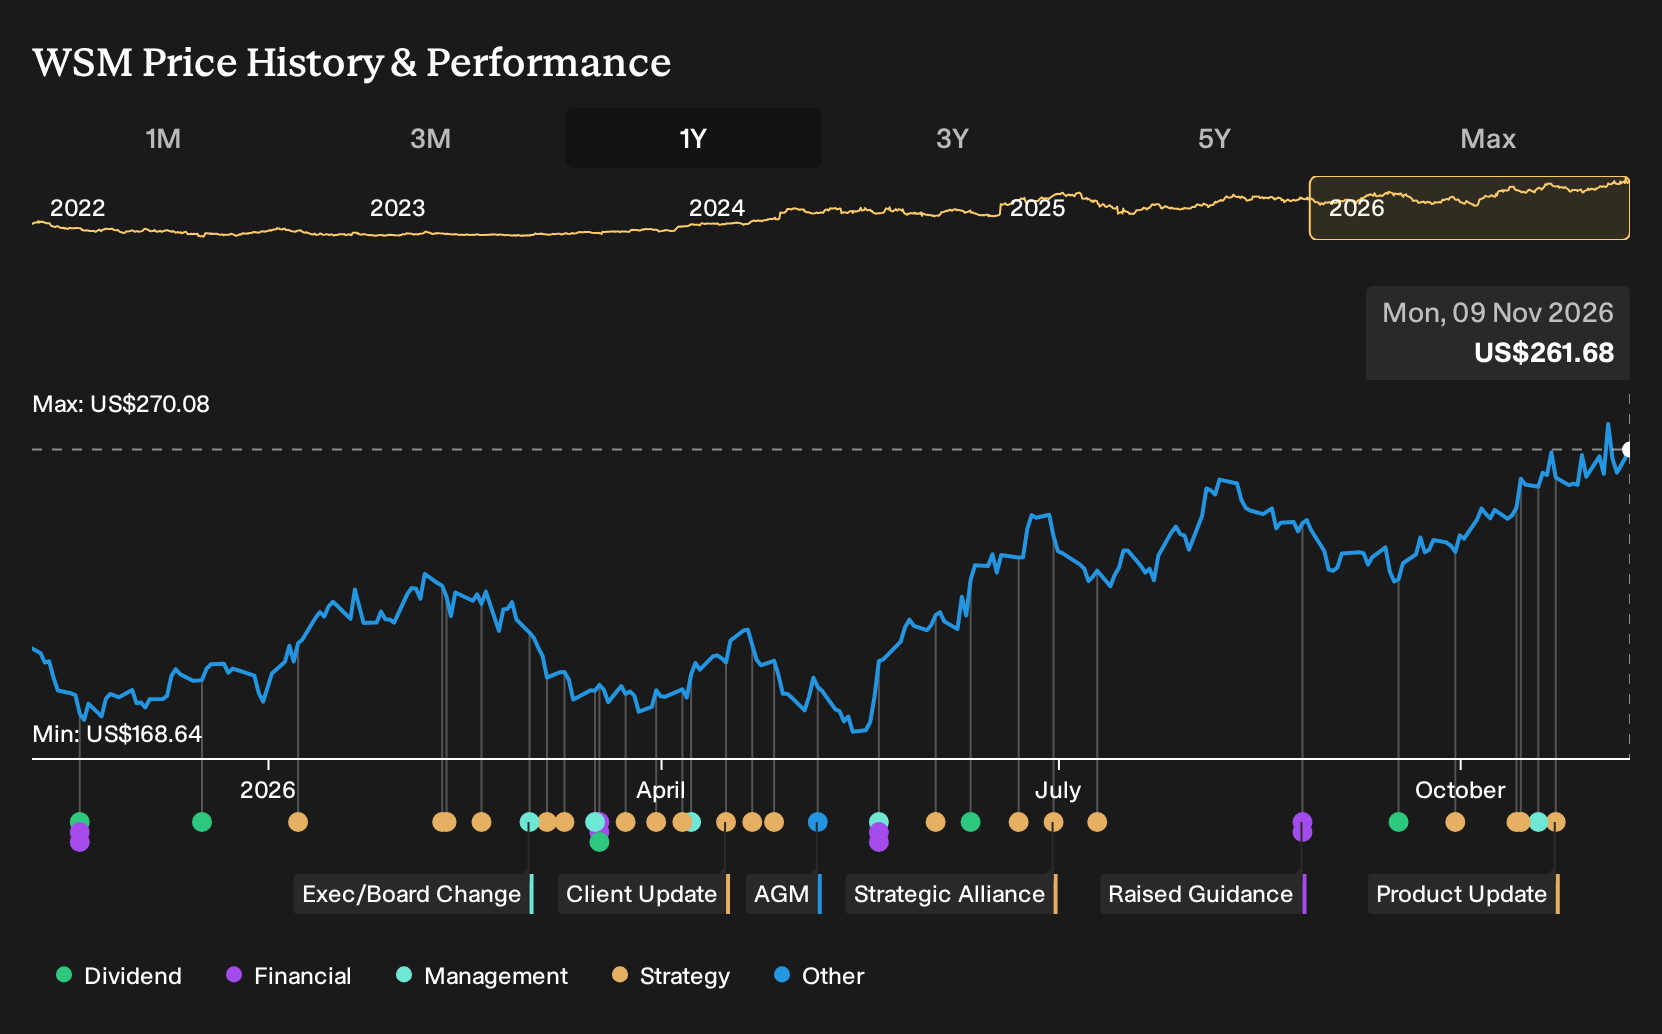
- Williams-Sonoma recently attracted renewed attention as investors reassessed its fundamentals, with analysts indicating the shares trade slightly above their estimated fair value.
- The company’s continued push into AI powered tools like Olive and Otto, which materially lift online engagement and conversion, has become a focal point for how its digital model might support margins.
- We will now explore how Williams-Sonoma’s investment narrative could evolve as its AI driven digital platforms become more central to execution.
Scan Williams-Sonoma’s AI story against a curated peer set by reviewing 53 AI infrastructure stocks that could also see sentiment shift as digital engagement tools gain traction.
Williams-Sonoma Investment Narrative Recap
To own Williams-Sonoma, you need to buy into a simple idea. The retailer keeps translating its omni-channel footprint and tools like Olive and Otto into higher quality traffic, better conversion and resilient margins, even while the broader housing market looks sluggish. The recent share price move does not materially change that operational story in the near term.
The key short term catalyst still lies in how effectively those AI driven experiences support digital revenue and protect operating margin as tariffs and fuel costs weigh on merchandise economics. The biggest risk sits on the other side of that equation. Prolonged housing softness or renewed freight pressure could cap comparable sales and squeeze earnings.
Recent commentary highlighted how customers who use Williams-Sonoma’s AI powered tools convert at about 3x the rate of others and personalized visits generate roughly 9x the revenue of an average visit, according to the analyst consensus Narrative on Simply Wall St. That is directly relevant to today’s focus on whether the stock’s premium P/E is backed by a defensible digital model.
If those engagement metrics hold up as the firm leans further into e commerce, B2B and emerging brands, they become a practical catalyst to watch around each results update. Any sign that tariffs, fuel costs or operational controls start to offset those digital gains, or that AI tools lose effectiveness, would quickly move back to the foreground for Williams-Sonoma shareholders.
Analysts project Williams-Sonoma's narrative toward about US$9.4b in revenue and US$1.3b in earnings by 2029. This outlook embeds 5.4% yearly revenue growth and an earnings increase of roughly US$100m from about US$1.2b today.
Uncover why Williams-Sonoma's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view puts Williams-Sonoma’s tariff risk front and center. The most cautious analysts worried that higher trade and fuel costs could outpace AI driven gains, even while still modeling roughly US$9.3b of revenue and US$1.3b of earnings by 2029. That is a more muted story, and today’s AI focused news could eventually reshape it.
Explore another Williams-Sonoma fair value estimate, including one that suggests it could be worth just $246.35.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Williams-Sonoma research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Williams-Sonoma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams-Sonoma's overall financial health at a glance.
Looking for more investment ideas beyond Williams-Sonoma?
Once you have a view on Williams-Sonoma, it can help to compare it with other opportunities that match your risk level, income needs and return goals. The Simply Wall St Screener lets you quickly filter the market into focused shortlists so you can spend time on analysis, not on raw data gathering.
- If capital preservation is front of mind, start with companies that score well on resilience by reviewing 31 resilient stocks with low risk scores that could align better with a cautious approach.
- For investors hunting for quality at a reasonable entry point, scan a curated group of potentially mispriced opportunities through the 40 high quality undervalued stocks and see which ones deserve a closer look.
- Income focused readers who care about regular cash returns can weigh up a focused universe of higher yield opportunities by checking out the 7 dividend fortresses that might fit a dividend led playbook.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com