


EN
CFO Departure Could Be A Big Test For Severn Trent Stock (LSE:SVT)
- Severn Trent reported that Chief Financial Officer and Executive Director Helen Miles has informed the Board she will step down over a 12 month notice period to become CFO at Vistry, with a formal process underway to identify her successor.
- The departure of a long standing CFO who is closely involved in Severn Trent's large AMP8 investment, efficiency and ODI programmes raises questions about continuity in executing these complex regulatory and cost initiatives.
- We will now assess how Severn Trent's investment narrative could be affected by Helen Miles leaving the CFO role after a planned transition.
Scan how other regulated utilities handle leadership changes and capital plans by reviewing our hand picked 4 resilient stocks with low risk scores alongside Severn Trent's latest CFO transition.
Severn Trent Investment Narrative Recap
For Severn Trent, the core belief is that a £15b AMP8 plan, heavier environmental obligations and efficiency targets can be turned into regulated asset growth, Outcome Delivery Incentive rewards and cost savings. Helen Miles leaving does not change that investment agenda today, because she remains in post for up to 12 months to support the handover.
The near term swing factor is execution on AMP8 spending, the targeted £150m operating and £500m capital efficiencies and ODI performance, all under tight regulatory scrutiny. The biggest risk is that investigations or weaker customer outcomes lead to tougher Ofwat decisions that squeeze allowed returns and keep net margins under pressure.
The most relevant announcement here is the AMP8 investment and ODI framework described in the analyst consensus Narrative on Simply Wall St. That view highlights the plan to grow regulated capital value by about 60% to 2030 and to pursue at least £300m of ODI rewards across AMP8, backed by technology, in sourcing and renewable generation.
This backdrop is where a CFO transition matters most. Investors are watching whether Severn Trent maintains discipline on enhancement totex, delivers the planned efficiency gains and avoids repeat customer service penalties. Progress on AI enabled monitoring, energy self sufficiency and ODI outcomes will likely shape sentiment around execution more than the leadership change itself.
Severn Trent CFO Change Against Analyst Assumptions
Analyst expectations give useful context for Helen Miles leaving Severn Trent. Forecasts link the AMP8 spend and ODI targets to specific revenue, margin and valuation outcomes that investors can test against their own views on execution and regulatory risk.
On the top line, analysts are working with revenue growth of 9.3% a year over the next three years. Profit margins are expected to move from 13.1% today to 16.5% by around 2029, which implies that efficiency delivery and ODI rewards would show up not just in higher revenue but also in a thicker profit pool.
Earnings sit at £371.0m in the latest snapshot and are projected to reach £609.2m by about 2029, which is an increase of roughly £238m. That path assumes the share count stays broadly flat, so earnings per share at £2.03 in the forecast year line up with the absolute profit number rather than being diluted by fresh equity funding.
Valuation work in the consensus folds these operating inputs into a specific set of capital market assumptions. The current P/E multiple of 25.2x on today’s earnings is expected in the scenario to trend down to 20.0x on the 2029 profit figure, which still sits above the 18.4x level cited for the wider GB water utilities sector.
On those inputs, Severn Trent would reach around £3.7b of revenue and £609.2m of earnings by 2029, with analysts applying a discount rate of about 7.6% to translate that profile back into today’s value. That framework underpins the average price target of £32.57 and the view that the stock, at £30.94, is close to what the Street regards as fair for now, even as a new CFO steps in to oversee the AMP8 programme and funding mix.
Severn Trent's narrative projects £3.7b revenue and £609.2m earnings by 2029. This requires 9.3% yearly revenue growth and an earnings increase of about £238m from £371.0m today.
Uncover why Severn Trent's fair value is essentially aligned with its current price.
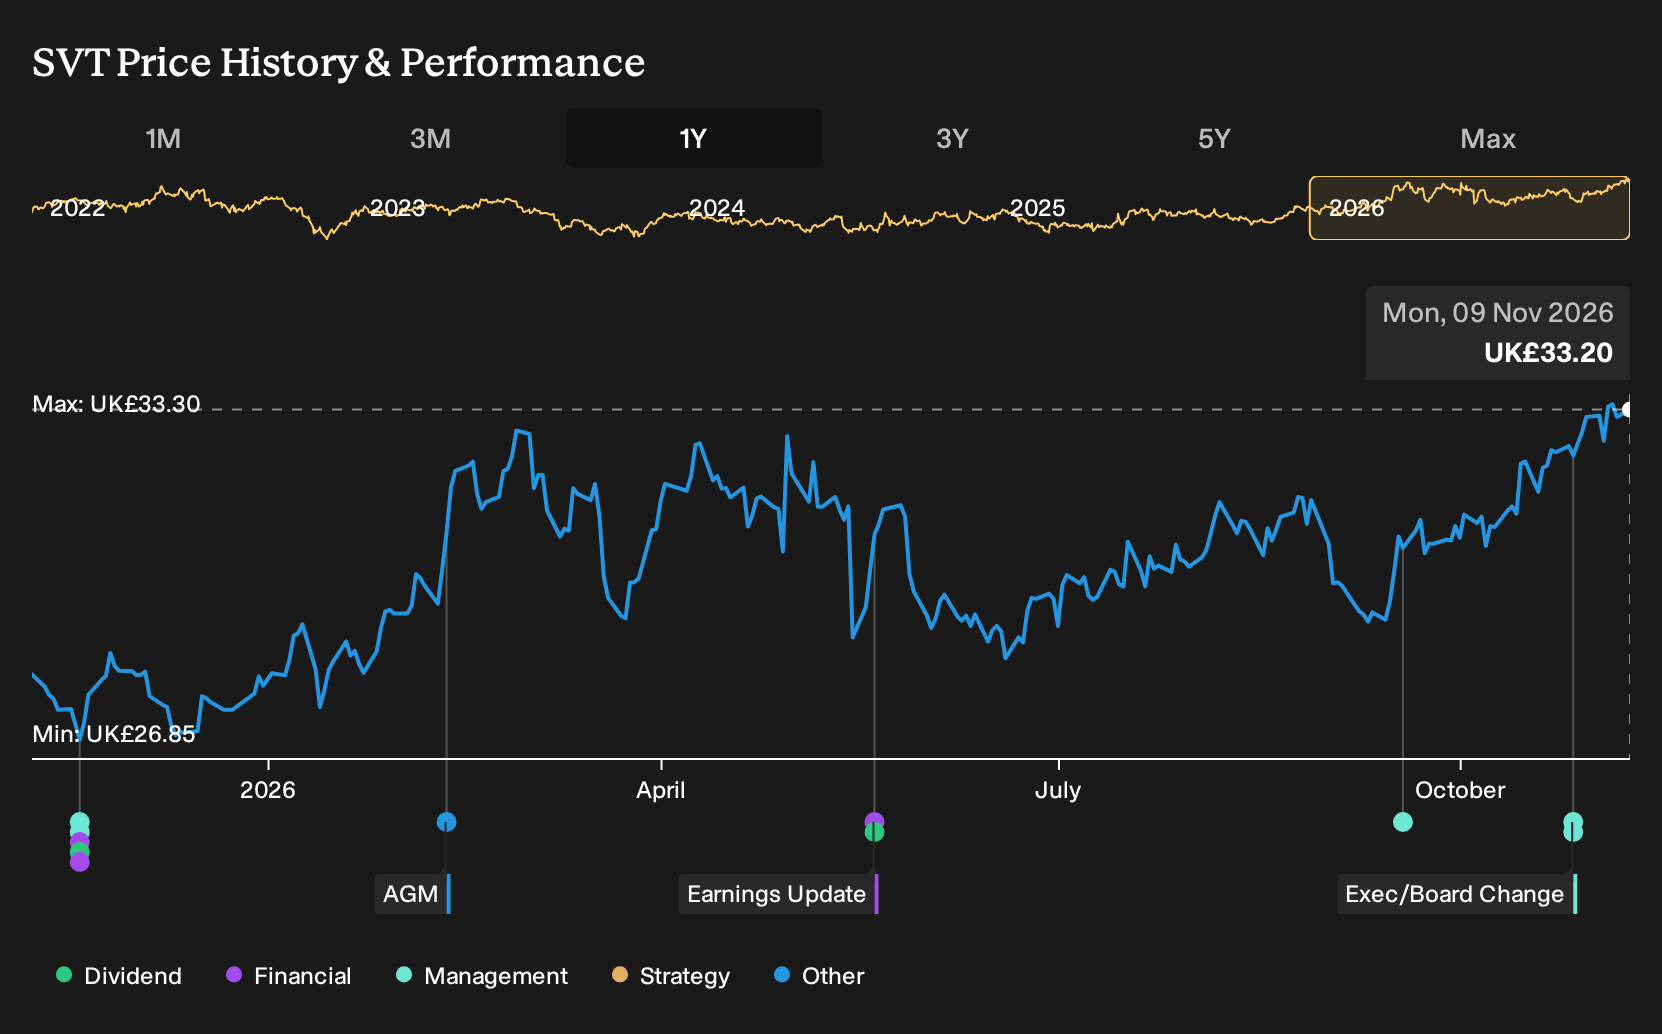
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span a wide range, from about £9.22 to £33.03, so opinion on Severn Trent is clearly split. Compare that spread with risks around ODI penalties, tighter Ofwat decisions and rising enhancement totex, then decide which assumptions you find more convincing.
Explore 2 other Severn Trent fair value estimates, including one that suggests it could be worth as much as £33.03.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Severn Trent research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Severn Trent. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Severn Trent's overall financial health at a glance.
Looking for more Severn Trent sized investment ideas?
If this Severn Trent review has sharpened your thinking and you want to widen the field, the Simply Wall St Screener can help you quickly surface other stocks that fit very different risk and reward profiles.
- If you care most about financial resilience and low volatility, start with a 4 resilient stocks with low risk scores so you can see which businesses score well on the Simply Wall St risk model.
- For investors hunting for quality at a sensible price, scan a 16 high quality undervalued stocks that blends solid fundamentals with potentially attractive valuations.
- If income is your priority, focus on return of cash by reviewing a set of 6 dividend fortresses that pair higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com