


EN
Australian Stock Market Today: ASX Futures Firm On Strong US Jobs And CPI Test
The Morning Bull - Australian Market Morning Update Tuesday, 10 Nov 2026
Australian shares look set to open firmer, with SPI futures pointing to a constructive tone. The single driver this morning is strong US jobs data that keeps global growth appetite alive and risk assets supported.
US non-farm payrolls showed a solid 165,000 job gain in October and the unemployment rate edged down to 4.1%. That combination signals resilient US demand and reinforces expectations that the Federal Reserve keeps policy firmly focused on containing inflation.
Stronger US hiring can pressure US yields higher, which tends to lift the US dollar and influence the Australian dollar and local funding costs. For Australian companies, that backdrop feeds directly into the outlook for interest expenses and the translation of offshore earnings.
The live question now is simple: Do upcoming US inflation figures validate this jobs-led growth story, or force investors to rethink how restrictive global rates need to stay from here?
Stocks to Watch Before the Opening Bell
BHP Group (BHP)
Copper prices bounced after last week’s steep pullback, with tight supply in China and a crackdown on illegal mining in the DRC back in focus. Copper producers including BHP Group moved with the metal. Traders watching BHP are effectively watching copper, since shifts in concentrate availability and pricing can influence earnings sensitivity and capital allocation decisions.
APA Group (APA)
ANZ has ruled out direct finance for new gas projects and pipelines, including APA Group’s proposed Beetaloo Basin infrastructure. All four big local banks now limit funding for new upstream oil and gas. That raises questions about the future funding mix for APA’s North to East Australia pipeline plan and shifts attention onto alternative lenders, partners, or project pacing.
NEXTDC (NXT)
Goodman Group and Digital Realty have jointly bought a 9.9% stake in NEXTDC at an average A$9.22 a share, paying up to A$10.40 for some stock. The pair say they are not currently planning a takeover but reserve the right to change stance. Investors now have a new reference point for valuation and a signal of interest from global data centre specialists.
Top Movers
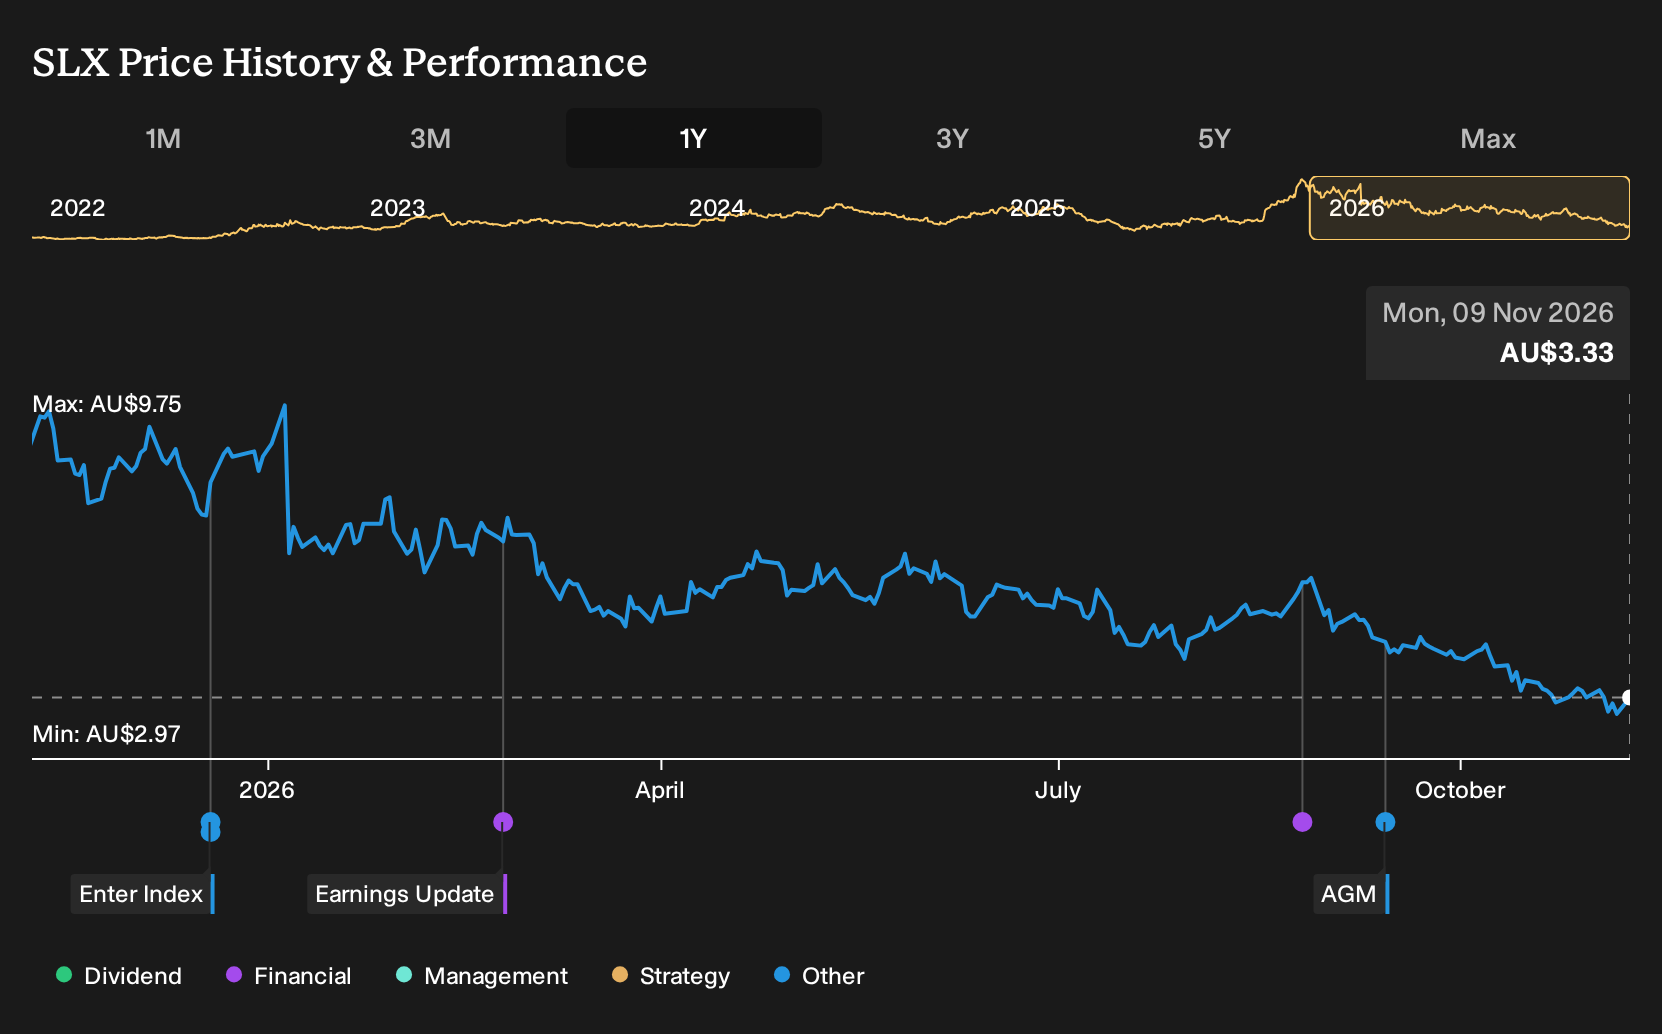
- Silex Systems (ASX:SLX) jumped 12.12% on renewed interest in uranium enrichment technology and potential future nuclear fuel demand.
- Paladin Energy (ASX:PDN) climbed 10.86% after quarterly results showed higher sales and a return to quarterly profitability.
- Star Entertainment Group (ASX:SGR) gained 9.68% as investors responded to the company secretary transition update and ongoing remediation focus.
Top Losers
- Ventia Services Group (ASX:VNT) fell 16.23%.
- Dyno Nobel (ASX:DNL) declined 10.99% after full year earnings showed higher sales and a shift to net profit.
- Scentre Group (ASX:SCG) slipped 4.43% after Morgan Stanley downgraded the stock on concerns around key tenant David Jones.

On The Radar
Australian trading over the next few sessions revolves around local confidence data and a dense run of bank and resource earnings, set against a key US inflation print.
- Westpac Consumer Confidence Index, Tue 10 Nov. The forecast sits at 78.3 versus the previous 80.4. A weaker result would underline pressure on household spending and keep a lid on expectations for a quick easing in Australian borrowing costs.
- NAB Business Confidence, Wed 11 Nov. The index previously read at 13 in negative territory with a forecast of 14, also below zero. Any deeper deterioration would highlight strain for listed industrials and small cap contractors that rely on new orders.
- Commonwealth Bank of Australia, Wed 11 Nov. Q1 2027 numbers place the focus on net interest margin and bad debts. Together, these help shape how investors assess earnings resilience for the broader Australian banking sector.
- Aristocrat Leisure, Thu 12 Nov. Fiscal 2026 results will put gaming revenue growth next to digital margins. The mix helps investors evaluate how much of Aristocrat Leisure’s earnings power comes from recurring online spend versus more cyclical venues.
- US CPI, Tue 10 Nov. Headline inflation is expected at 3.9% YoY and 0.3% MoM. A softer outcome would ease pressure on US yields and could take some heat out of the US dollar against the Australian dollar.
Sector & Industry Watch
Energy and Oil and Gas Recent weakness after strong year
Energy and Oil and Gas have both fallen over the past week, with 7 day returns down about 7%, even though year to date and 1 year numbers remain higher. Recent updates from MC Mining, Beetaloo Energy, Botala Energy and TMK Energy underline how many producers are leaning on lenders, shareholder cash and government approvals in order to keep projects moving while prices soften.
If you rely on Energy for income or inflation protection, this Thursday’s US crude oil inventory data are the key external check. A sharp move in oil around that release can quickly shift revenue expectations for local producers and fuel cost assumptions for airlines and transport heavy businesses.
Materials and Metals and Mining Miners edging up as deals flow
Materials and Metals and Mining have both recorded 7 day gains after a weaker 30 day patch, with 1 year returns still in positive territory. Capital raisings at Pacific Lime and Cement, Critical Minerals Group and Sarytogan Graphite, along with project news from BHP, FireFly Metals, IGO and a long list of explorers, show money still flowing into copper, gold and critical minerals even as the sector debates proposed capital gains tax changes.
If you hold a basket of miners or an ETF, the federal government response to industry concerns about those capital gains tax reforms is the one to watch. Any adjustment to the rules can affect how easily explorers raise equity compared with more established producers.
Consumer Discretionary Rebound continues with confidence in focus
Consumer Discretionary has risen over the past week and month while 1 year and year to date returns remain weaker, which suggests a bounce from low levels rather than a clear uptrend. Updates from Propel Funeral Partners, Flight Centre, Carma and ARB show some companies still growing volumes while others feel the pinch from higher mortgages, fuel costs and competition from cheaper imports.
If your portfolio includes retailers, travel stocks or auto exposed businesses, tonight’s Westpac Consumer Confidence Index is the key read. A softer print would underline pressure on non essential spending and can shape how boards talk about Christmas trading, discounting and inventory plans.
Tech Strong 7 day move off a low base
Tech has posted a solid 7 day return while year to date and 1 year numbers are still clearly weaker, so the recent strength looks like a recovery rally. Corporate moves at Codan, DUG Technology, Etherstack, X2M Connect and Talius Group, plus the register shake up at NEXTDC where Goodman Group and Digital Realty took a stake, have pulled attention back to contract pipelines and recurring software style revenue.
If you hold Technology exposure, focus on what management teams say at upcoming meetings about cash needs, capital raisings and the mix of one off contracts versus ongoing subscriptions. Any shift in tone can quickly change how durable this latest Tech bounce feels in everyday portfolios.
Banks Recent climb meets earnings and business survey test
Banks have enjoyed firm 30 day gains even though the latest 7 day return is slightly softer and 1 year performance is still close to flat. Full year commentary from ANZ, along with earlier updates from other majors, keeps the spotlight on net interest margins and bad debts at the same time as households and small businesses juggle higher rates.
If you hold bank stocks mainly for dividends, tomorrow’s NAB Business Confidence reading is the key local catalyst. A weaker outcome can feed into more cautious language from lenders on arrears and provisioning, which in turn can influence how boards think about future payout ratios.
Find Tomorrow's Top Performers
If bank dividends are the part of today’s story that matters most to you, start with this list of 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com