


EN
What Serica Energy (LSE:SER)'s UK Drilling Contract Means For Shareholders
- Serica Energy announced that it has signed a contract for Odfjell Drilling’s Beacon Pacific semi submersible rig to deliver a six well UK Continental Shelf campaign starting in the third quarter of 2027, with capacity to support both new drilling and plugging and abandonment activity across its portfolio.
- The decision to bring a high specification rig back to the Bruce field for the first wells there since 2012, targeting more than 10,000 boepd of potential incremental production, shows management prioritising near field projects that can use existing infrastructure rather than pursuing higher risk frontier exploration.
- We will now see how Serica Energy's investment narrative could shift as this multi well Beacon Pacific campaign is layered onto its existing plans.
Serica Energy Investment Narrative Recap
To own Serica Energy, you need to believe its North Sea portfolio can convert short cycle drilling into steadier production while managing outages at hubs like Triton and Bruce. The Beacon Pacific contract aligns with that idea by giving the business dedicated rig capacity for both new wells and plugging and abandonment across its fields.
The analyst consensus Narrative on Simply Wall St still flags Triton uptime, execution on infill projects from 2027, and UK tax policy as the near term swing factors. This new multi well program is important for medium term volumes, but it does not change the immediate risk around operational reliability or the timing of fiscal reform.
The Beacon Pacific contract ties directly into the multi well 2027 campaign already highlighted in the analyst consensus Narrative on Simply Wall St. Management now has a specific sixth generation rig lined up to execute those Bruce, Kyla, and Glendronach opportunities, which reduces some operational uncertainty around access to suitable equipment.
For investors, the read across is straightforward. The key production and cash flow catalysts still hinge on Triton coming back from its extended shutdown, ongoing reliability work at the Bruce hub, and integrating the wider portfolio. The new rig deal mainly clarifies how Serica Energy intends to deliver the next phase of drilling once those nearer term tasks are in hand.
Serica Energy's current analyst narrative points to revenue of US$1.2b and earnings of US$58.1m by 2029, based on 8.5% yearly revenue growth and an earnings swing of about US$60.7m from a loss of US$2.6m today to that forecast profit level.
Uncover how Serica Energy's fair value indicates a 46% potential upside to its current price that could narrow quickly.
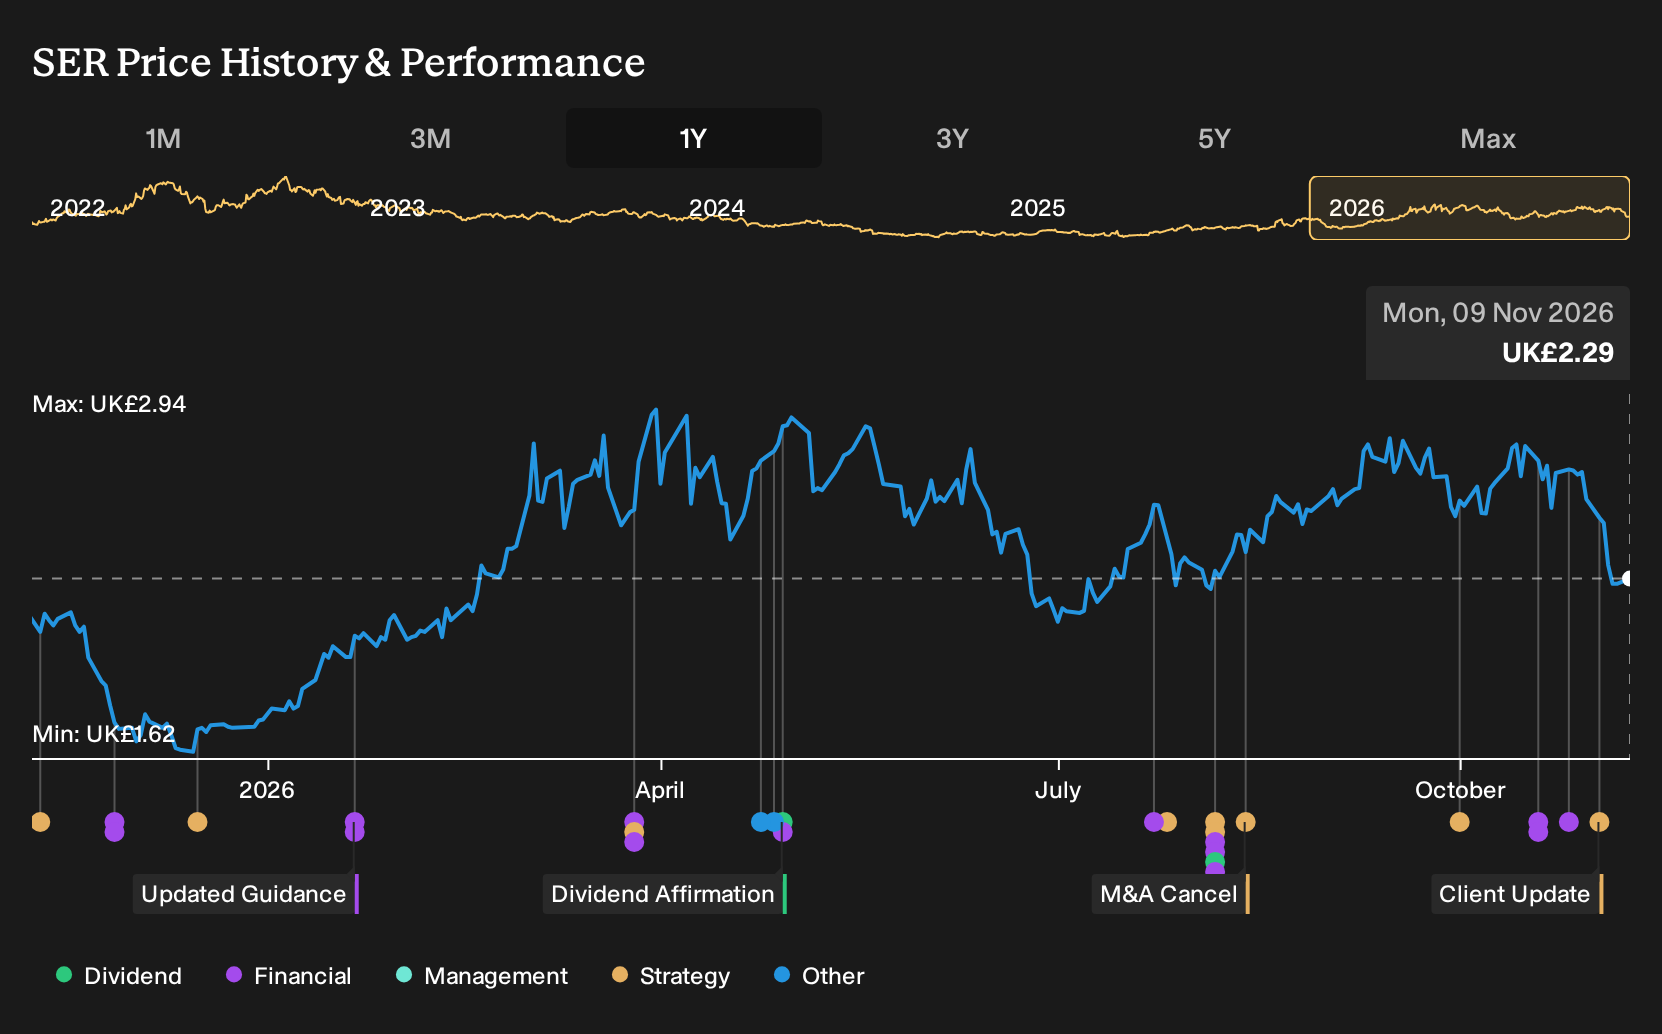
Exploring Other Perspectives
One bullish twist on Serica Energy focuses less on outage risk and more on how efficiently the group might convert its tax assets into earnings. The most optimistic analysts were already pencilling in revenue of about US$1.3b and earnings near US$201.8m by 2029. Those projections did not factor in this Beacon Pacific contract, so some views may shift as investors reassess both the potential upside and the execution risk around the new drilling plan.
Explore 4 other Serica Energy fair value estimates, including one that suggests as much as 484% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Serica Energy research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Serica Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Serica Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Serica Energy?
Once you have a view on Serica Energy, it can help to line it up against other opportunities that fit different goals such as value, resilience, or income. The Simply Wall St Screener gives you a quick way to filter that wider universe without getting buried in noise.
- If value is your priority and you want companies with quality fundamentals trading at what could be interesting prices, take a look at our hand picked 16 high quality undervalued stocks that meet those criteria.
- If capital preservation matters most and you prefer steadier profiles, scan the 4 resilient stocks with low risk scores that combine resilient financial characteristics with lower risk scores.
- If you are hunting for ideas that the market may not be paying full attention to yet, review the 5 high quality undiscovered gems with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com