


EN
QXO (QXO) Could Be 64% Undervalued On Acquisition Led Sales Growth
QXO (QXO) has put investors on alert after reporting a sharp rise in preliminary third quarter sales, largely tied to its Beacon Roofing Supply, Kodiak Building Partners, and TopBuild acquisitions.
QXO’s recent sales update lands after a tough stretch for the stock, with the share price down 24.8% over the past 90 days and the year-to-date share price return lower by 41.4%, while the 1-year total shareholder return has fallen 32.8%. Recent gains, including a 4.7% 7-day share price return and a 6.9% 30-day share price return, suggest some momentum is rebuilding as investors weigh the acquisition driven expansion, upcoming third quarter results on November 12, and Brad Jacobs’ separate CKX platform, against the longer track record of weaker total shareholder returns over three and five years.
Compare QXO’s acquisition driven story with other potential building products and industrial roll up candidates by scanning our hand picked list of solid balance sheet and fundamentals (25 results).
Bulls point to QXO’s acquisition-fueled scale and the gap to analyst targets, while bears highlight the losses and long-term underperformance. Which story looks closer to fair value once the numbers are lined up?
Most Popular Narrative: 64% Undervalued
Against QXO’s last close of $11.56, the most followed narrative on Simply Wall St points to a fair value of $32.53, which implies a large gap between price and estimated worth according to that framework. According to OOO97, an investor in the Simply Wall St Community who wrote the narrative, that gap hinges on aggressive acquisition plans and execution on margins rather than small tweaks around the edges.
QXO represents a disciplined M&A consolidation play in the $800B building products distribution market, led by Brad Jacobs, the most proven serial acquirer in modern industrial history (300x cumulative returns across four prior platforms, approximately 500 acquisitions). The company has built a $2.13B EBITDA pro-forma platform in under 18 months by acquiring Beacon Roofing Supply ($11B), Kodiak Building Partners ($2.25B), and TopBuild ($17B, closed July 1). This has created the largest publicly traded building products distributor in North America with number one positions in insulation and waterproofing and number two in roofing.
See why 24 investors see QXO as 64% undervalued.
Result: Fair Value of $32.53 (UNDERVALUED)
Still, the narrative can unravel quickly if integration of Beacon, Kodiak and TopBuild drags on costs, or if QXO’s acquisition pipeline stalls under its complex capital structure.
Find out about the key risks to this QXO narrative.
Another View: What QXO’s Sales Multiple Is Saying
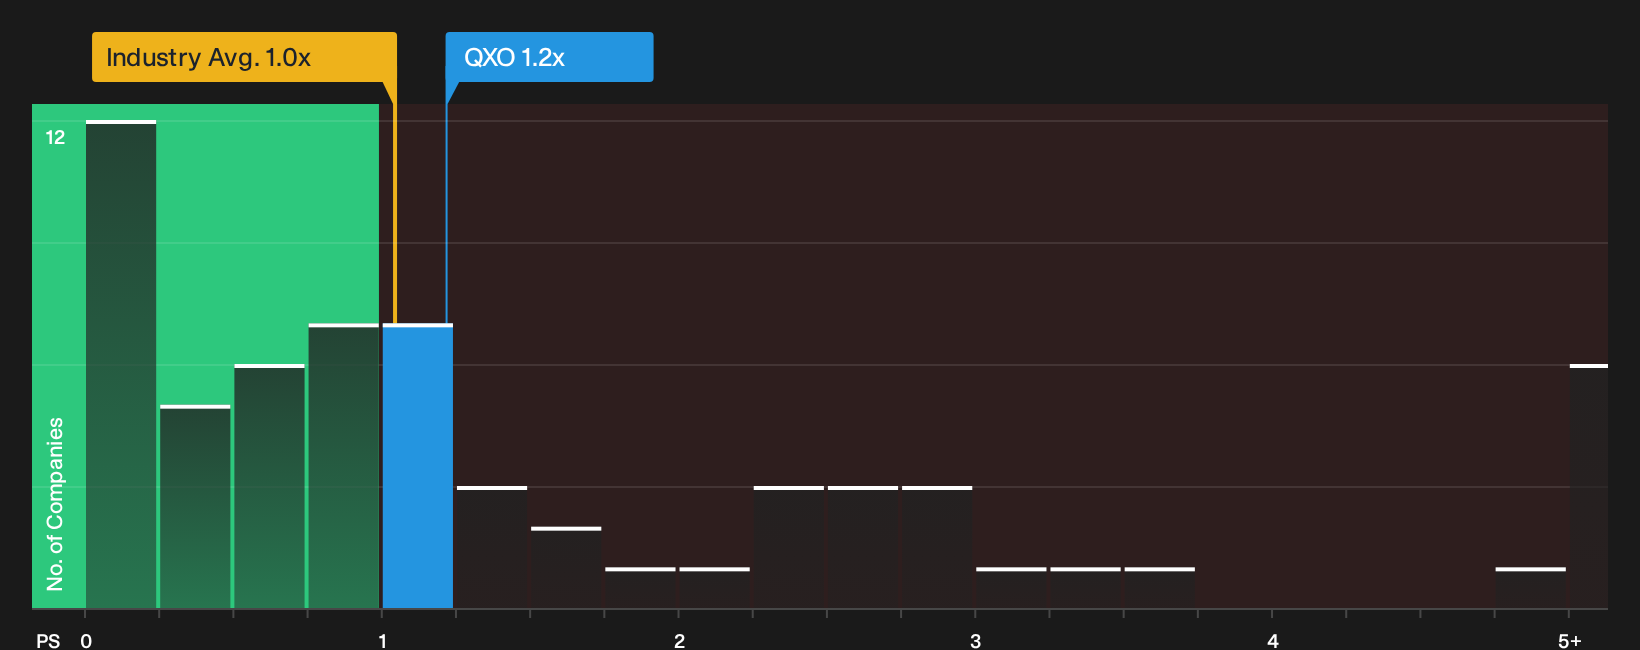
The DCF style community narrative pegs QXO as heavily undervalued, yet the simple sales multiple sends a more mixed signal. On a P/S of 1.2x, the stock looks expensive next to the broader US trade distributors group at 1x, but inexpensive versus closer peers on 3.1x and an estimated fair ratio of 3.7x. Is that a margin of safety or a warning about execution risk?
For investors comparing these signals, it helps to see how this pricing stacks up in detail. This includes the fair ratio that the market could move towards over time and how that might reprice QXO if expectations change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on QXO’s valuation and execution risk can feel messy, so move fast, look through the numbers yourself, and weigh both sides of the story. To see how the key positives and concerns line up in one place, start with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond QXO?
If QXO has you thinking harder about where to put fresh capital, use this moment to line up a few other high conviction ideas while you are here.
- Target stronger downside protection by focusing on businesses that score well on resilience and balance sheet quality through the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning companies that our models flag as attractively priced using the 40 high quality undervalued stocks.
- Spot potential up and comers with solid financial foundations before wider attention arrives by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com