


EN
Jupiter Fund Management (LSE:JUP) Looks Fairly Valued As Inflows And Earnings Improve
Jupiter Fund Management (LSE:JUP) is back in focus after reporting H1 2026 revenue and net income growth, as well as higher Q3 assets under management and net inflows that have lifted market interest in the stock.
The recent trading action reflects that shift in sentiment. Jupiter Fund Management’s share price has gained 11.8% over the past 90 days and 12.9% year to date, while the 1 year total shareholder return of 28.0% and 3 year total shareholder return of about 1.7x suggest that momentum has been building rather than fading.
Scan how Jupiter Fund Management’s renewed inflow story compares with other asset managers by reviewing our hand picked list of solid balance sheet and fundamentals (9 results) in the same space.
After that kind of rebound and a modest gap to the latest analyst target, is Jupiter Fund Management still pricing in a turnaround that has room to run, or has the recent rerating already done most of the work?
Most Popular Narrative: 3% Undervalued
Jupiter Fund Management closed at £1.80, while the analyst consensus Narrative on Simply Wall St places fair value around £1.85, which implies only a small margin between price and the modelled outcome using an 8.3% discount rate.
The main thing that has to go right is that Jupiter Fund Management converts its improved investment performance, broader platform and cost savings into sustainably stronger net inflows and a lower cost/income ratio, while industry fee margins continue to compress.
See why 15 investors see Jupiter Fund Management as 3% undervalued.
Result: Fair Value of £1.85 (ABOUT RIGHT)
Still, this narrative can be knocked off course if fee margins compress faster than guided, or if CCLA integration expenses and client churn bite harder than expected.
Find out about the key risks to this Jupiter Fund Management narrative.
Another View: DCF Flags Less Room For Error
The analyst Narrative frames Jupiter Fund Management as roughly fairly priced around £1.85 on earnings and multiples. Our DCF model tells a different story. On that cash flow lens, the shares at £1.80 trade above an estimated value near £1.28, which points to limited valuation cushion if execution slips.
For readers who lean on cash flows first, it is worth unpacking how the SWS DCF model treats fee compression, flat revenue and lower margins compared with simple earnings multiples, and then deciding which set of assumptions feels closer to what Jupiter Fund Management can actually deliver from here. Look into how the SWS DCF model arrives at its fair value.
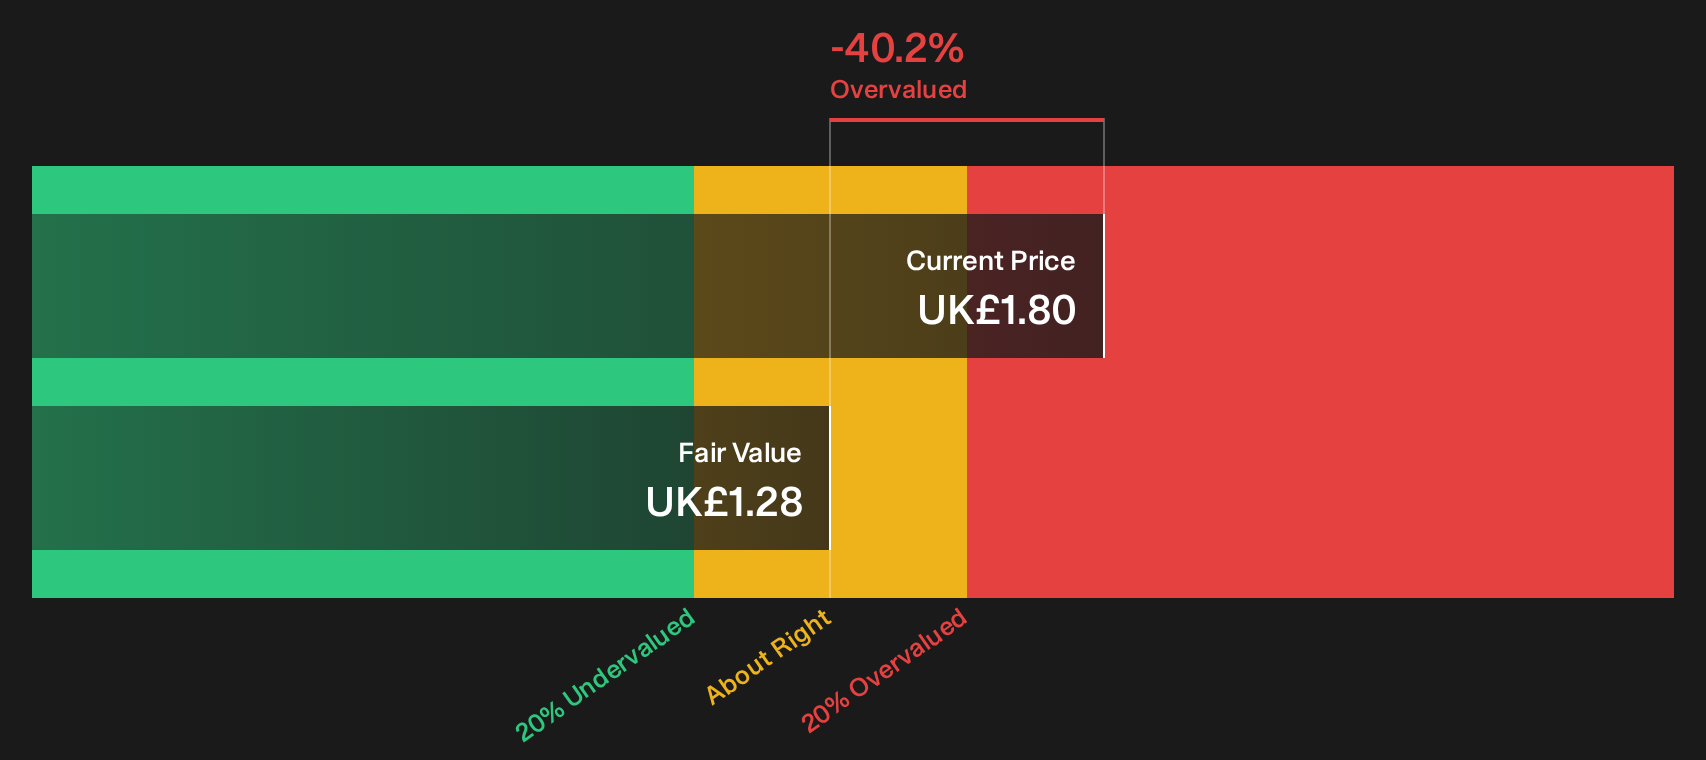
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Jupiter Fund Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling that the Jupiter Fund Management story could tilt either way from here, given both flagged risks and potential rewards, take a closer look at the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Jupiter Fund Management?
Do not stop with a single asset manager. Broaden your watchlist with a few focused idea lists that could highlight the next opportunity before the crowd catches on.
- Target stronger balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (9 results) that can help anchor your portfolio.
- Hunt for quality at a price that still looks appealing by reviewing a focused set of 16 high quality undervalued stocks screened on both cash flows and financial strength.
- Build a watchlist of potential future favourites by checking a tight group of 5 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com