


EN
Has RS Group (LSE:RS1) Become Pricey As Strong Half Year Earnings Lift Interest?
RS Group earnings spark fresh investor focus
RS Group (LSE:RS1) moved back into the spotlight after its H1 2027 earnings on 5 November 2026, reporting half year sales of £1,544.3m and net income of £87.8m.
RS Group’s recent half year figures landed alongside a share price that has climbed 8.69% over 90 days and delivered a 27.94% year to date share price return. The 1 year total shareholder return of 40.51% points to momentum that investors are currently rewarding more strongly in the equity than over the 3 year total shareholder return of 23.51% and the 5 year total shareholder return, which has declined 26.27%.
Extend your research beyond RS Group by scanning a curated set of industrial distributors and capital goods peers using our list of solid balance sheet and fundamentals (9 results), which have been filtered for resilience and financial strength.
RS Group’s sharp one year share price recovery, alongside steady earnings progress, splits opinion. Is this move mainly about better fundamentals or investors warming back up to the story, and how does that show up in the valuation?
Most Popular Narrative: 3% Overvalued
RS Group’s last close at £7.95 sits modestly above the analyst consensus Narrative fair value of £7.68, which is built using an 8.9% discount rate and detailed revenue and earnings forecasts from the analyst consensus Narrative on Simply Wall St.
The expansion of RS PRO and related private label ranges, with over 10,000 new products launched and revenue mix already above 14%, continues to shift the business toward higher margin, differentiated offerings. This supports a case for structurally firmer gross margins and smoother earnings over time.
See why 21 investors see RS Group as 3% overvalued.
Result: Fair Value of £7.68 (OVERVALUED)
Still, the RS Group narrative can unravel if weak demand in areas like Mexico and semiconductors persists, or if higher organic OpEx delivers slower than expected payback.
Find out about the key risks to this RS Group narrative.
Another View: RS Group on earnings multiples
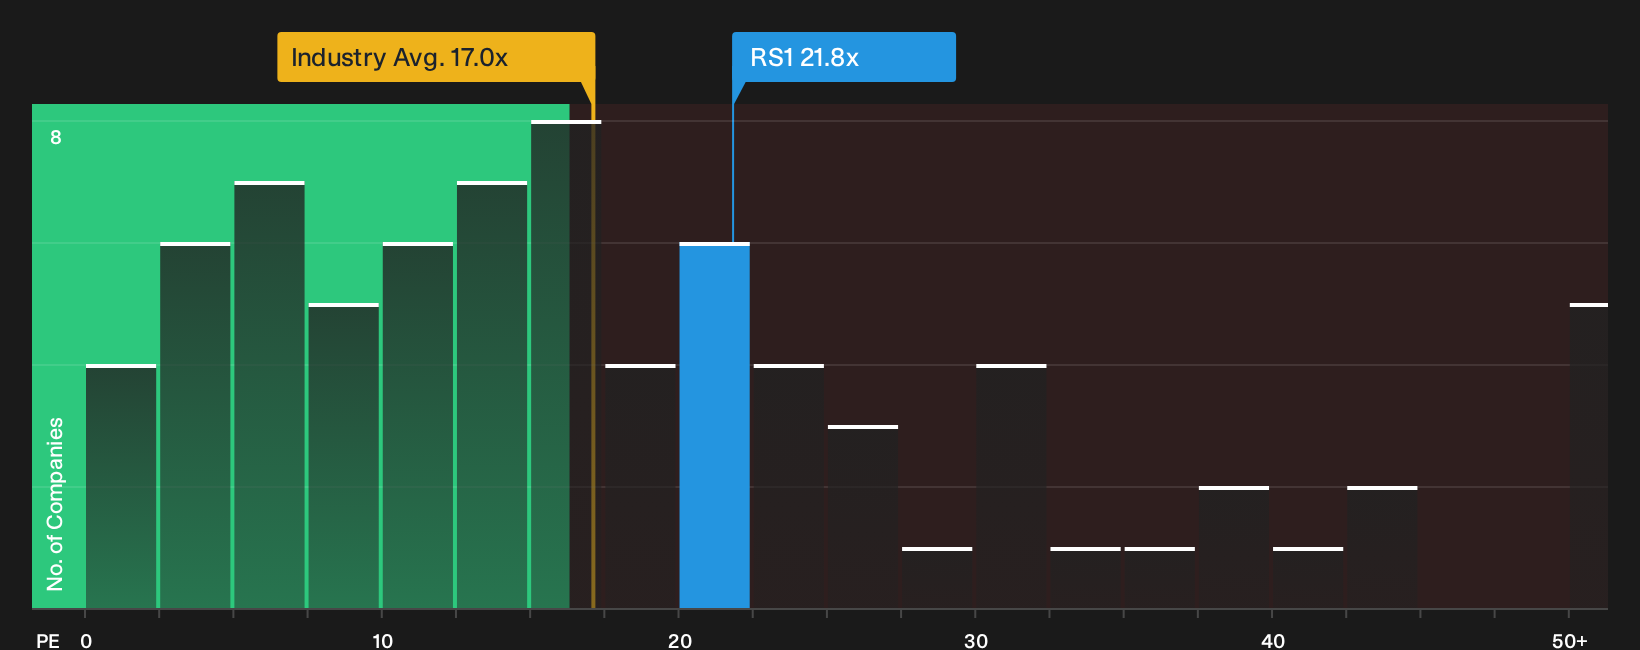
Analysts using narrative fair value see RS Group as about 3% overvalued at £7.95 versus £7.68. On a P/E of 21.8x, though, the shares trade below the peer average of 25.4x and close to a fair ratio of 22.9x, which points to a more balanced risk or opportunity. Which lens do you trust most?
To pressure test that earnings based view further, take a closer look at how the current multiple compares with peers and the fair ratio using our valuation breakdown, then decide whether the trade off between price and quality stacks up for you See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the current optimism around RS Group is justified or overdone? Move quickly, review the underlying drivers, then weigh up the 4 key rewards.
Looking for more RS Group sized ideas?
Do not stop with RS Group. Broaden your watchlist now by scanning focused stock ideas that match different risk levels, income goals and value preferences.
- Target potential mispricing and seek strong fundamentals by running a screen for 16 high quality undervalued stocks that meet your quality and valuation rules.
- Strengthen the income side of your portfolio by searching for reliable payers in our hand picked set of 6 dividend fortresses.
- Dial down volatility risk by filtering for companies in the 4 resilient stocks with low risk scores that combine sturdier balance sheets with more resilient business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com