


EN
How Investors May Respond To Macerich (MAC) Narrower Quarterly Loss
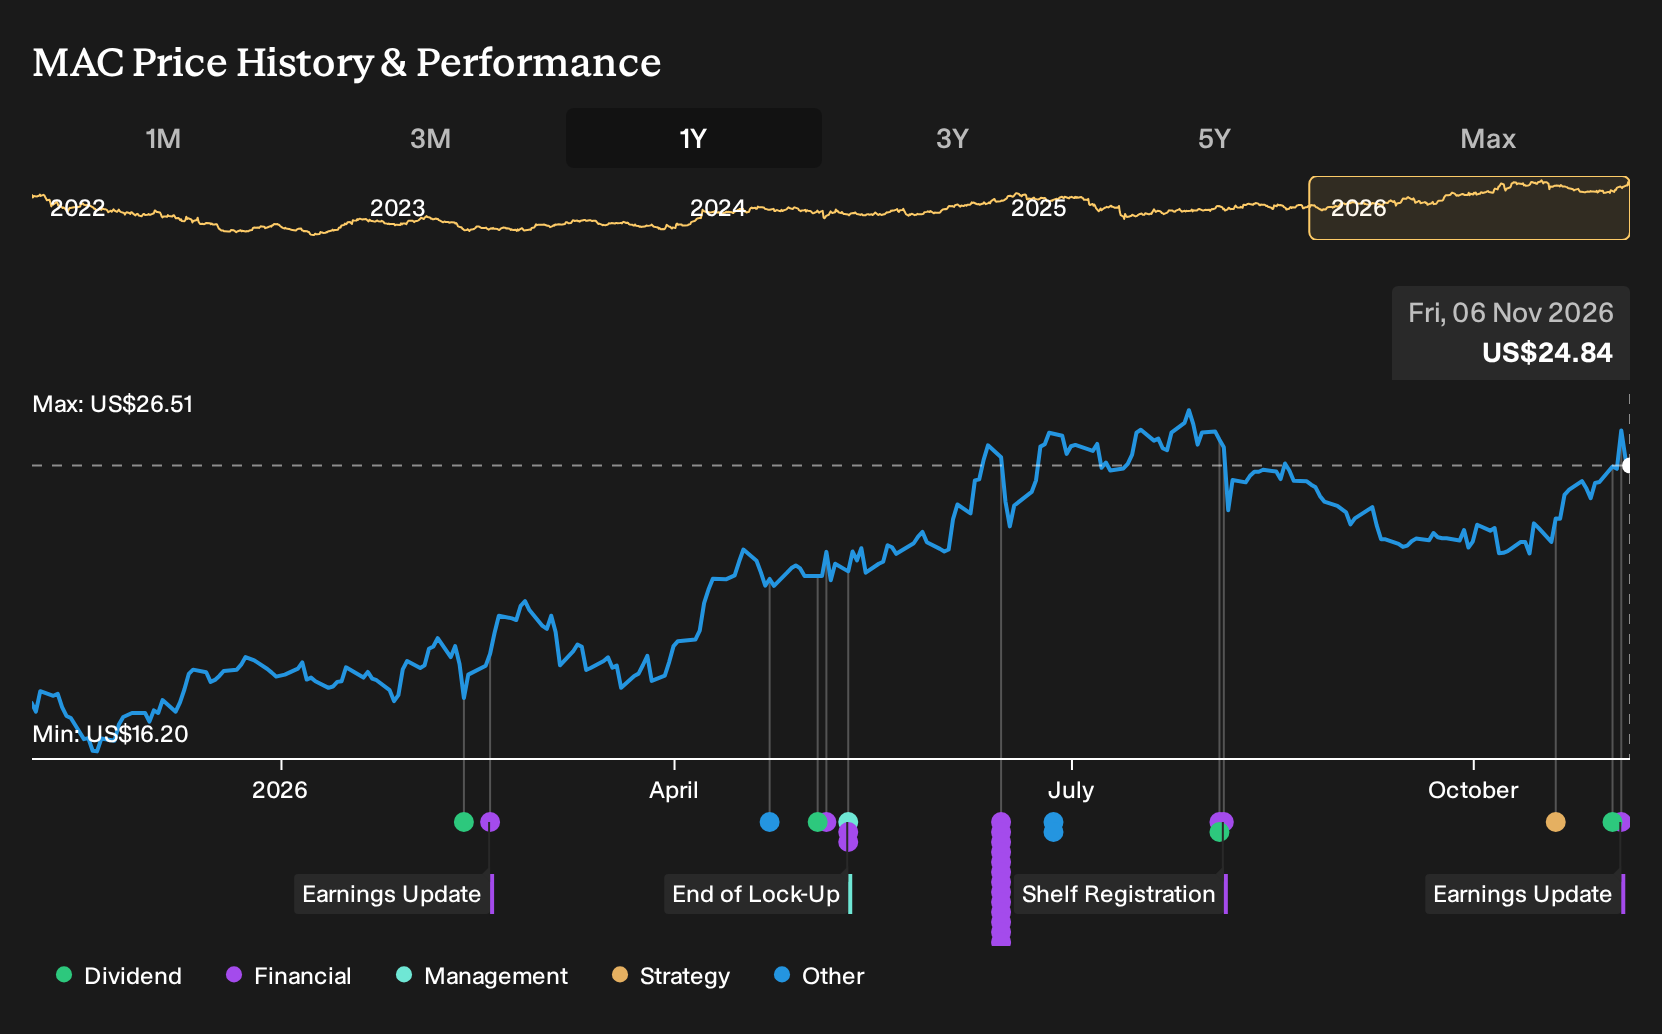
- Macerich reported third quarter 2026 revenue of US$260.07 million and a net loss of US$16.73 million, with basic and diluted loss per share from continuing operations at US$0.06. The board also declared a US$0.17 quarterly dividend payable in December 2026.
- The sharp reduction in quarterly net loss compared with the prior year points to pressure still present in the business, yet also to progress on cost control and operating efficiency as Macerich works through its mall repositioning efforts.
- We will examine how Macerich's narrower quarterly net loss influences the existing investment narrative built around its Path Forward plan.
Compare Macerich's earnings recovery and dividend move with a curated group of income ideas built on stronger balance sheets. Use the 7 dividend fortresses as a starting watchlist.
Macerich Investment Narrative Recap
To own Macerich, you need to believe its Path Forward plan can convert signed leases and committed anchors into stable cash flow while coping with e commerce pressure on traditional tenants. The latest quarter shows a much smaller loss, which supports that view, but the business is still unprofitable and interest costs remain a key constraint.
The key near term swing factor is execution on openings and rent collection from the signed not open pipeline. The biggest risk remains high leverage and refinancing exposure, highlighted in the analyst consensus narrative on Simply Wall St, which could restrict flexibility if borrowing costs stay high relative to operating income.
The most recent update is the third quarter 2026 result. Revenue for the period was US$260.07 million and the company reported a net loss of US$16.73 million, compared with a larger loss a year earlier. Together, these figures indicate an operation still under strain, with some signs of cost and margin repair starting to appear.
For the first nine months of 2026, Macerich recorded US$751.31 million of revenue and a net loss of US$80.16 million. When you compare this with catalysts such as leasing under the Path Forward plan and the objective of lowering net debt to EBITDA, the numbers highlight how much depends on turning committed projects into rent paying tenants while keeping redevelopment and interest costs contained.
Macerich's narrative projects US$1.2b revenue and US$96.8 million earnings by 2029. That profile is built on analysts' assumption of 3.8% yearly revenue growth and an earnings swing of roughly US$267 million from current earnings of a US$170.4 million loss.
Discover how Macerich's fair value indicates a 7% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternate view on Macerich focuses strongly on refinancing risk. The most pessimistic analysts were assuming revenue around US$1.0b and earnings near US$90.7 million by 2029 before this earnings and dividend news. That is a thinner story than consensus, and it shows how far opinions can stretch. Use those differences as a prompt to compare several narratives yourself and decide which assumptions you find more realistic as new information becomes available.
Explore 2 other Macerich fair value estimates, including one that suggests it could be worth just $26.56.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing and following your own research process.
- A great starting point for your Macerich research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Macerich. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Macerich's overall financial health at a glance.
Looking For More Investment Ideas Beyond Macerich?
Once you have formed a view on Macerich, it can help to set it alongside other opportunities that match your income goals, risk tolerance, and balance sheet preferences. The Simply Wall St Screener lets you do that quickly by filtering for focused shortlists built around clear fundamentals rather than headlines.
- If you want steadier capital and income profiles, start with companies that screen as relatively resilient by reviewing 31 resilient stocks with low risk scores that have historically paired lower risk scores with more durable business models.
- For investors hunting for quality at a reasonable price, use our value focused filter and scan through 40 high quality undervalued stocks that combine solid fundamentals with what our models flag as discounted valuations.
- If you are searching for under the radar opportunities, broaden your watchlist with a 19 high quality undiscovered gems that show strong financial underpinnings but receive less attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com