


EN
Is Willis Towers Watson (WTW) Below Fair Value As Q3 Earnings Reset Expectations?
Willis Towers Watson earnings set the tone
Willis Towers Watson (WTW) recently posted third quarter 2026 results, giving investors fresh numbers on sales, profit and earnings per share that can help reset expectations around the stock.
Recent trading has been mixed. The share price is around US$328.86 after slipping 2.27% over the last day. However, an 11.00% 30-day share price return suggests some short term momentum is building, while the 5-year total shareholder return of 53.30% points to a steadier long term record.
Spot opportunities with similar earnings setups by scanning our hand picked 40 high quality undervalued stocks, which pairs solid fundamentals with potential mispricing.With Willis Towers Watson now at roughly US$329 and sitting at a double discount to both analyst targets and intrinsic estimates, where does a fair, grounded valuation really land after this latest quarter?
Most Popular Narrative: 11% Undervalued
At a last close of $328.86, the analyst consensus Narrative on Simply Wall St points to a fair value for Willis Towers Watson of $370.63. This frames the current quote as trading at an 11% discount and puts the focus squarely on whether margin plans and cash flows can support that gap.
Acceleration of the Propel AI Acceleration Plan, which targets about US$400m in run-rate savings and higher enterprise and segment margin levels by 2028, could lift Willis Towers Watson’s adjusted operating margin profile and support higher earnings power.
See why 9 investors see Willis Towers Watson as 11% undervalued.
Result: Fair Value of $370.63 (UNDERVALUED)
Still, if commercial insurance pricing softens further or talent losses continue in key practices, Willis Towers Watson’s margin and AI savings narrative could come under pressure.
Find out about the key risks to this Willis Towers Watson narrative.
Another View on Willis Towers Watson’s Valuation
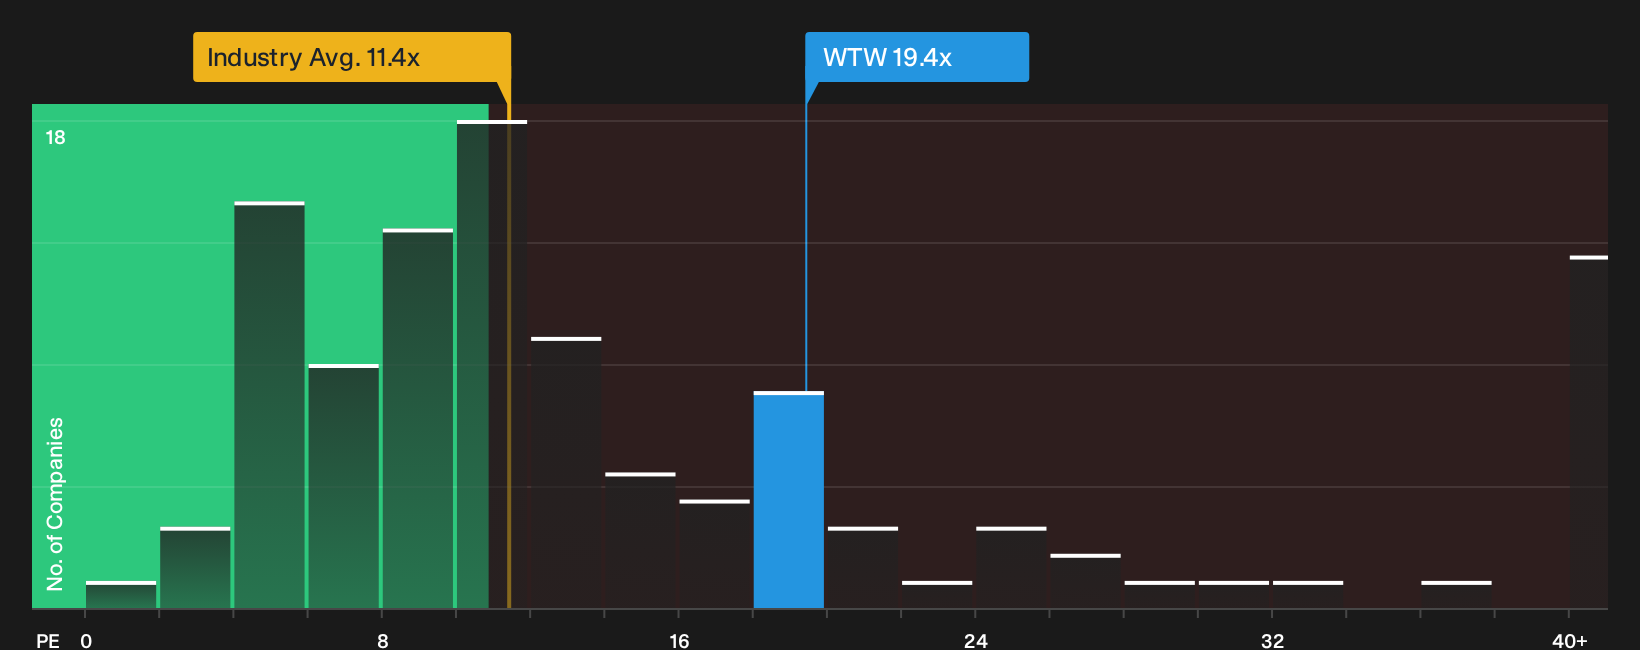
That 11% discount to fair value is only one side of the story. On earnings, Willis Towers Watson trades on a P/E of 19.4x compared with 11.4x for the wider US Insurance group and a fair ratio of 14.6x, which points to a richer tag and potential re rating risk if sentiment cools.
For an earnings based cross check that spells out what this gap could mean for upside or downside skew, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the tug of war between risks and rewards around Willis Towers Watson feels finely balanced to you, consider acting while the data is fresh and stress test the thesis against 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Willis Towers Watson?
You have already done the hard work by digging into Willis Towers Watson. Do not stop there when a wider set of opportunities sits one click away.
- Target resilient cash generators and compare payout strength using a curated set of income ideas through 7 dividend fortresses.
- Hunt for mispriced quality and stack potential bargains side by side with the Simply Wall St screener focused on 40 high quality undervalued stocks.
- Zero in on financial durability by filtering for robust balance sheets and stronger fundamentals through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com