


EN
How Social Housing Contract Wins At Downer EDI (ASX:DOW) Have Changed Its Investment Story
- Downer EDI announced that Homes Victoria awarded it a Property Maintenance Services Contract worth about A$400 million over a potential nine year term to provide responsive and planned maintenance, vacant property restorations and upgrade works for social housing in the East Division.
- The long dated social housing maintenance work adds another government backed services contract to Downer EDI's portfolio, deepening its role in essential facilities work tied to recurring activity rather than one off construction projects.
- This article examines how Downer EDI's push toward higher quality, long term services revenue is affected by this A$400 million housing contract.
Scan more government backed service providers like Downer EDI by jumping into our curated list of list of solid balance sheet and fundamentals (12 results).
Downer EDI Investment Narrative Recap
To own Downer EDI, you need to believe the shift toward long term, services heavy work can keep lifting earnings quality while the business transformation holds together operationally. The analyst consensus narrative on Simply Wall St leans on disciplined contract selection and execution. This new A$400 million Homes Victoria mandate fits that playbook and plugs into recurring social housing activity.
The short term swing factor still looks like delivery of the internal technology and process programs that are meant to support EBITA margins and cash conversion. The biggest near term risk remains state government outsourcing settings. Any reset in pricing or scope across defence, health, education or housing contracts could blunt the benefit of new wins.
The Homes Victoria award aligns with one of the core catalysts in that analyst consensus narrative on Simply Wall St, which points to long dated social housing and broader facilities contracts as a base for steadier Facilities segment earnings. This deal sits in that category and adds length to the pipeline that analysts already focus on.
For investors, the interest is how that contract base interacts with existing levers such as rising work in hand in power and water and the ongoing digital and transformation spend. If Downer EDI converts those projects and programs into cleaner margins and more predictable cash, the operational story behind the current P/E and value debate becomes clearer.
Downer EDI's current analyst narrative points to A$10.9b in revenue and A$355.9m in earnings by 2029, based on an assumed 4.0% yearly top line growth rate and an earnings uplift of about A$139.4m from A$216.5m today.
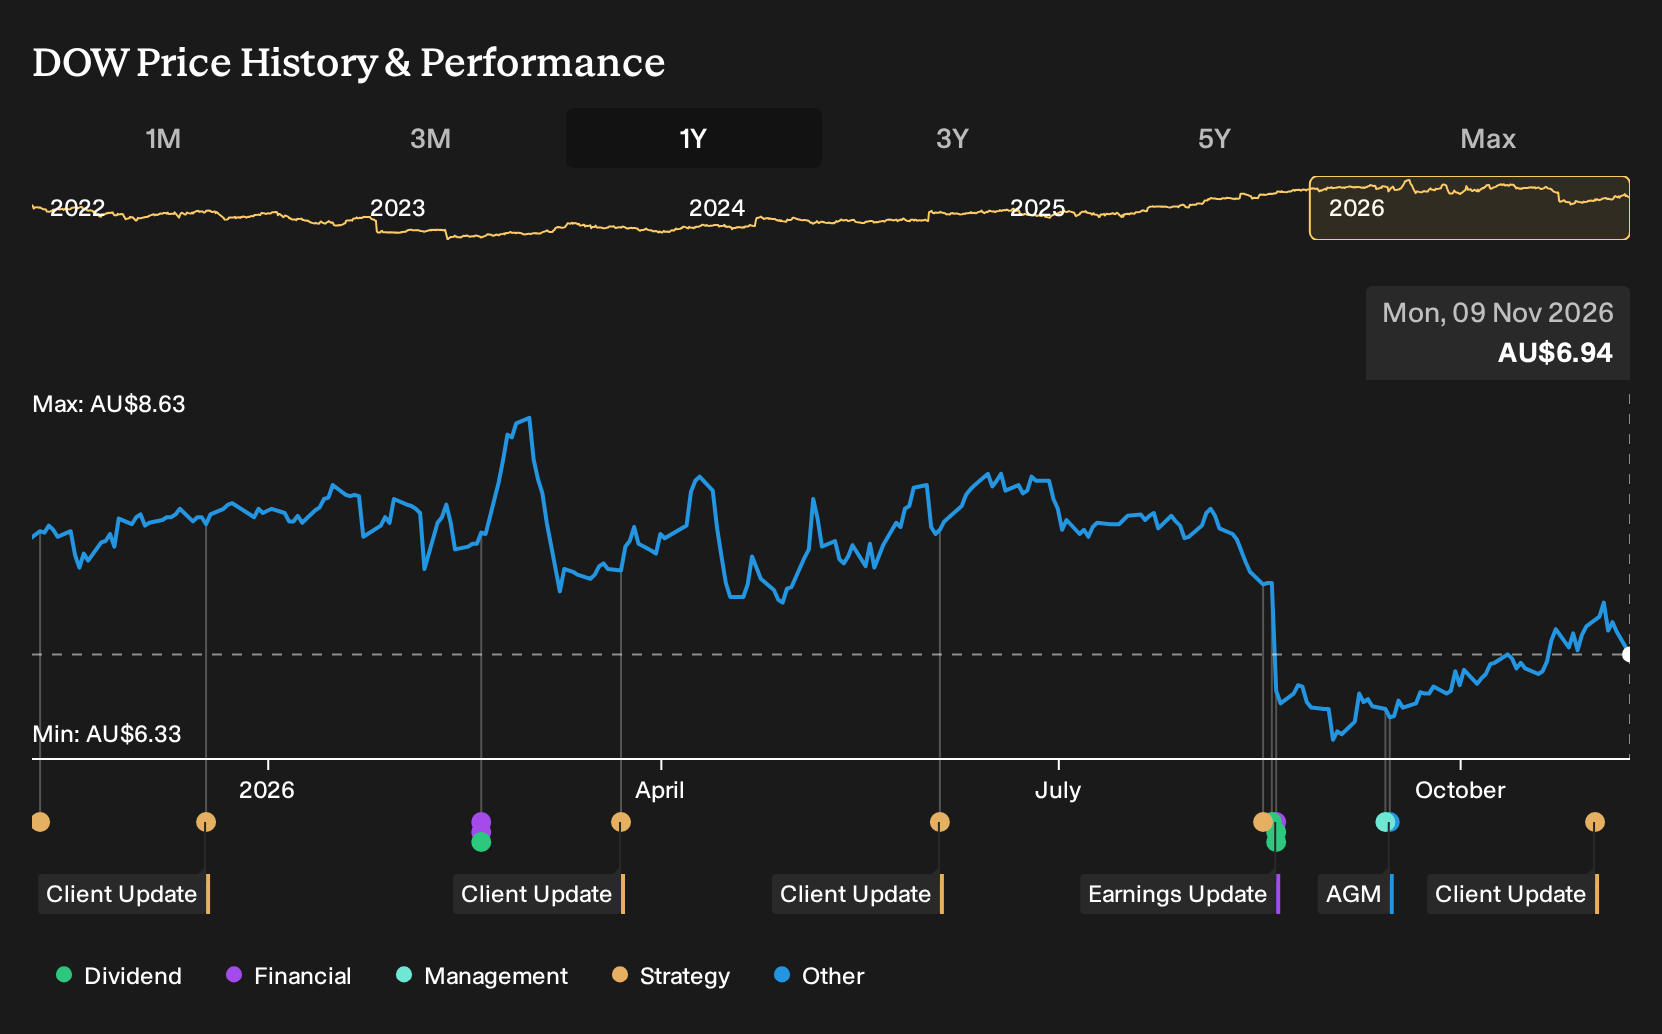
Discover why Downer EDI's fair value indicates a 12% potential upside to its current price, which could close sooner than you expect.
Exploring Other Perspectives
One alternative view treats contract repricing as the bigger issue for Downer EDI than winning new work. The most cautious analysts were modelling about A$10.6b of revenue and A$352.3m of earnings by 2029, and saw that scenario as already justifying the lower price target. This new Homes Victoria deal could prompt those expectations to shift. It can be useful to compare several narratives before deciding how you see the stock.
Explore another Downer EDI fair value estimate, including one that suggests it could be worth just A$7.78.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Downer EDI research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Downer EDI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Downer EDI's overall financial health at a glance.
Looking For More Investment Ideas Beyond Downer EDI?
If the Downer EDI story has sharpened your thinking about contract quality, cash flow, and balance sheet strength, it can be useful to test that same framework across a wider watchlist using the Simply Wall St Screener.
- For investors hunting for resilient businesses that aim to protect capital through steadier operations, the 6 resilient stocks with low risk scores can be a helpful place to start building a shortlist.
- If you prefer to focus on income, you can scan for companies that pair higher yields with underlying balance sheet support by filtering through 4 dividend fortresses.
- Those looking for stocks that the market might be pricing cautiously can review a curated pool of ideas via 2 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com