


EN
Is Adobe (ADBE) Trading At A Discount As AI Partnerships Grow?
Adobe has seen its share price retreat in recent years, and the stock closed at US$239.30 most recently. This puts fresh focus on a simple question for investors who care about valuation. Are you now paying a price that matches what the company is earning today and is expected to earn over time, or has sentiment moved further than the earnings story supports?
- Over the past 5 years, Adobe’s share price has fallen 63.7%, which puts earnings under the spotlight because so much of the earlier optimism has already been priced out.
- New partnerships that lean on Adobe’s AI tools, such as the recently announced multi year alliance with Disney and integrations of its CX Enterprise Coworker across major AI platforms, can influence how investors think about future profitability and the timing of cash flows from its software portfolio.
- Your read on Adobe is one view; the desks covering it have another. See what analysts think Adobe's shares could be worth.
The issue now is whether Adobe’s current market value is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing whether Adobe’s current P/E lines up with its earnings story, it can help to run the same test across a wider field of 40 high quality undervalued stocks.
Does Adobe Look Undervalued on Earnings?
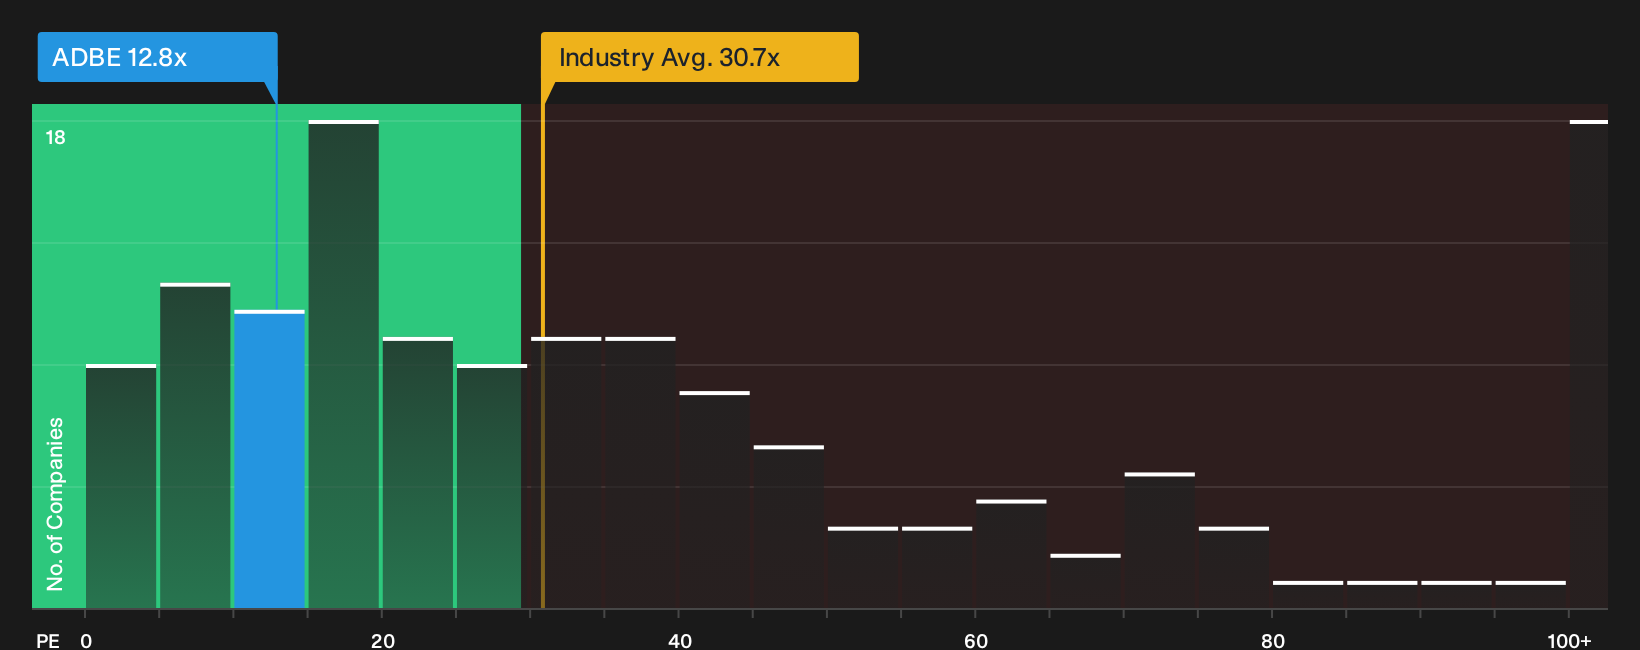
The P/E ratio suits Adobe because most of its value is tied to earnings from recurring software subscriptions. On this yardstick, the stock trades on about 12.8x earnings, well below the broader software industry on roughly 30.7x and far under the peer group average near 49.3x. Compared with the multiple implied by the Fair Ratio model, which blends Adobe’s growth profile, profitability, sector and size, the current P/E appears to be on the inexpensive side rather than the expensive side.
Because the multi year Disney alliance and wider AI partnerships have sharpened attention on Adobe’s content and customer experience products, the gap between its lower P/E and richer peer multiples is striking. The key judgment for you is whether that discount reflects a realistic appraisal of risks around AI monetisation and competition, or whether it points to earnings that are being valued more cautiously than those of similar software companies. Explore the numbers behind Adobe's P/E valuation.
The Adobe Narrative: What Would Justify Today's Price?
Adobe Narratives on Simply Wall St pick up where this valuation question leaves off by spelling out what would need to happen to growth, margins and earnings for the stock to be worth meaningfully more or less than today’s price. Each scenario links a specific fair value to a particular mix of future catalysts and potential setbacks for Adobe, so you can track which version of the story the business is actually moving toward over time.
Views on Adobe split sharply between investors who see an overreaction to AI risk and those who think the stock has become a long running value trap.
Bull case: 48% undervalued
According to BlackJesus, an investor in the Simply Wall St Community, Adobe’s AI pivot and pricing model are being treated far too pessimistically.
"The disconnect between these fundamentals and the compressed valuation multiple suggests a significant margin of safety for the patient investor, provided the company can prove its AI monetization strategy..."
Discover why this Narrative puts Adobe at 48% undervalued.
Bear case: 47% overvalued
heartwood, a Simply Wall St Community investor who wrote the opposing Narrative, worries Adobe’s AI bets are hurting both users and long term holders.
"Adobe's investment in Firefly has caused great harm in the user community, it cannibalizes the user base, it devalues the work of original content creators..."
Explore why this Narrative puts Adobe at 47% overvalued.
Adobe’s valuation is only half the story
Price and earnings paint one picture of Adobe, but Simply Wall St’s broader checks have also flagged specific concerns that investors often overlook and that deserve a closer look before making any decision. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com