


EN
Sat Out Freeport McMoRan's Rally? Here Is What Holders Saw
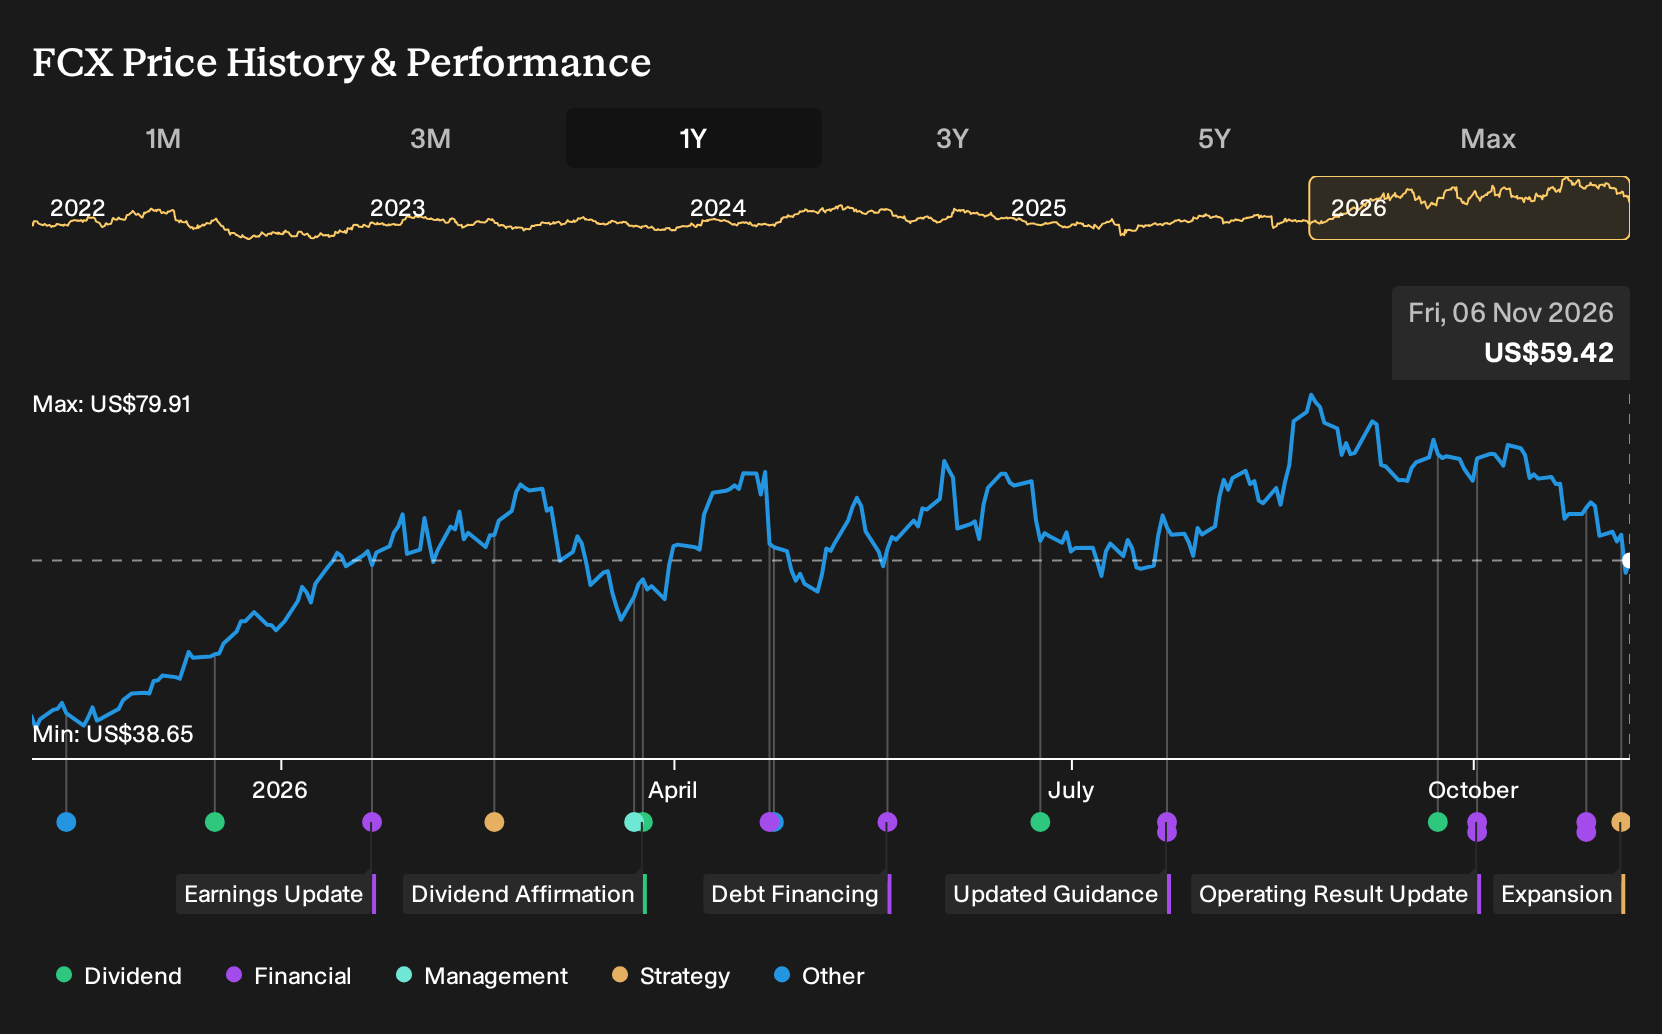
If Freeport-McMoRan sat on your watchlist instead of in your account, the past year probably felt expensive. Investors who held Freeport-McMoRan over the past year are up 50.6%, including dividends. That move followed a year when analysts were already arguing over whether copper producers could justify higher P/E multiples as U.S. policy, Indonesian smelter plans, and Grasberg risks pulled in opposite directions. Which of those business assumptions deserved more weight before the gain arrived?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The move put Freeport-McMoRan in the middle of this trade. Scan 16 top copper producer stocks for other companies exposed to it.
The Case For, And Against, Freeport-McMoRan Back Then
The shares cost US$38.65 at the start of the period, and anyone looking at Freeport-McMoRan had to choose between two sharply different stories.
On the optimistic side, one Narrative put Fair Value at US$50.06, about 30% above the start price. That view leaned on revenue growth of 6.5%, a profit margin assumption of 10.8%, and a future P/E of 26.7x supported by the new Indonesian smelter and U.S. policy support.
The opposing case anchored Fair Value at US$27, around 30% below the start price. It focused on technological substitution, tighter environmental rules, and resource nationalism as potential long-run drags on demand, costs, and access to reserves.
What The Results Changed For Freeport-McMoRan
The clearest new data point was Freeport-McMoRan's Q3 2026 numbers. Revenue moved from US$6,972m in Q3 2025 to US$7,546m in Q3 2026, while net income increased from US$667m to US$1,166m and net margin stepped up from 9.6% to 15.5%. Stronger profitability supported the optimistic case on margins, even as Grasberg execution issues kept the cautious story alive.
The takeaway for you is simple. When a thesis leans on higher future margins, track reported net margin quarter by quarter and see whether it is actually drifting toward the assumption used in the Fair Value model.
What Freeport-McMoRan's Price Already Bakes In
Freeport-McMoRan now trades at US$59.42 after a 50.6% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, framing today’s quote as a test of how much execution confidence you have.
That Narrative leans on questions about scaling low cost leach volumes and managing higher capital and operating spending. Anyone paying the current price is effectively assuming those projects deliver at scale, so how do the highlighted inflation and Grasberg execution risks color that expectation?
"Bearish analysts expect Freeport-McMoRan to struggle to earn its higher capital and operating costs back if input inflation persists, Grasberg execution issues recur, and regulatory pressures on copper and alternative materials continue to build. The main requirement for success is that Freeport-McMoRan scales its low-cost leach program and brownfield expansions, such as Bagdad and Grasberg, sufficiently to offset higher U.S. cash costs and the larger Indonesia smelter footprint while maintaining reliable production."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 37% below our estimate - turns a large backlog of AI infrastructure and multicloud database deals into subscription revenue.
- Company 2 - 26% below our estimate - grows a large digital banking customer base while lifting revenue per active account and efficiency.
- Company 3 - 47% below our estimate - commits heavy capital to new film plants to expand higher margin OEM and dealer channels.
That is three of the list. See all 40 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com