


EN
Brookfield (TSX:BN) Stock May Look Stretched On Fresh AI Data Center Plans
Brookfield has delivered a very strong 3 year share price run, which now puts a spotlight on whether the current valuation is supported by what the business earns. With the stock recently closing at US$58.47 and fresh headlines around large new projects, the question for investors is how much of Brookfield's earnings power is already reflected in that price.
- The share price has gained 101.3% over the past 3 years, which makes it important to test how firmly this move is anchored in underlying earnings.
- Plans for a more than £20b AI focused data center build in England and the recent US$12b raise for Brookfield's credit arm can influence expectations for future profitability and the timing of cash flows that underpin its earnings profile.
- There is a second opinion on Brookfield worth weighing. See what analysts think Brookfield's shares could be worth.
The issue now is whether Brookfield's current share price is justified by its earnings when set against the industry average.
If Brookfield's AI data center push and credit expansion has your attention but you want a broader watchlist, a focused stock screen is another starting point for research in 53 AI infrastructure stocks.
Is Brookfield Getting Expensive on Earnings?
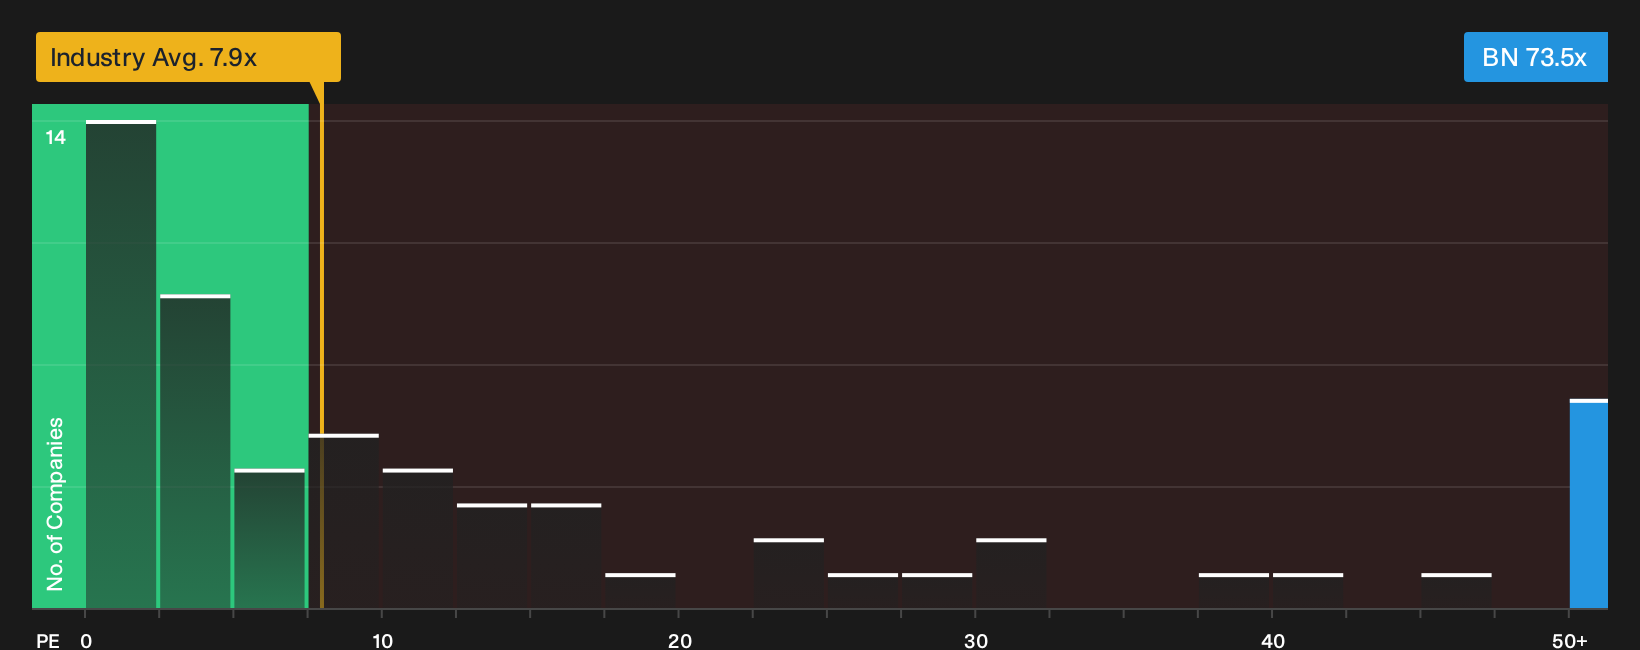
P/E fits Brookfield because earnings still sit at the center of how investors judge an asset manager's long term fee stream. On this yardstick, the stock trades on a P/E of 73.5x, which is far above the Capital Markets industry average of 7.9x and also well ahead of the broader peer group on 13.5x. That is a steep premium for each dollar of current earnings.
Because Brookfield is planning a multi decade AI data center build in England, the share price now embeds a lot of confidence that these long duration projects and the enlarged credit platform will support stronger profitability in time. The excess returns model heavily penalises the business for its current economics, so the huge gap between 73.5x and the industry benchmark reads less as a precise mispricing and more as a warning that, on this framework, the stock currently screens as overvalued on earnings. Explore the numbers behind Brookfield's P/E valuation.
The Brookfield Narrative: What Would Justify Today's Price?
Narratives on Brookfield pick up where the P/E puzzle leaves off and explain what paths for growth, profitability and earnings would need to hold for the stock to appear materially richer or cheaper than it does today on Simply Wall St's Community page. Instead of a single point estimate from a model or ratio, you see the future assumptions that figure relies on, so you can judge over time whether Brookfield's real world progress matches them.
One of the top community narratives on Brookfield: 29% undervalued
According to ANTONI0, a Simply Wall St Community investor who wrote the Narrative, Brookfield’s appeal starts with how earnings compound inside the group.
"The return comes from compounding earnings, any narrowing of the discount is the accelerant, not the engine..."
Discover why this Narrative puts Brookfield at 29% undervalued.
One more Brookfield check that belongs beside the earnings math
Before you stop at the P/E and project list, it is worth asking who is steering Brookfield, how their rewards are structured and whether those incentives align with your own goals. See who runs Brookfield and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com