


EN
Mach Natural Resources (MNR) Stock Could Be A Bargain As 2027 Plan Takes Shape
Mach Natural Resources has seen its unit price fall in recent months, and that drop puts a spotlight on a simple question for investors who follow this stock. Is the current market value properly explained by what the partnership is earning today and is expected to earn over time?
- Over the past 3 years, Mach Natural Resources has declined 21.7%, which puts real pressure on whether the current earnings profile can support even this lower price level.
- The partnership recently outlined a plan to keep capital spending controlled while focusing on cash-flowing oil assets. This can shape how reliably earnings support distributions and future reinvestment needs.
- Your read on Mach Natural Resources is one view; the desks covering it have another. See what analysts think Mach Natural Resources's shares could be worth.
The issue now is whether Mach Natural Resources' recent unit price, after this pullback, is justified by the earnings power of the business.
If you are weighing Mach Natural Resources against other opportunities that are also being filtered on valuation and quality, a focused screen of 40 high quality undervalued stocks may be useful.
Is Mach Natural Resources a Bargain on Earnings?
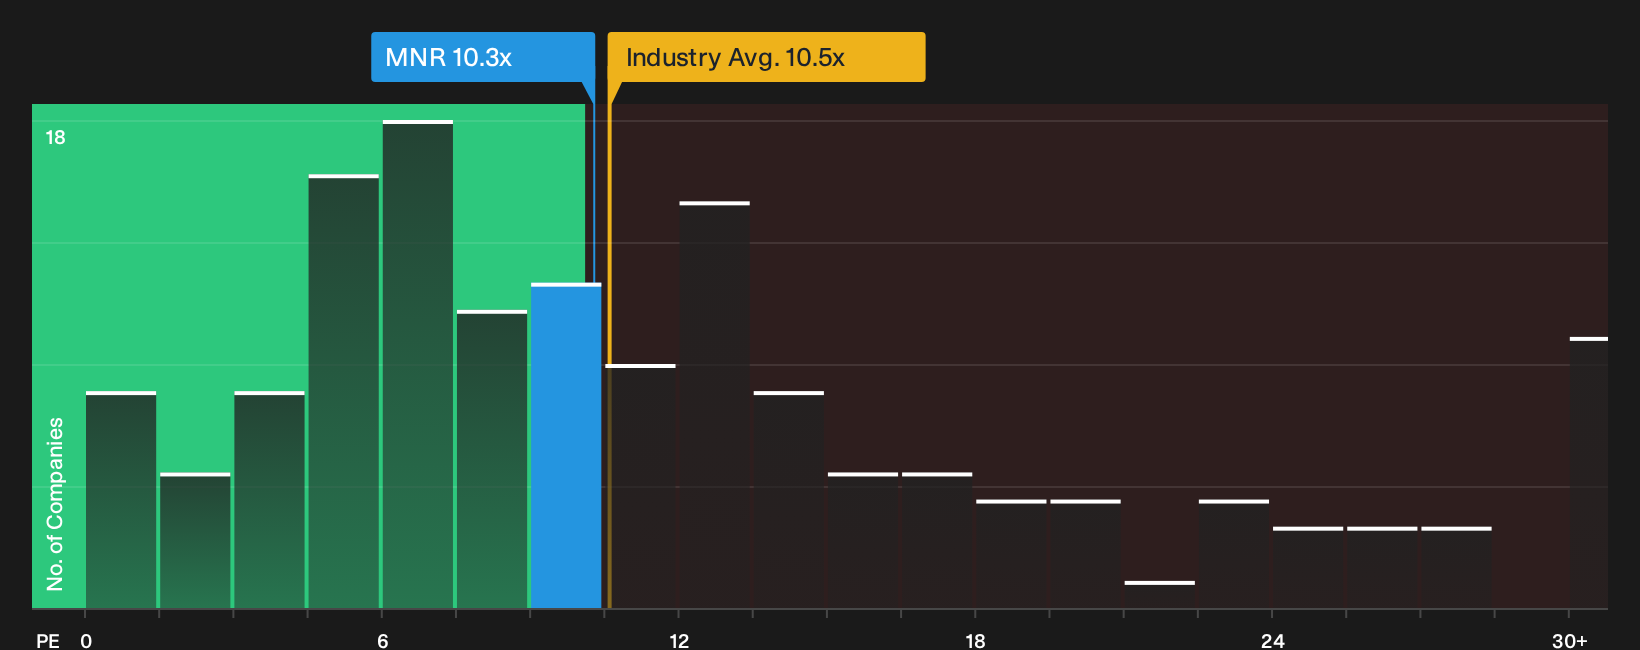
The P/E ratio suits Mach Natural Resources because earnings remain a central yardstick for how the partnership funds distributions and future drilling. At about 10.3x, the current P/E sits slightly below the broader oil and gas sector on roughly 10.5x and sits more clearly under the peer group on about 12.8x. That spread suggests the market is applying a modest discount to Mach Natural Resources relative to comparable operators.
The Fair Ratio model, which looks at factors such as profitability profile, size, risk and sector norms, points to a higher P/E than where Mach Natural Resources trades today, so the units screen as undervalued on this metric. Because management is guiding to a reinvestment rate below 50% of operating cash flow and a disciplined acquisition plan following the latest Q3 2026 update, the current earnings multiple indicates the market is not paying up for that approach. Explore the numbers behind Mach Natural Resources's P/E valuation.
The Mach Natural Resources Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Mach Natural Resources, spelling out which paths for volumes, margins and earnings would need to hold for the units to trade meaningfully above or below where they change hands today. The article also sets out the underlying assumptions behind each fair value view in a way you can compare against the partnership's actual results as they arrive on Simply Wall St's Community page.
One of the top narratives on Mach Natural Resources: 47% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is management executing on its plan to reduce leverage from roughly 1.3 to 1.4x debt/EBITDA back toward about 1x by 2027 while continuing to buy and integrate distressed assets and flex capital between oil and gas…"
Discover why this Narrative puts Mach Natural Resources at 47% undervalued.
One more forward-looking check for Mach Natural Resources
There is one more angle to line up against Mach Natural Resources' current P/E and story: how professional analysts see the business a few years from now and what that implies for earnings power. Explore where analysts expect Mach Natural Resources to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com