


EN
Omada Health (OMDA) Stock May Be Overvalued Despite Raised 2026 Guidance
Omada Health has seen its share price slide over the past month, even as the business reports record profitability, which puts a sharper spotlight on whether the current valuation is still in line with its earnings power. With the stock back under pressure, the question is how much of the recent operational progress is already reflected in the price you see on screen.
- Omada Health is down about 30.0% over the past month, which puts recent earnings-driven optimism and today’s earnings multiple under closer scrutiny.
- The company recently reported record revenue and a record net profit, which can support a market view that its earnings base is becoming more established and potentially less dependent on distant growth assumptions.
- Your read on Omada Health is one view; the desks covering it have another. See what analysts think Omada Health's shares could be worth.
The issue now is whether Omada Health's current share price is adequately supported by its earnings when set against the Fair Ratio benchmark.
If you want a broader watchlist while you assess whether Omada Health's earnings justify today's price, a focused stock screen built around 40 high quality undervalued stocks can be a useful second starting point.
Does Omada Health Look Pricey on Earnings?
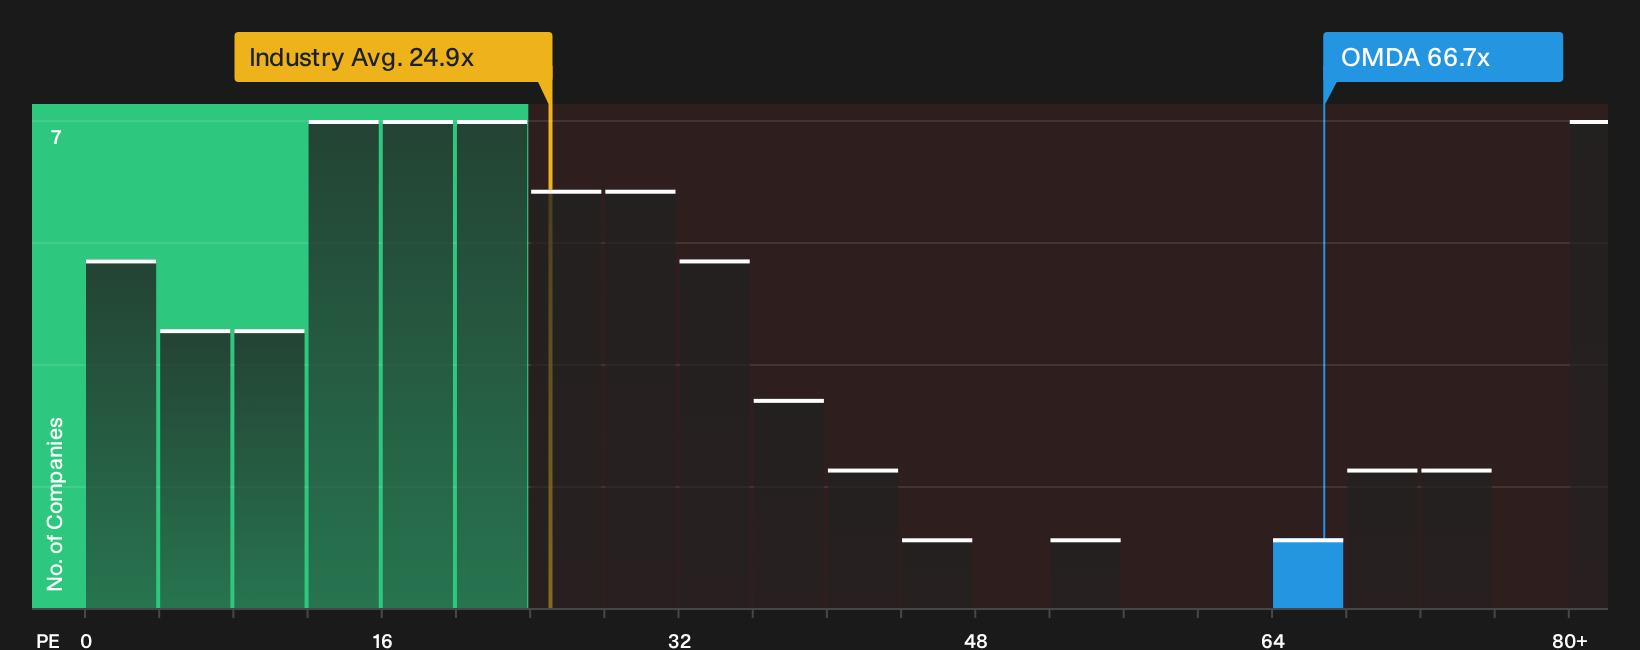
The P/E ratio suits Omada Health because the market is clearly focused on its bottom line after the recent move into stronger profitability. On this measure, Omada Health trades on about 66.7x earnings, compared with a Healthcare sector average near 24.9x and a peer group closer to 56.8x. That places the stock on a richer multiple than both its broad industry and more direct comparables.
Because the Fair Ratio model blends factors like growth profile, margins, scale and risk, it points to a lower P/E than the one investors are currently paying. As a result, the shares screen as overvalued on this framework. Despite Omada Health lifting 2026 revenue guidance after a record Q3, the current earnings multiple still prices the business at a premium to what this tailored benchmark implies. Explore the numbers behind Omada Health's P/E valuation.
The Omada Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Omada Health's valuation riddle leaves off by spelling out which paths for future growth, profitability and earnings would need to hold for the shares to be worth materially more or less than today’s price. They sit on the platform’s Community page as structured viewpoints. Each one treats fair value as a hypothesis about how Omada Health's business develops that you can watch over time, rather than a single static number.
One of the top narratives on Omada Health: 31% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"Although Omada Health highlights access to more than 25 million covered lives through large PBMs and health plans, the current base of roughly 1.1 million active members shows that most covered individuals are not yet enrolling..."
Discover why this Narrative puts Omada Health at 31% undervalued.
One more Omada Health factor to check before you make a move
Market pricing tells you what investors think today, but the analyst models looking a few years out give you a second lens on what might be built into Omada Health's story. Explore where analysts expect Omada Health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com