


EN
Crane (CR) Could Be 15% Undervalued After Strong Earnings And Higher 2026 Guidance
Why Crane’s latest earnings and guidance update matters now
Crane (CR) just paired a regular fourth quarter dividend of $0.255 per share with fresh third quarter results and a higher full year 2026 earnings outlook, giving investors new information to reconsider the stock.
At a share price of US$201.06, Crane has seen short term share price momentum cool, with the 90 day share price return down 8.84% while the year to date share price return is up 7.21% and the 5 year total shareholder return has more than tripled.
Compare Crane’s earnings momentum and dividend profile with a curated group of industrials by scanning 19 high quality undiscovered gems that may be flying under most investors’ radar.
After a strong quarter, firmer guidance and a recent cooling in Crane’s share price, the real test now is simple: does the current valuation still reward new risk takers more than it penalises them?
Most Popular Narrative: 15% Undervalued
Crane’s last close at $201.06 sits below the analyst consensus Narrative fair value of $237.20. The analyst consensus Narrative on Simply Wall St builds this from detailed earnings, margin and backlog forecasts using an 8.6% discount rate.
Crane’s recent acquisition of PSI, which includes Druck, Panametrics and Reuter-Stokes, continues to expand the company’s presence in higher margin sensing and fluid control applications. 2026 EPS accretion is now guided at about US$0.20 compared with the original US$0.08 expectation, supporting further earnings and margin growth.
See why 5 investors see Crane as 15% undervalued.
Result: Fair Value of $237.20 (UNDERVALUED)
Still, the story around Crane could change quickly if chemical end markets stay weak in Process Flow Technologies, or if premium P/E expectations ease with any margin slip.
Find out about the key risks to this Crane narrative.
Another view on Crane’s valuation
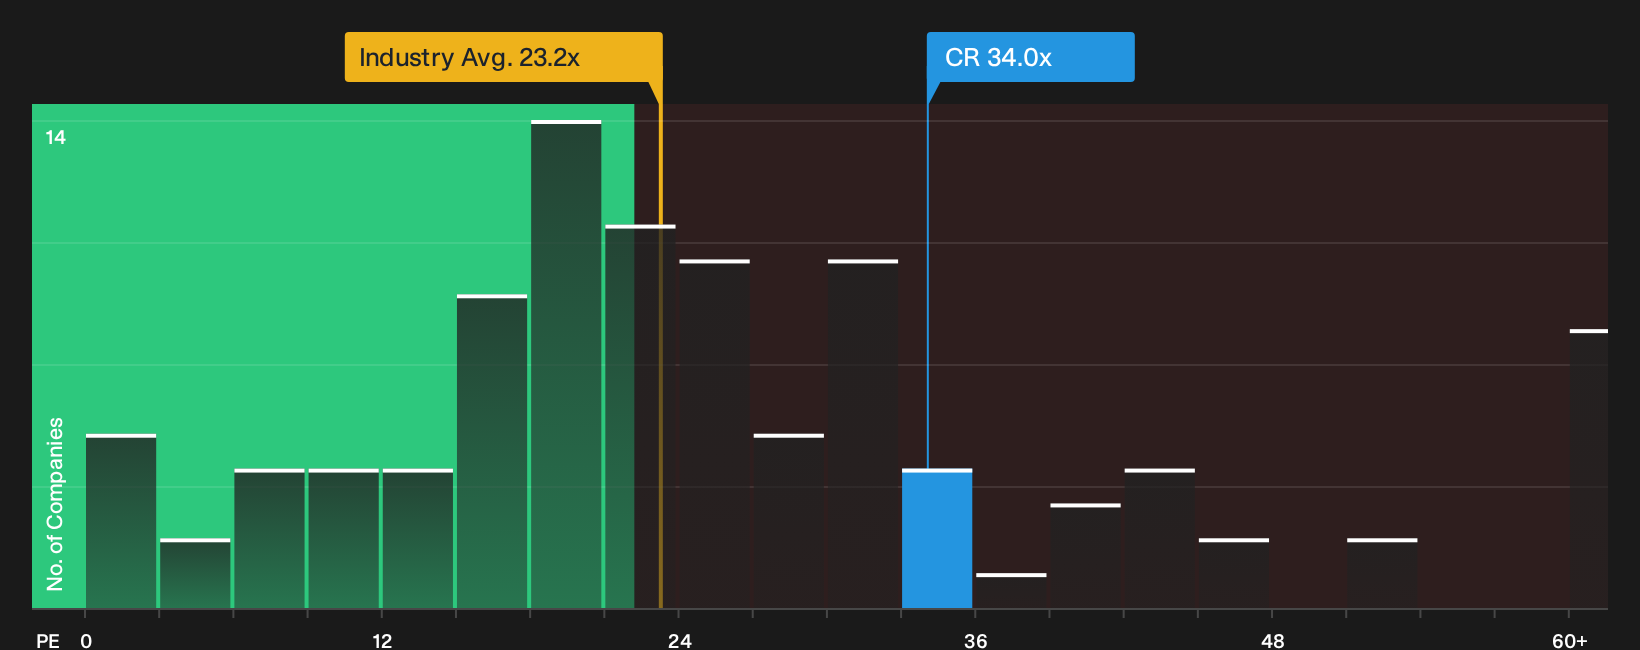
The narrative fair value of $237.20 paints Crane as undervalued, yet the current P/E of 34x tells a tougher story. It is higher than the US Machinery industry at 23.2x, peers at 27.7x and even the fair ratio of 24.6x. That premium raises a simple question: How much execution risk are you really willing to pay for?
To see how this pricing gap lines up with earnings quality and growth expectations, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Crane is mixed, which is exactly when fresh data can be most useful for independent thinkers who move before the crowd. To see what investors are currently optimistic about, review the 3 key rewards
Looking for more Crane-sized investment ideas?
Do not stop your research with Crane alone. The next opportunity rarely announces itself, and a focused stock list can save you hours of scrolling and guesswork.
- Target resilient compounding potential by scanning companies with durable earnings and price support through the 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the 40 high quality undervalued stocks and compare businesses whose fundamentals and pricing might line up more neatly.
- Zero in on balance sheet strength by filtering for companies with healthy cash and manageable debt using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com